StockWatch
·

RAJAPALAYAM MILLS LTD.-$

BSE: 532503

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27·vs Q2 FY26
Revenue
315.06
+18.3%+24.3%
Expenditure
288.69
+9.6%+19.2%
Net Profit
19.71
+1666.3%+132.4%
OPM %
17.42%
+3.39pp+0.21pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
-59.3244.30147.92251.54355.17Q2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

Rajapalayam Mills: consol PAT +33% YoY on textile turnaround, associate income soft

textile manufacturing · yarn spinning · margin expansion

ResultsQ2 FY2703 Nov 20263 minConsumer & Retail

Rajapalayam Mills textile ops turn profitable; consol PAT up 116% YoY, down 41% QoQ

textile · turnaround · associate income

ResultsQ1 FY2713 Aug 20263 minConsumer & Retail
Latest
Quarterly Result3 Nov, 12:47 pm

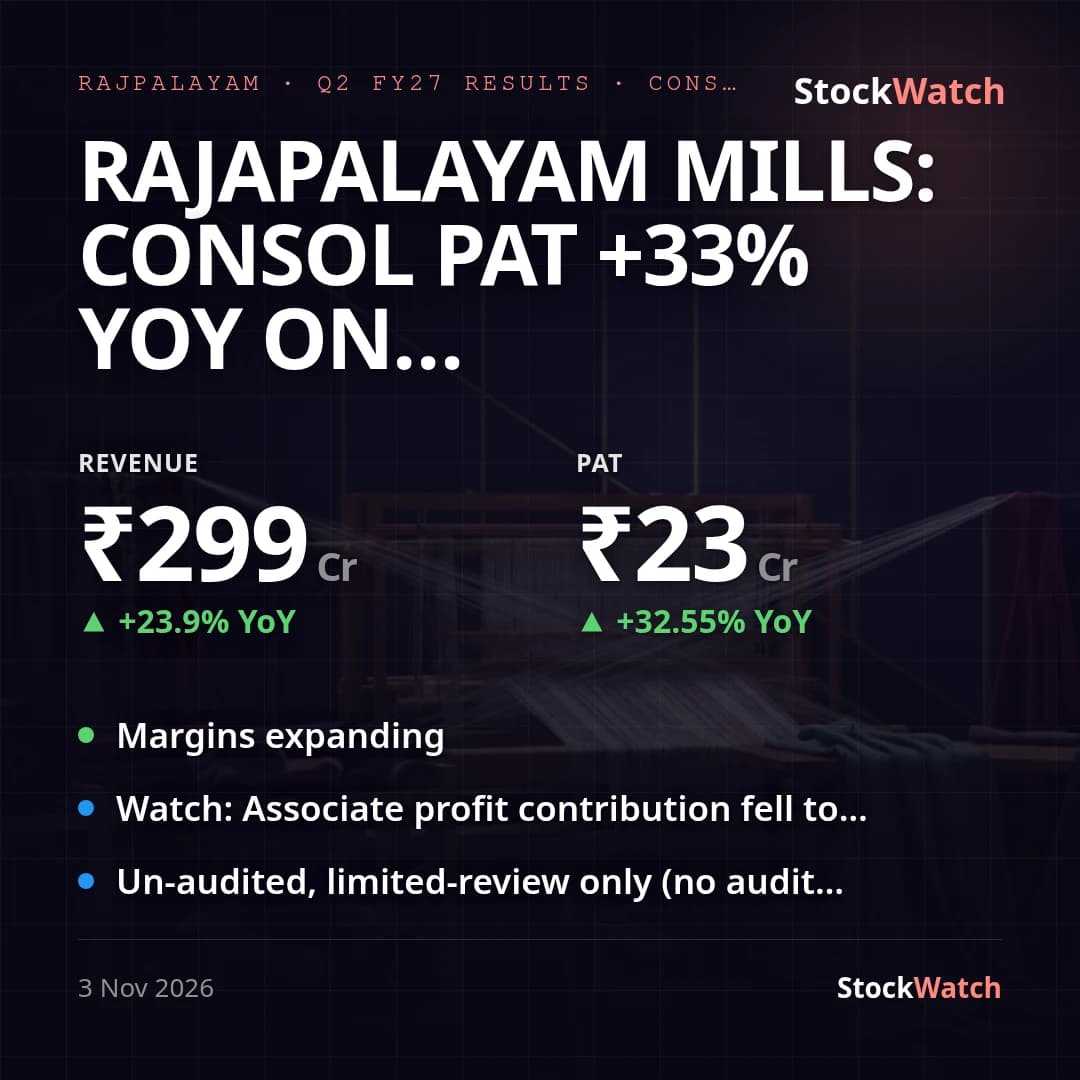
Rajapalayam Mills: consol PAT +33% YoY on textile turnaround, associate income soft

Rajapalayam Mills' consolidated PAT came in at ₹22.66 Cr for Q2 FY27, up 32.5% YoY and 29.1% QoQ, on consolidated revenue of ₹299.17 Cr (+23.9% YoY, +14.5% QoQ); consolidated EPS was ₹24.62 against ₹18.58 a year ago. The standalone print — i.e., the core textile business on its own — was far stronger: standalone PAT of ₹19.71 Cr is up 132% YoY (from ₹8.48 Cr), with standalone PBT before exceptional items jumping to ₹26.35 Cr from just ₹2.84 Cr a year earlier. That divergence matters: consolidated growth trails standalone because the equity-accounted share of associates' profit (Ramco Cements, Ramco Industries, Ramco Systems) fell to ₹12.53 Cr from ₹16.23 Cr YoY, a ~22.8% decline that diluted an otherwise much sharper textile recovery. Exceptional items (small losses on sale of property/plant) are immaterial in both periods, so this isn't a one-off-driven headline — the underlying operating improvement is real. Margins expanded on both comparisons: net margin (PAT/total income) rose to 7.42% from 6.95% YoY and 6.59% in Q1 FY27. Operating margin (EBITDA/revenue) was roughly flat YoY at ~17.4% versus ~17.2%, but recovered sharply from ~14.0% in the seasonally weaker June quarter — consistent with the textile cycle's stronger H2 demand window and improved cotton-to-yarn spreads feeding through to the standalone P&L. No formal management guidance for this quarter is on record, and no analyst consensus or brokerage preview for Q2 FY27 could be found — this is a thinly covered small-cap and the result was filed same-day with no indexed Street estimates, so both vsGuidance and vsStreet are unknown rather than inferred. No management press release or concall commentary accompanied this filing to compare against. The quarter's listed corporate-governance items (Nov 3 board meeting, trading-window closures around the results) are procedural disclosures tied to the results process itself and carry no incremental operating signal; the company's previously reported ₹400 Cr fabric-capacity expansion plan is a separate, longer-horizon strategic item not tied to this quarter's print. Going into Q3, the swing factor for consolidated numbers is whether associate income (Ramco Cements/Industries) stabilizes — a continued decline there would keep capping consolidated growth well below what the standalone textile turnaround is now delivering.

3 Nov 2026, 12:47 pm

Quarterly Result13 Aug, 12:48 pm

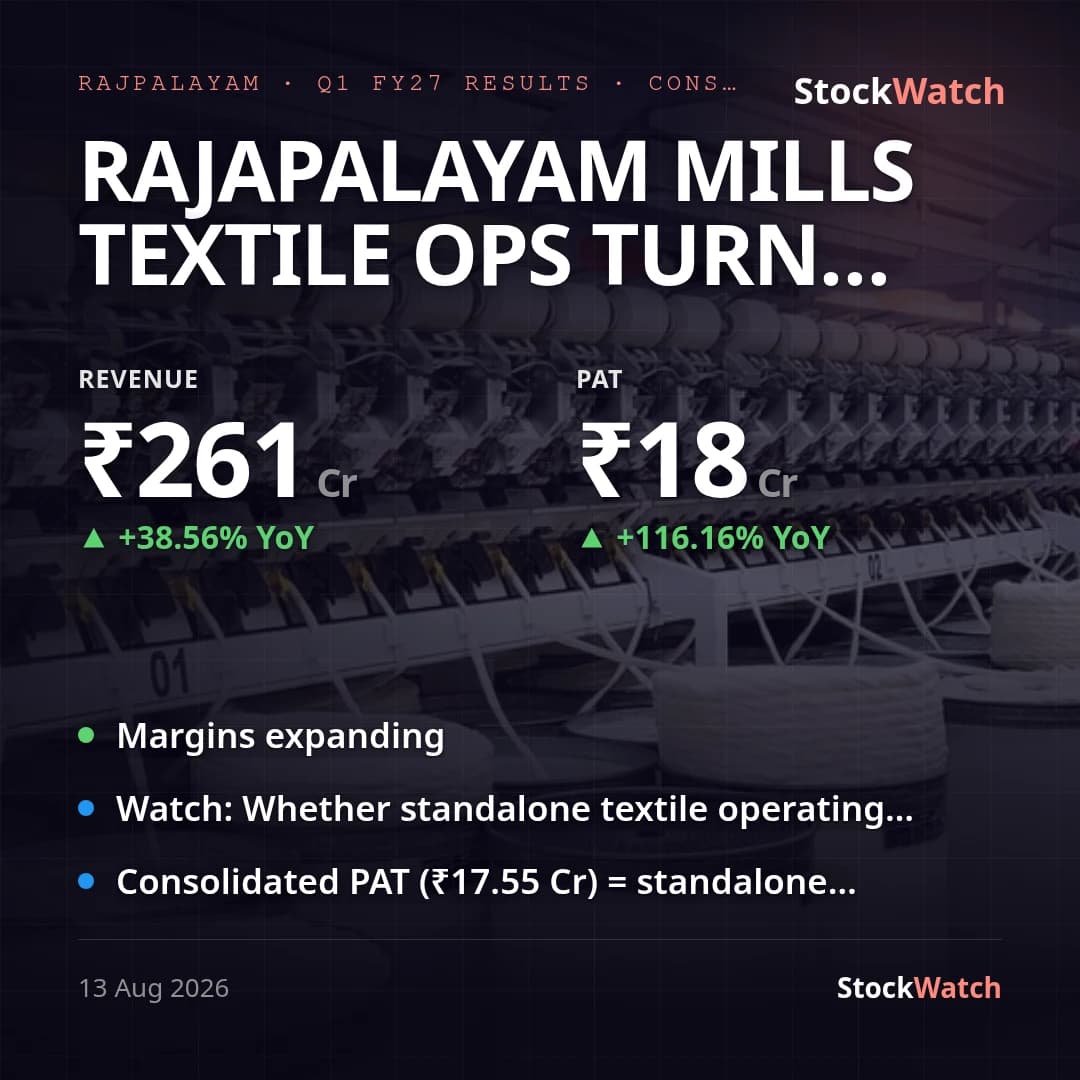
Rajapalayam Mills textile ops turn profitable; consol PAT up 116% YoY, down 41% QoQ

Rajapalayam Mills reported consolidated (primary basis) revenue from operations of ₹261.28 Cr for Q1 FY27 (quarter ended June 30, 2026), up 38.6% YoY from ₹188.57 Cr but down 3.0% sequentially from ₹269.34 Cr. Consolidated PAT was ₹17.55 Cr, up 116% YoY from ₹8.12 Cr, though down 40.7% QoQ from ₹29.61 Cr — the sequential softness stems from a lower associate-income contribution, not deterioration in the core business. Consolidated NPM improved to 6.7% from 4.2% a year ago but compressed from 10.8% in Q4 FY26. Consolidated basic EPS was ₹19.07 versus ₹8.83 a year ago and ₹32.17 last quarter. Both periods carry a small exceptional loss on sale of property/plant & equipment (₹1.01 Cr now vs ₹0.22 Cr a year ago); adjusting both periods for this, YoY consolidated PAT growth is north of 120% rather than 116% reported — the swing is real, not one-off driven. The more consequential story sits at the standalone (core textile) level. Standalone net profit before exceptional items and tax was ₹2.84 Cr this quarter, a genuine turnaround from operating losses of ₹5.27 Cr in Q4 FY26 and ₹16.07 Cr in Q1 FY26 — likely tied to input-cost (cotton) and power-cost movement given Cost of Materials Consumed, Power & Fuel and Other Expenditure are the largest expense lines, though the filing gives no line-item commentary to confirm the driver. Standalone PAT was ₹1.12 Cr, versus losses of ₹12.24 Cr a year ago and ₹3.44 Cr last quarter — still a wafer-thin 0.4% NPM on ₹261 Cr of standalone revenue. The bulk of consolidated profit — ₹16.44 Cr of the ₹17.55 Cr total — came from the company's share of profit in its associates (The Ramco Cements, Ramco Industries and Ramco Systems), down from ₹33.05 Cr in Q4 FY26, which is what drove the QoQ PAT decline despite the standalone improvement. We found no analyst previews or consensus estimates for this quarter — Rajapalayam Mills is a thinly-covered micro-cap textile name — so vsStreet is unknown; management has also issued no formal prior guidance or outlook on record, so the print cannot be graded against a stated bar, and there is no management press release in our context to cross-check framing against the numbers. Corporate developments this quarter were procedural rather than operational: the company closed its trading window ahead of results (July 15), sent out its FY26 physical annual report and AGM notice with a ₹0.50/share dividend (August 4), and has scheduled its 90th AGM for August 28, 2026 — none bear directly on the Q1 print. From the current quarter, the company has also folded its captive power segment into textile operations for internal reporting under Ind AS 108, reducing segment disclosure granularity going forward.

13 Aug 2026, 12:48 pm

Corporate Events

Board MeetingRAJPALAYAM
2026
3Nov

Board Meeting

The Board Meeting is scheduled to consider and approve the U…

BSE Filing ↗
Board MeetingRAJPALAYAM
2026
30Sep

Board Meeting

The Board of Directors considered and approved the Standalon…

BSE Filing ↗
Board MeetingRAJPALAYAM
2026
28Aug

Board Meeting

The 90th Annual General Meeting of the Company will be held …

BSE Filing ↗
DividendRAJPALAYAM
2026
21Aug

₹0.5 / share

BSE Filing ↗
Board MeetingRAJPALAYAM
2026
13Aug

Board Meeting

The Board Meeting is scheduled to consider and approve Unaud…

BSE Filing ↗
Board MeetingRAJPALAYAM
2026
28May

Board Meeting

The Board of Directors of the Company at their Meeting held …

BSE Filing ↗
Board MeetingRAJPALAYAM
2026
12Feb

Board Meeting

Consider and approve Unaudited Standalone and Consolidated F…

BSE Filing ↗
Board MeetingRAJPALAYAM
2025
10Nov

Board Meeting

Consider and approve Un-Audited Standalone and Consolidated …

BSE Filing ↗
Board MeetingRAJPALAYAM
2025
11Aug

Board Meeting

consider Inter alia the Unaudited Standalone and Consolidate…

BSE Filing ↗
Board MeetingRAJPALAYAM
2025
28May

Board Meeting

Consideration of Audited Annual Accounts for the year ended …

BSE Filing ↗
Board MeetingRAJPALAYAM
2025
7Feb

Board Meeting

Consider and approve Unaudited Standalone and Consolidated F…

BSE Filing ↗
Board MeetingRAJPALAYAM
2024
12Nov

Board Meeting

Consider and approve Un-audited Standalone and Consolidated …

BSE Filing ↗
Board MeetingRAJPALAYAM
2024
29May

Board Meeting

Consider and approve Audited Annual Accounts for the year en…

BSE Filing ↗
Board MeetingRAJPALAYAM
2024
12Feb

Board Meeting

Consider and approve Unaudited Financial Results for the Qua…

BSE Filing ↗