StockWatch
·

Scoda Tubes Ltd

BSE: 544411

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27·vs Q2 FY26
Revenue
150.94
+19.8%+1.3%
Expenditure
144.90
+21.8%+11.3%
Net Profit
4.79
-8.9%-65.7%
OPM %
10.60%
-2.25pp-4.78pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.0042.8885.76128.64171.52Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

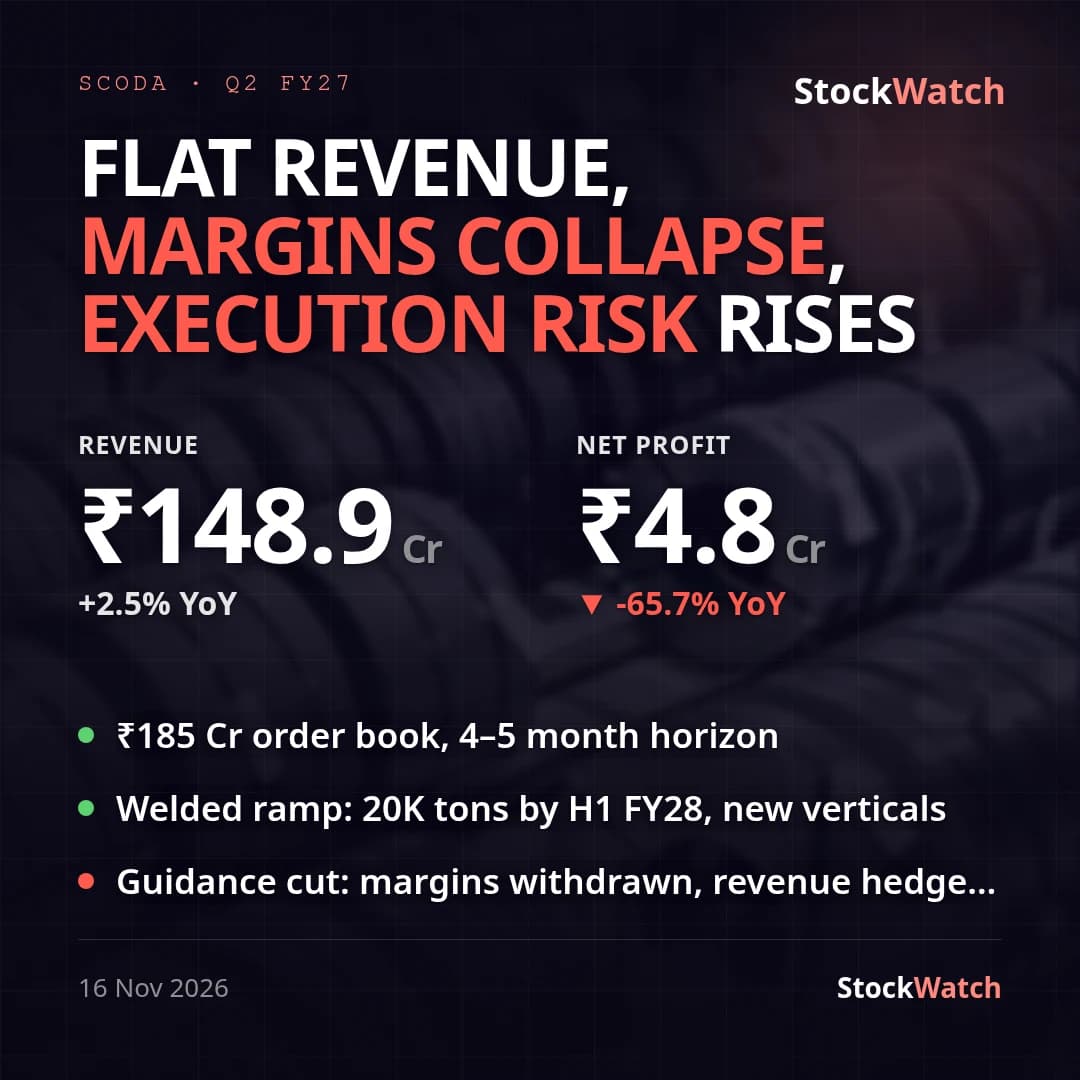
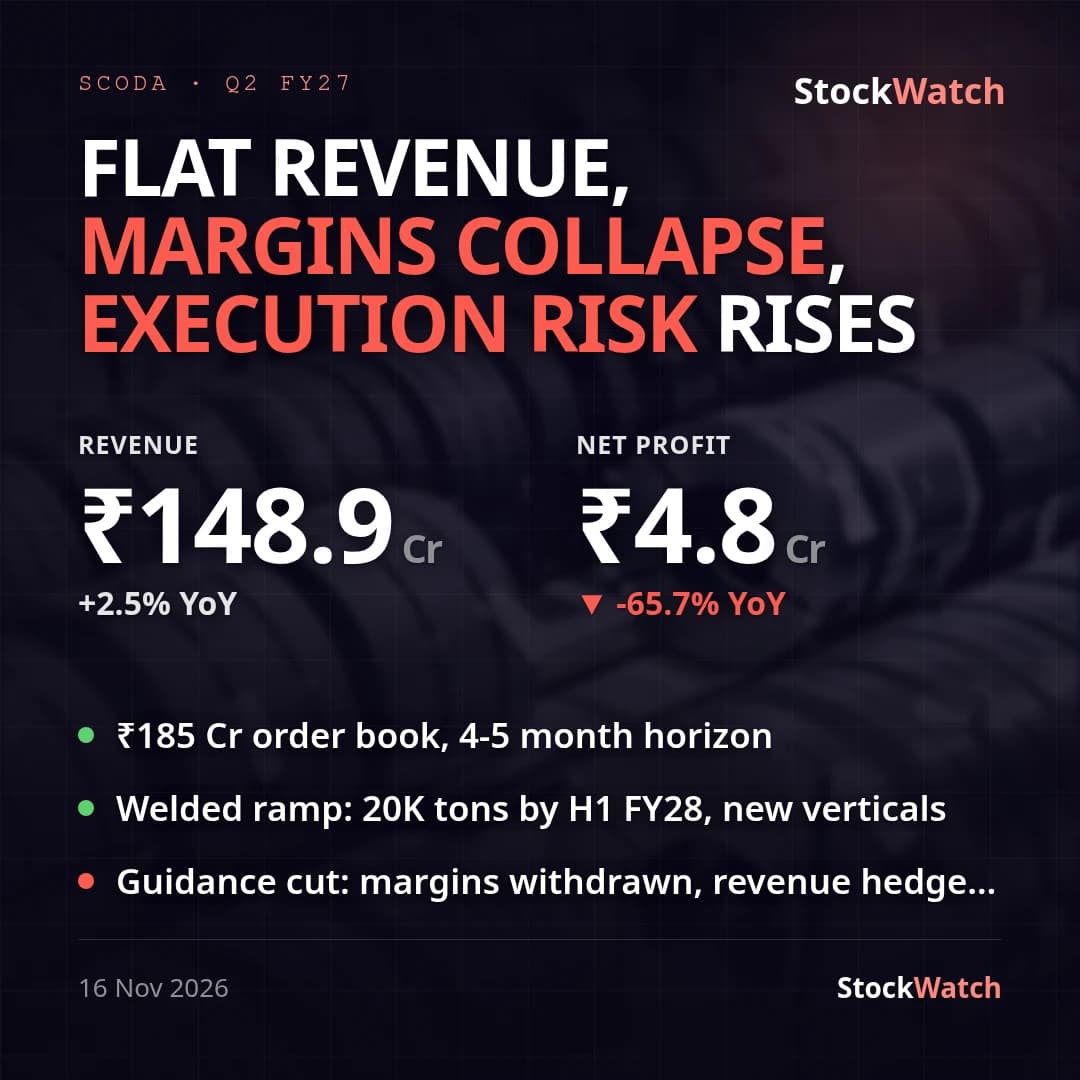
Flat Revenue, Margin Collapse, Guidance Cut — Execution Risk Now Critical

welded expansion · margin collapse · execution risk
Result verdictFollow-upQ2 FY2716 Nov 20266 minMetals & Mining

Flat quarter, margin collapse, guidance cut — ramp execution critical

capacity ramp · margin pressure · order book
TranscriptDeep diveQ2 FY2716 Nov 20266 minMetals & Mining

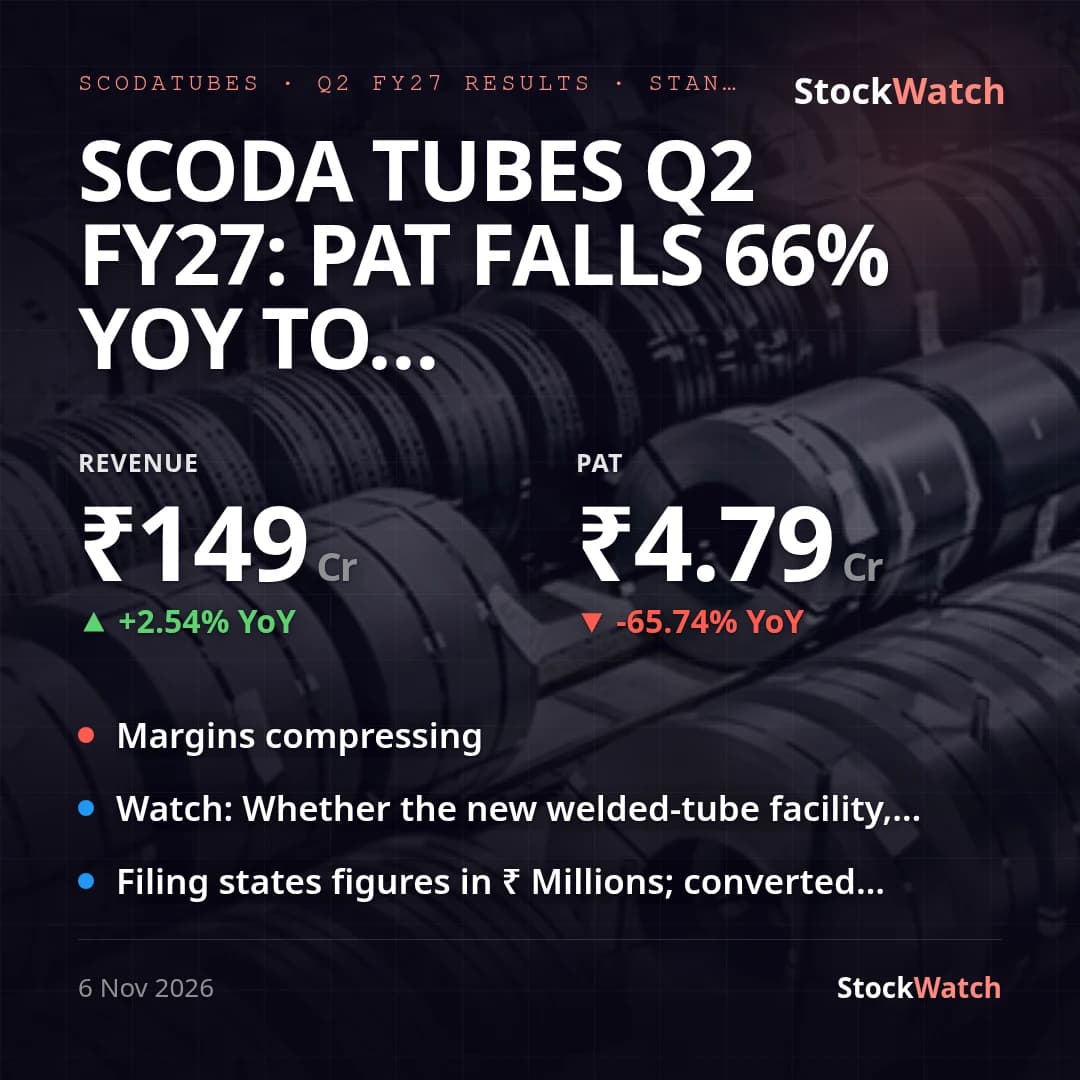
Scoda Tubes Q2 FY27: PAT falls 66% YoY to ₹4.8 Cr as capacity ramp-up costs bite margins

stainless steel pipes · capacity expansion · margin compression

ResultsQ2 FY2706 Nov 20263 minMetals & Mining
Latest
Quarterly Result6 Nov, 4:14 pm

Scoda Tubes Q2 FY27: PAT falls 66% YoY to ₹4.8 Cr as capacity ramp-up costs bite margins

Scoda Tubes' standalone PAT for Q2 FY27 fell 65.7% year-on-year to ₹4.79 Cr (from ₹13.97 Cr) even as revenue from operations rose a modest 2.5% YoY to ₹148.95 Cr. Sequentially, revenue jumped 19.8% QoQ (from ₹124.35 Cr) but PAT still slipped 8.9% QoQ (from ₹5.25 Cr), confirming the YoY profit story — not the QoQ revenue pop — is what matters here. EPS came in at ₹0.80 against ₹2.42 a year ago and ₹0.88 last quarter. There were no exceptional items in either period, so the reported and adjusted YoY moves are the same. The squeeze sits below the operating line. Operating margin (OPM) compressed to roughly 10.6% from 15.4% a year ago and about 12.9% last quarter, while net margin fell to 3.2% from 9.4% YoY. Depreciation nearly tripled YoY to ₹4.80 Cr (from ₹1.72 Cr) and finance costs rose 25.8% YoY to ₹6.93 Cr, as the company capitalises and debt-funds the new welded-tube capacity it has been building — capital work-in-progress rose to ₹45.39 Cr from ₹8.81 Cr at FY26-end, and non-current borrowings grew to ₹96.79 Cr from ₹44.06 Cr. Revenue growth has not yet caught up with these fixed costs. Against management's own FY27 guidance of 25% revenue growth and 14-15% EBITDA margins — repeated on the May 2026 concall, where the company called that target conservative and said it would revisit it in H1 FY27 — the actual H1 FY27 print (revenue up 12.6% YoY to ₹273.29 Cr, PAT down 52.3% YoY to ₹10.04 Cr) is running well short of both the growth pace and the margin band, a clear miss rather than the upgrade the prior call's confident tone implied. No formal Q2 FY27 street consensus could be confirmed this round — coverage of the stock is thin and recent brokerage reads found were inconsistent, so vs-street is left unresolved rather than guessed. No management press release accompanied this filing to cross-check against the numbers. The quarter sets up H2 FY27 as the real test: management has flagged the new welded-segment facility for commissioning in H2, and whether its ramp-up lifts volumes and margins back toward the guided 14-15% band — without a further step-up in finance costs and depreciation outpacing it — will determine if the 25% full-year growth target is still reachable or gets formally walked back.

6 Nov 2026, 04:14 pm

Corporate Events

Board MeetingSCODATUBES
2026
6Nov

Board Meeting

The meeting of the Board of Directors is scheduled to consid…

BSE Filing ↗
Board MeetingSCODATUBES
2026
4Sep

Board Meeting

The Board of Directors appointed a cost auditor and an inter…

BSE Filing ↗
Board MeetingSCODATUBES
2026
12Aug

Board Meeting

A meeting of the Board of Directors of the Company is schedu…

BSE Filing ↗
Board MeetingSCODATUBES
2026
26May

Board Meeting

The board meeting is scheduled to consider and approve the A…

BSE Filing ↗