StockWatch
·

SELAN EXPLORATION TECHNOLOGY LTD.-$

BSE: 530075

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27·vs Q2 FY26
Revenue
127.18
-3.8%+121.4%
Expenditure
50.60
+2.2%+21.4%
Net Profit
57.29
+5.5%+385.1%
OPM %
68.81%
+6.26pp+15.45pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.0037.0274.05111.07148.10Q2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

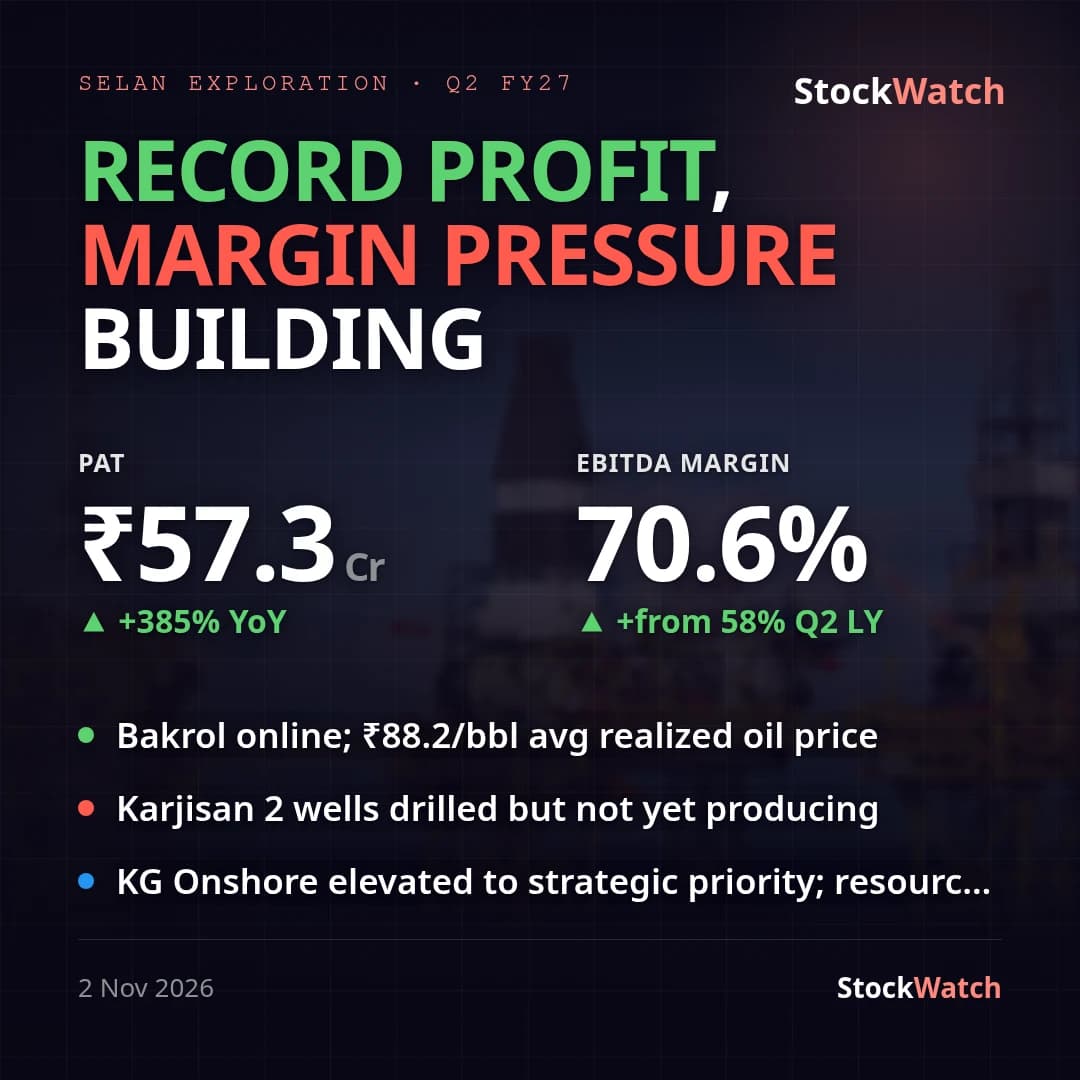
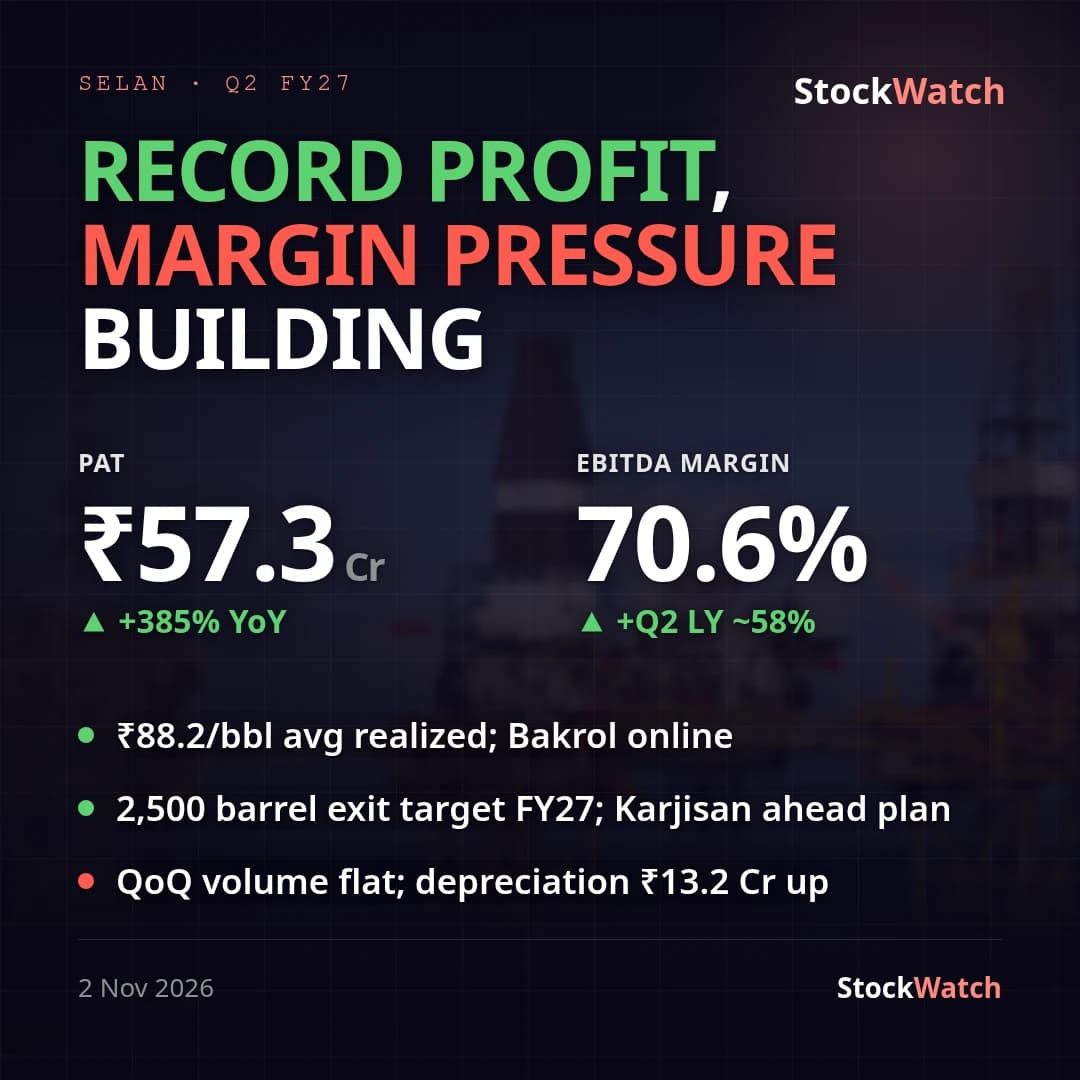
Record profit, execution risk rising — the commodity story beneath the headline

oil exploration · production ramp · commodity exposure

Result verdictFollow-upQ2 FY2702 Nov 20266 minEnergy & Oil/Gas

Strong margins from higher oil prices, but QoQ volume decline tempers near-term

production ramp · 2500 barrel exit · KG Onshore discovery

TranscriptDeep diveQ2 FY2702 Nov 20266 minEnergy & Oil/Gas

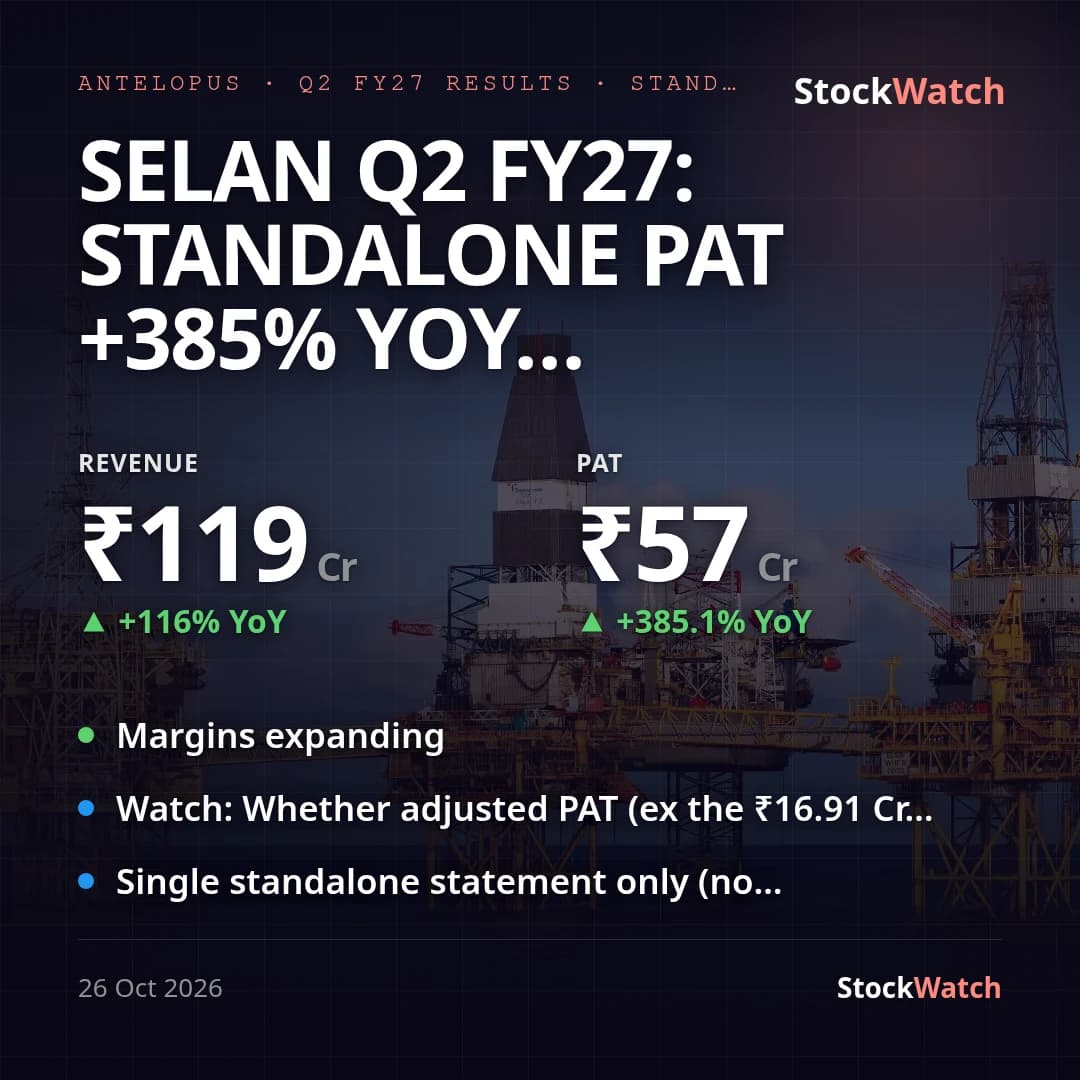
Selan Q2 FY27: standalone PAT +385% YoY to ₹57.3 Cr, revenue +116%; adj. growth ~237%

oil and gas · e&p · margin expansion

ResultsQ2 FY2726 Oct 20263 minEnergy & Oil/Gas
Latest
Quarterly Result26 Oct, 4:51 pm

Selan Q2 FY27: standalone PAT +385% YoY to ₹57.3 Cr, revenue +116%; adj. growth ~237%

Antelopus Selan Energy (formerly Selan Exploration) reported standalone net profit of ₹57.29 Cr for Q2 FY27, up 385% YoY from ₹11.81 Cr and up 5.5% QoQ from ₹54.32 Cr, on revenue (net of GoI profit-petroleum share) of ₹119.08 Cr, up 116% YoY but down 9.1% sequentially from ₹131.04 Cr. NPM expanded sharply to 45.1% from 20.6% a year ago and 41.1% last quarter. Reported growth is flattered by two identifiable, non-operating tailwinds specific to this quarter: a ₹16.91 Cr reduction in the amortisation charge from a change in the estimated useful life of oil & gas assets (effective October 2025, so absent from the year-ago base), and a ₹6.50 Cr one-off refund of excess cess remitted in FY21-23 sitting inside other income. Stripping both out and tax-effecting at the quarter's 25.2% rate, adjusted PAT works out to roughly ₹39.8 Cr, an adjusted YoY growth of ~237% — still a strong underlying print given revenue itself more than doubled, but well short of the headline +385%. The quarter also carried no exceptional item, a favourable swing against Q1 FY27's ₹10 Cr impairment provision on the Elao field CWIP, which helps explain the modest QoQ PAT gain despite the 9% sequential revenue decline. No street consensus estimate for this specific quarter could be located despite a search, and our records hold no prior formal guidance from the company; vs-street and vs-guidance are both unknown for this print. Separately, web reporting on the FY26 annual results (announced May 2026) indicates management's working FY27 production target of 2,500 boepd (versus a ~1,880 boepd March-2026 exit rate), via a seven-well Karjisan campaign, the remaining eight wells of the ten-well Bakrol FDP, and commercial oil flow at the Duarmara field — but this filing discloses no quarterly production volume, so progress against that target cannot be graded from the numbers here. On the corporate-action front, the company received DGH approval for two new Discovered Small Field Round-IV blocks (KG onshore in Andhra Pradesh, Cambay onshore in Gujarat), with Revenue Sharing Contracts formally signed on October 22, 2026 — expanding exploration acreage beyond the existing Bakrol/Lohar/Cambay/Elao base, though with no near-term P&L impact. No separate management press release was available in the context for this result; the filing's own notes are the only management commentary on record for the quarter.

26 Oct 2026, 04:51 pm

Board Meeting27 Jul, 6:10 pm

Selan Q1FY27: PAT up 384% YoY to ₹54.3 Cr as NPM hits 41%, even after ₹10 Cr impairment

Antelopus Selan Energy (formerly Selan Exploration) reported standalone Q1 FY27 (quarter ended June 30, 2026) net profit of ₹54.32 Cr, up 384% year-on-year from ₹11.22 Cr and up 43% sequentially from ₹38.08 Cr, on net revenue from operations of ₹131.04 Cr (+158.8% YoY, +28.5% QoQ). Net profit margin expanded sharply to 41.1% of total income from 20.9% a year ago and 36.7% last quarter. The quarter carries a one-off: a ₹10.00 Cr exceptional impairment against capital work-in-progress on the Elao Field, taken because DGH approval for further development on the field is still pending. Excluding this charge, adjusted PAT would be roughly ₹64.3 Cr, an adjusted YoY growth of ~473% versus the 384% reported — so even on a like-for-like basis the underlying jump is real and not an artefact of the one-off, which if anything held the reported number back. The margin expansion was driven by revenue outpacing a nearly flat cost base: total expenses were ₹49.50 Cr versus ₹53.25 Cr last quarter and ₹38.56 Cr a year ago, with employee benefits expense and other expenses both falling roughly in half sequentially even as royalty and cess (which scales with realizations) rose to ₹21.01 Cr from ₹11.97 Cr. Depreciation and amortisation was ₹10.33 Cr for the quarter; per the auditor's note, a revised 10-year extension estimate on the Bakrol, Lohar and Cambay field PSCs (effective October 2025) is lowering the amortisation charge by ₹11.93 Cr this quarter, a tailwind that will recur each quarter going forward rather than a one-time item. There is no formal management guidance or prior concall commentary in our records for this filing, and no broker/Street estimate could be located for this specific quarter (this is a micro-cap oil & gas explorer with limited formal coverage) — both vsGuidance and vsStreet are marked unknown rather than assumed. Company communications reviewed via web search indicate a FY27 production target of ~2,500 boepd under a self-funded growth plan, but the filing itself carries no production/volume disclosure to check progress against that target this quarter. Two other quarter-specific items stand out: a GST/Cess appellate order (received May 6, 2026) allowed a refund of ₹6.56 Cr for FY2020-23, of which ₹6.50 Cr was originally expensed — this has NOT been recognised in the P&L pending the actual refund order, so it is a potential future credit, not booked upside. Separately, the Cambay Field remaining 50% participating-interest talks with Synergia Energy remain stalled: the exclusivity period lapsed and the Share Purchase Agreement was unexecuted as of March 31, 2026, with no update in this filing. The board also flagged a promoter-group shareholder reclassification request the same day, a governance item unrelated to the P&L print.

27 Jul 2026, 06:10 pm

Corporate Events

Board MeetingANTELOPUS
2026
26Oct

Board Meeting

The meeting of the Board of Directors is scheduled to consid…

BSE Filing ↗
Board MeetingANTELOPUS
2026
27Jul

Board Meeting

The Board of Directors will consider a request for reclassif…

BSE Filing ↗
Board MeetingANTELOPUS
2026
27Jul

Board Meeting

The meeting of the Board of Directors of the Company is bein…

BSE Filing ↗
Board MeetingANTELOPUS
2024
29Oct

Board Meeting

Consider and approve Unaudited Financial Results

BSE Filing ↗
Board MeetingANTELOPUS
2024
12Feb

Board Meeting

Consider and approve Unaudited Financial Results of the Comp…

BSE Filing ↗
Board MeetingANTELOPUS
2023
16Oct

Board Meeting

Consider and approve Unaudited Financial Results for the qua…

BSE Filing ↗
Board MeetingANTELOPUS
2023
12Aug

Board Meeting

Consider and approve Unaudited Financial Results for Q1 FY 2…

BSE Filing ↗
Board MeetingANTELOPUS
2023
11Aug

Board Meeting

Consider and approve the Unaudited Financial Results of the …

BSE Filing ↗