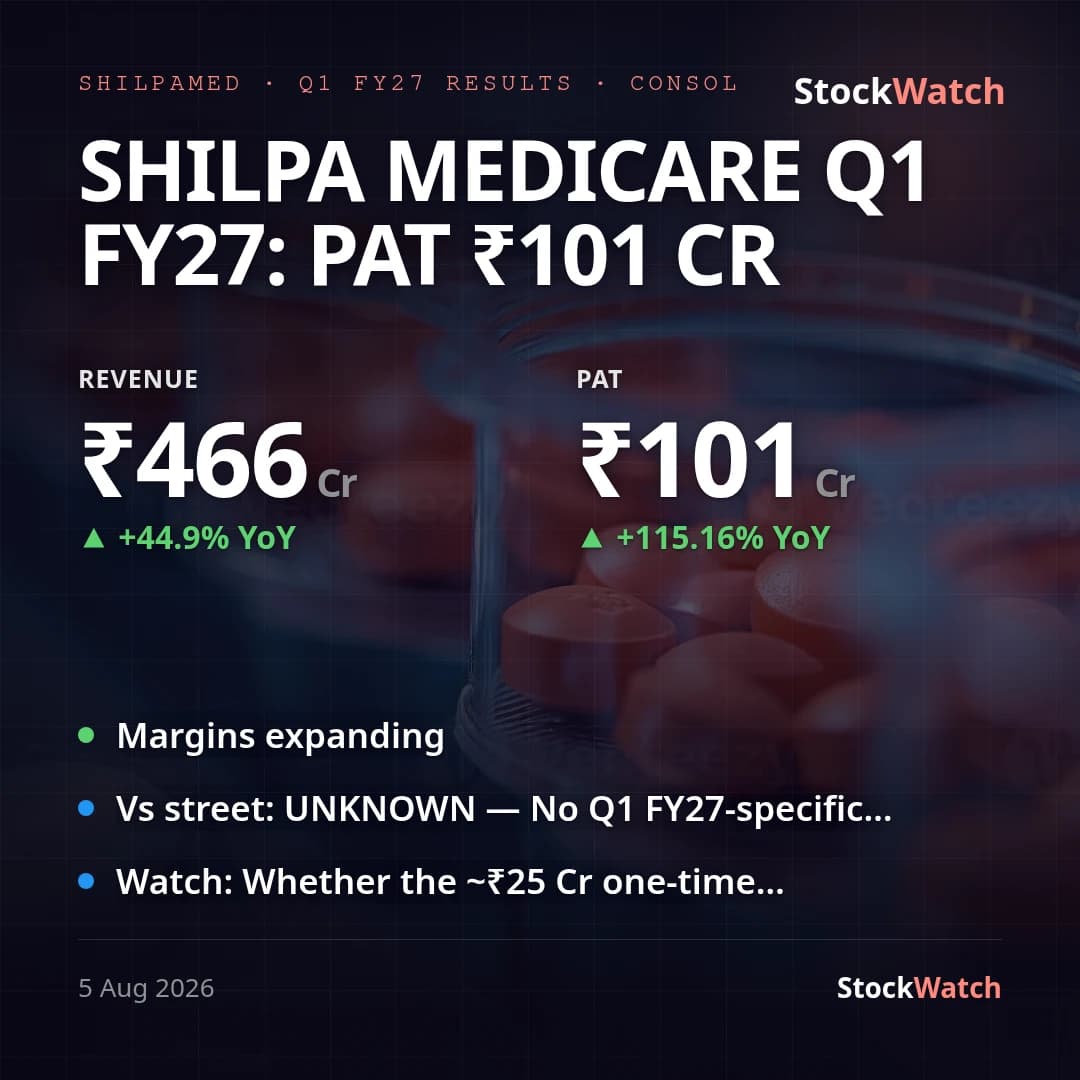
Shilpa Medicare Q1 FY27: PAT ₹101 Cr, +115% YoY but adjusted growth ~61% ex tax boost
On a consolidated basis (primary), Shilpa Medicare's Q1 FY27 revenue rose 44.9% YoY to ₹465.78 Cr (₹321.46 Cr a year ago) and 6.6% QoQ (₹436.99 Cr in Q4 FY26). Reported PAT more than doubled YoY to ₹100.88 Cr (+115.2%) but eased 6.4% QoQ from ₹107.79 Cr. The YoY PAT jump is not a clean operating story: tax expense flipped to a net credit of ₹2.83 Cr this quarter (from ₹269 lakhs YoY) after a one-time deferred-tax liability reversal of roughly ₹25.36 Cr, booked after the company remeasured deferred tax balances under the new income-tax regime (Section 200, Income-tax Act 2025). Stripping that reversal out, adjusted PAT is closer to ₹75.5 Cr, putting adjusted YoY PAT growth at roughly +61% — still strong and ahead of revenue growth, but well short of the 115% headline.
Margins tell a similar story: reported consolidated NPM expanded to 21.7% from 14.3% a year ago (24.6% in Q4 FY26), but on an adjusted basis NPM is closer to 16.2% — a smaller but genuine YoY gain, and a step down from an adjusted ~18.9% in Q4 FY26 (which itself carried a ₹25.02 Cr exceptional gain). The underlying expense ratio did improve — total expenses fell to 80.4% of total income from 84.7% a year ago — consistent with operating leverage as revenue scaled, and consolidated PBT also got a modest lift from JV/associate income swinging to +₹5.96 Cr from -₹0.73 Cr a year ago. Standalone PAT of ₹64.92 Cr (+247% YoY) grew far faster than consolidated, but that divergence is largely a base effect: standalone Q1 FY26 carried a ₹5.18 Cr exceptional loss while this quarter carries a ₹3.51 Cr exceptional gain, in addition to the same tax reversal — the two bases are not comparable without adjustment.
Management issued no separate press release with this filing (none available at the time of this analysis), and no formal quantitative guidance exists on record — the only prior signal is the Q4 FY26 concall's qualitative confidence in FY27 growth from complex APIs, specialty formulations, biologics, ADCs and CDMO capacity, without numbers attached. This quarter's revenue and adjusted-PAT growth are directionally consistent with that framing, and it coincided with the commissioning of an integrated ADC GMP manufacturing facility at Shilpa Biologicals (June 24) and a Nivolumab biosimilar partnership with Orion Corp (June 30) — both consistent with the CDMO/biologics build-out management flagged. Leadership churn at the Biologicals subsidiary continued in parallel: its CEO resigned for personal reasons on July 15 and a replacement was appointed August 3, alongside a ₹9 Cr legal-settlement disclosure at the same subsidiary on June 24. No Q1 FY27-specific street estimate could be located; the only consensus figure found was an annual FY27 EPS estimate of ~₹13.75, not comparable to a single quarter.
Going into Q2 FY27, the key question is durability: whether the ~61% adjusted YoY PAT growth and the modest underlying margin gain persist once the tax reversal is a one-quarter event, and whether the new ADC/CDMO capacity and biosimilar partnership begin contributing measurably to revenue.