Shiprocket EBITDA turns positive in debut print; net loss narrows 24% YoY to ₹13.7 Cr
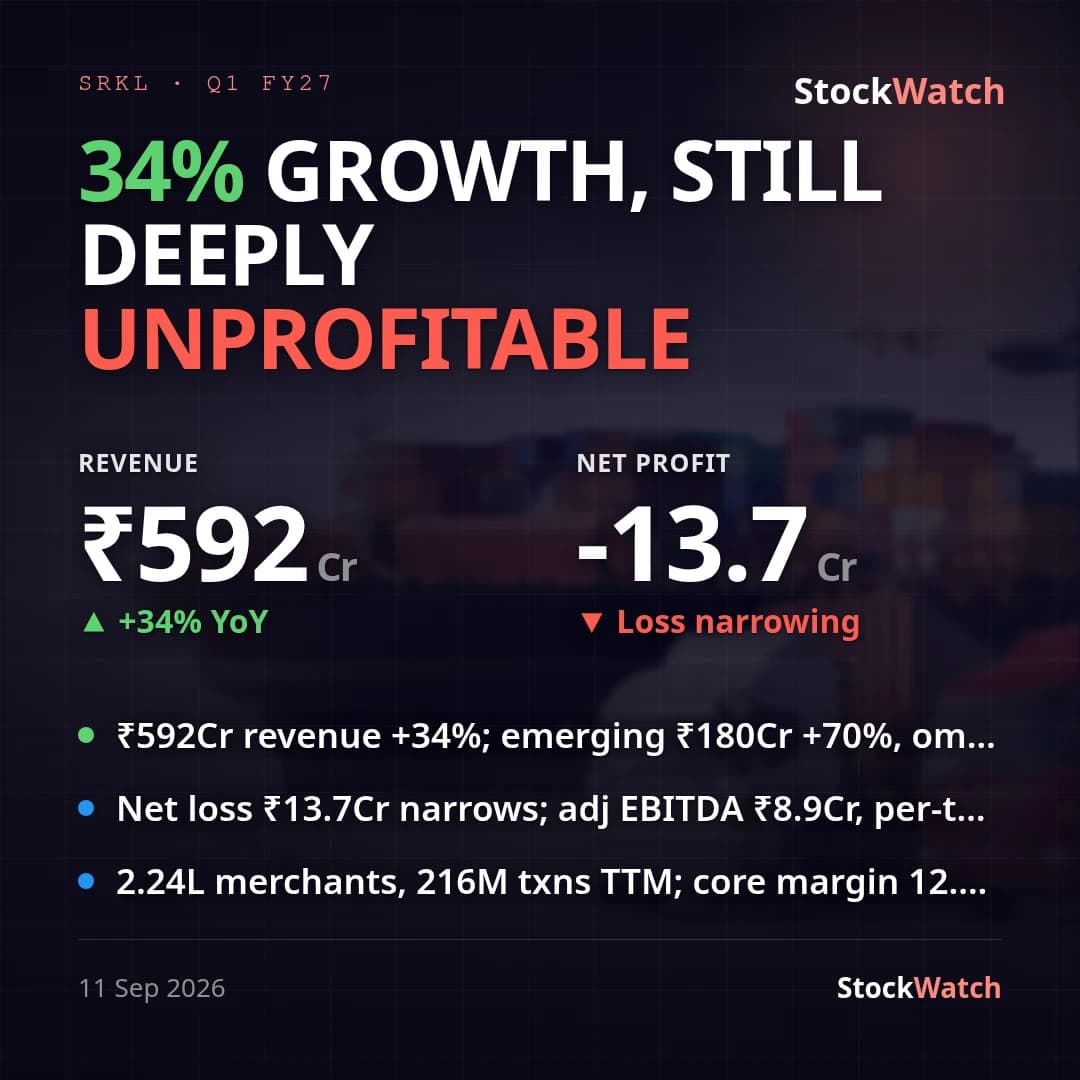
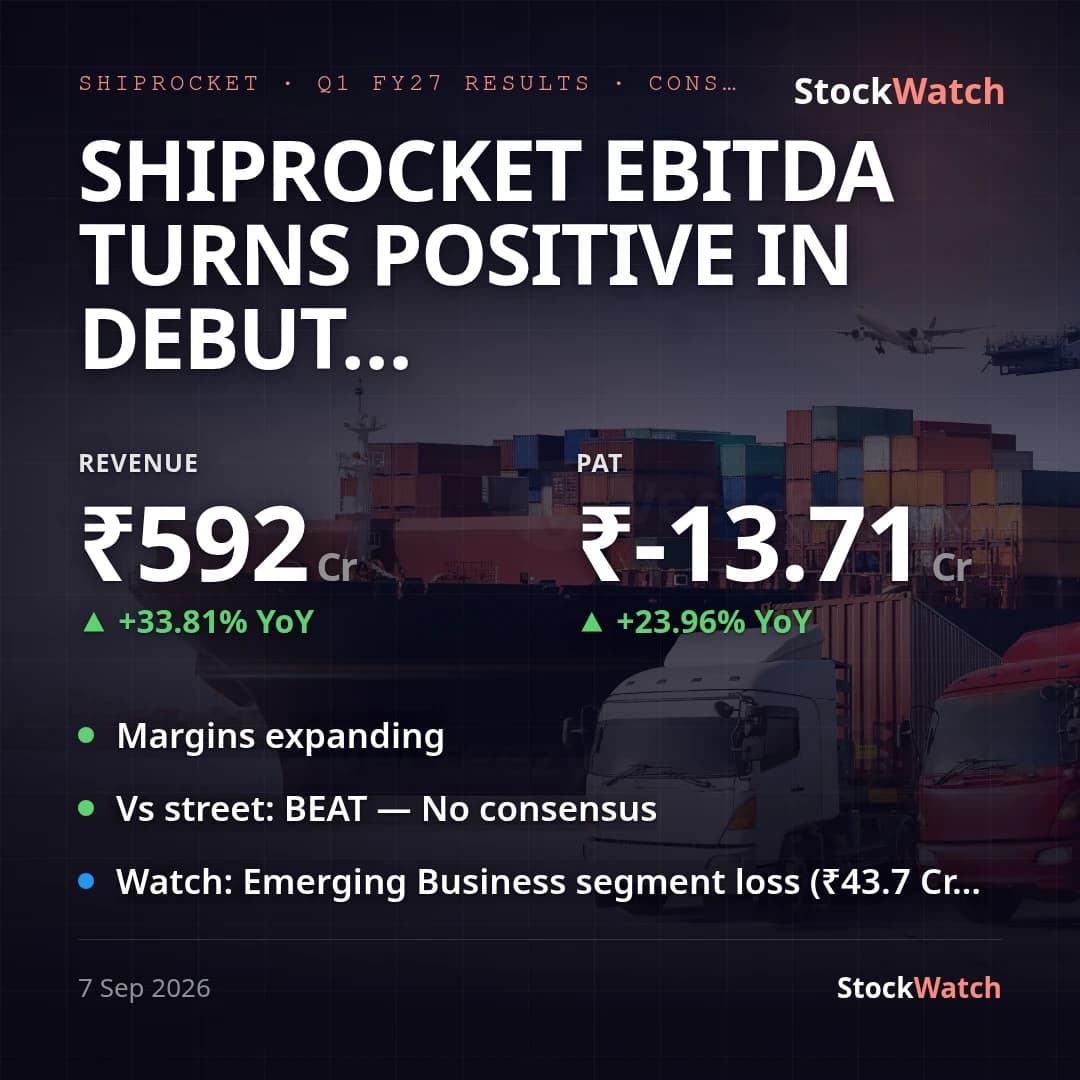
Shiprocket's maiden quarterly report as a listed company shows a consolidated Q1 FY27 loss of ₹13.7 Cr on revenue of ₹592.1 Cr (+33.8% YoY, +6.8% QoQ), above the ₹560–580 Cr revenue range flagged in our pre-result preview. The bigger surprise was operating profitability: EBITDA (PBT plus finance cost and depreciation) turned positive at ₹2.8 Cr, versus a ₹1.8 Cr EBITDA loss a year ago — well inside, in fact ahead of, the preview's expected ₹5–8 Cr EBITDA-loss range, a clear beat on the metric flagged as the quarter's real test. The bottom line still shows red because ₹28.5 Cr of non-cash employee share-based payment (SBC) expense sits above the EBITDA line; strip that out and the quarter is operating-profitable.
Growth was led by the newer Emerging Business segment (Omuni, international, ads and finance), up 70.2% YoY to ₹180.3 Cr, while the steadier Core Business (merchant-solutions/logistics) grew 22.3% YoY to ₹411.7 Cr and lifted its segment profit to ₹52.7 Cr from ₹41.3 Cr a year ago. Emerging Business losses widened too, however — to ₹43.7 Cr from ₹40.3 Cr YoY and ₹43.0 Cr QoQ — so group profitability is still held back by the newer bets even as the core logistics engine scales toward steady margins. Net loss narrowed 24% YoY (from ₹18.0 Cr) and 16% QoQ (from ₹16.3 Cr).
Standalone (parent-only, ex-subsidiaries) numbers diverge materially: the entity posted a ₹20.2 Cr profit (EPS ₹0.31) versus a loss a year ago, confirming the consolidated loss originates entirely in subsidiaries (Pickrr, Shiprocket Omuni, Shiprocket Pte/Inc, Logitrust). Management has no formal quantitative guidance on record — this is the first quarterly disclosure since the August 19, 2026 listing — and analyst coverage remains thin post-IPO with no verifiable independent consensus estimate, so the pre-result preview is the primary benchmark used here. Alongside the results, the board also approved BSR & Co. LLP as statutory auditor (replacing S.R. Batliboi) for a five-year term and ratified the ESOP 2016 and ESOP 2024 pools — the same ESOP charge that is currently the single biggest drag between EBITDA and net profit.
Two threads carry into Q2 FY27: whether Core Business segment margin (~12.8% of segment revenue, up from ~12.3% YoY) keeps expanding, and whether Emerging Business losses stabilize as those verticals scale — both explicitly flagged as watch items in our pre-result preview and still unresolved. Management's September 8, 2026 analyst call is the first chance to hear commentary on GMV, merchant count and ARPU, none of which were disclosed in this filing.