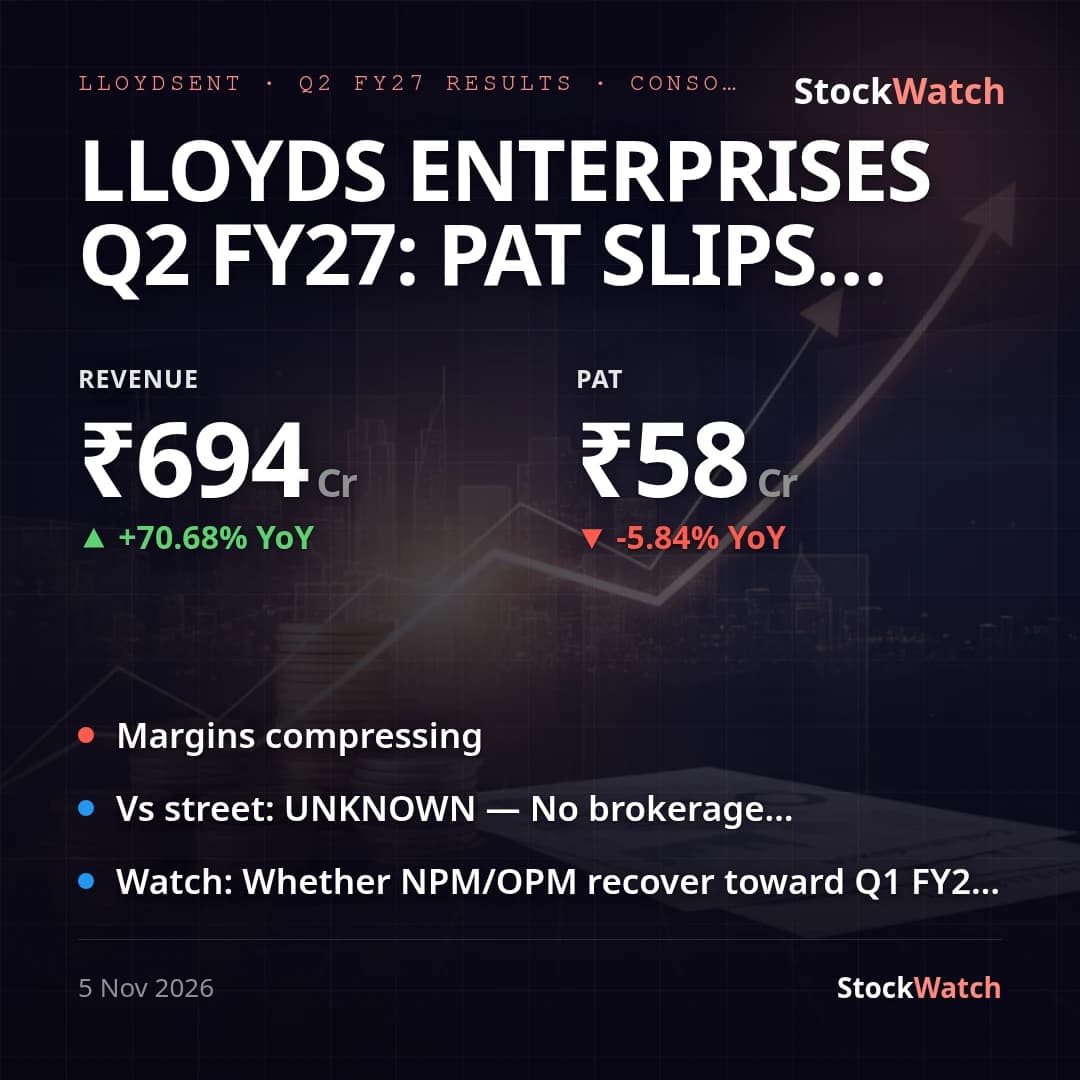
Lloyds Enterprises Q2 FY27: PAT slips YoY, margins squeeze on SISCOL-led revenue surge
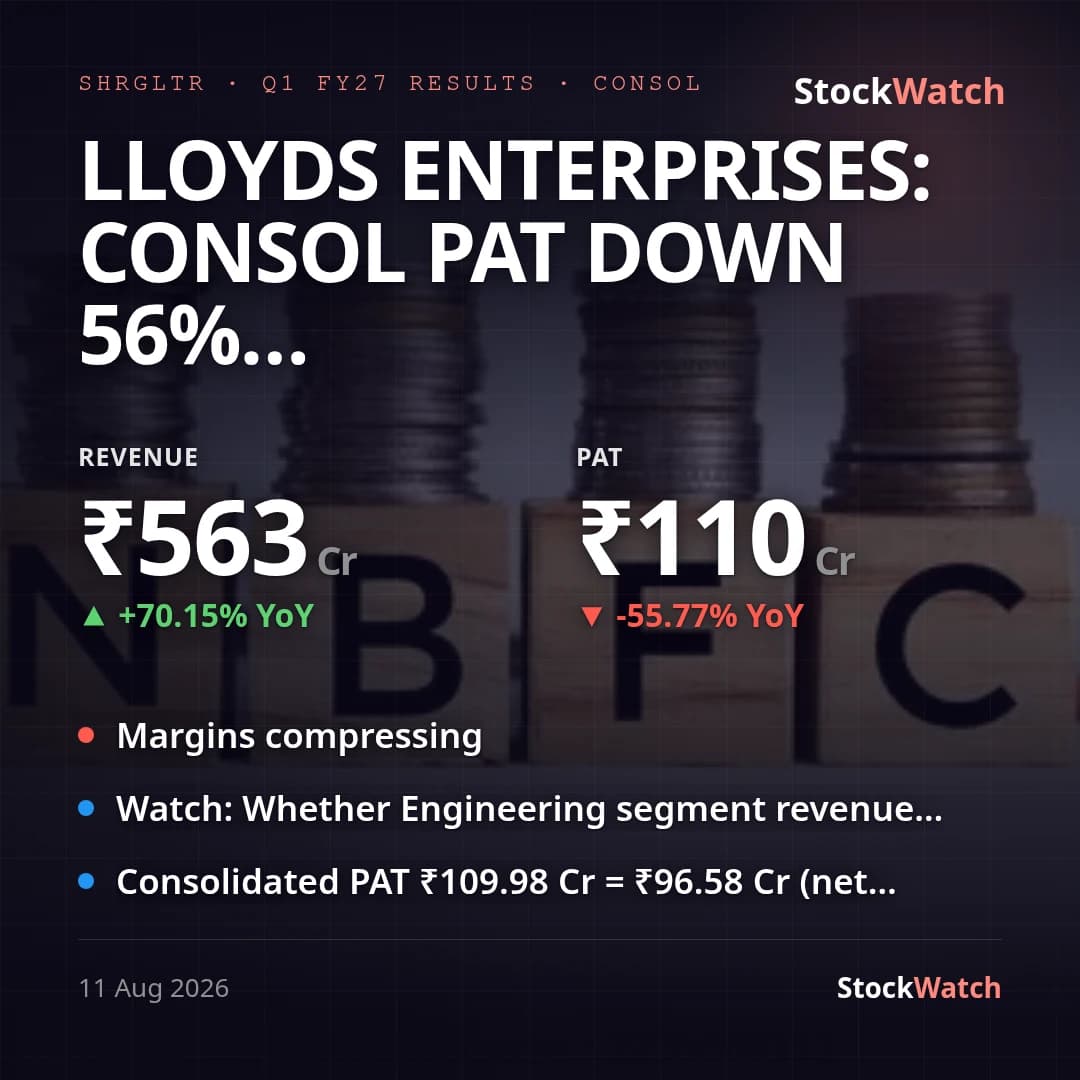
Lloyds Enterprises' consolidated revenue jumped 70.7% YoY to ₹693.91 Cr (₹406.57 Cr) and 23.3% QoQ (₹563.03 Cr), but the group's own notes flag this as not comparable: step-down subsidiary Steel Infra Solutions (SISCOL) entered the consolidation only from August 17, 2026, inflating the topline. Bottom line moved the other way — consolidated profit for the period fell 5.8% YoY to ₹58.23 Cr (₹61.84 Cr) and 47.1% QoQ (₹109.98 Cr), so revenue growth did not translate into profit growth even before adjusting for one-offs. PBT carried a ₹4.16 Cr charge from the SEBI settlement order dated September 29, 2026 (settled without admission of guilt); stripping that out, adjusted PAT is roughly flat YoY (+0.9%) rather than down 5.8% reported — a meaningfully better underlying picture, though still a sharp sequential slowdown from Q1 FY27's ₹109.98 Cr print. Critically, of the ₹58.23 Cr group profit, only ₹13.70 Cr accrues to Lloyds Enterprises' own shareholders — ₹44.53 Cr (76%) goes to non-controlling interests, up sharply from roughly 47% in Q1 FY27 — so the headline consolidated number overstates what flows to the parent's shareholders this quarter.
Margins compressed on both comparisons: net margin nearly halved to 7.89% from 18.17% in Q1 FY27 and 13.84% a year ago, while operating margin eased to 7.24% from 15.69% QoQ (though still up from 5.83% YoY). Finance costs more than doubled QoQ-adjusted and were up over 5x YoY (₹22.24 Cr vs ₹4.33 Cr) on fresh borrowings including the ₹219 Cr Tata Capital facility taken for the SISCOL acquisition, directly pressuring the bottom line. Segment data shows Engineering remains the core driver of both revenue (₹583.55 Cr, +88.6% YoY) and profit (₹70.10 Cr, 87% of total segment result), but Steel segment profit crashed to ₹5.71 Cr from ₹44.22 Cr in Q1 FY27 (-87% QoQ) despite revenue there rising to ₹110.11 Cr from ₹46.74 Cr, and the Electrical segment swung to a ₹4.21 Cr segment loss from a small profit a year ago. Standalone (parent-only) results underline how subsidiary-dependent the group is: standalone PAT was just ₹5.32 Cr, down 82% YoY from ₹30.05 Cr, versus the ₹693.91 Cr / ₹58.23 Cr consolidated figures.
No brokerage consensus or formal estimate for this quarter turned up in a web search, so vs-Street is unknown rather than assumed; the company also has no prior formal guidance on record for this quarter, and no management press release accompanying this filing was available to cross-check against the numbers. Corporate developments in the quarter tie directly into the print: the SEBI settlement (₹4.16 Cr) hit the P&L as noted above; the Board approved forfeiture of 3,35,552 partly-paid rights-issue shares for unpaid call money; and the company granted 1.35 lakh fresh ESOPs on October 19, 2026, alongside the completed SISCOL stake build (Lloyds Engineering Works now holds 51.70% directly, with the group's aggregate economic interest at 69.57%) — the transaction that both drove the revenue surge and the step-up in non-controlling interest.
Going into Q3 FY27, the quarter sets up three things to verify: whether margins recover toward Q1 FY27's levels once SISCOL is consolidated for a full quarter rather than ~45 days; whether the 76% non-controlling-interest share of profit (vs ~47% in Q1) normalizes, since that ratio determines what Lloyds' own shareholders actually earn; and whether Steel segment profitability returns to anything near its Q1 FY27 run-rate or whether ₹5.71 Cr on ₹110 Cr of revenue is the new baseline.