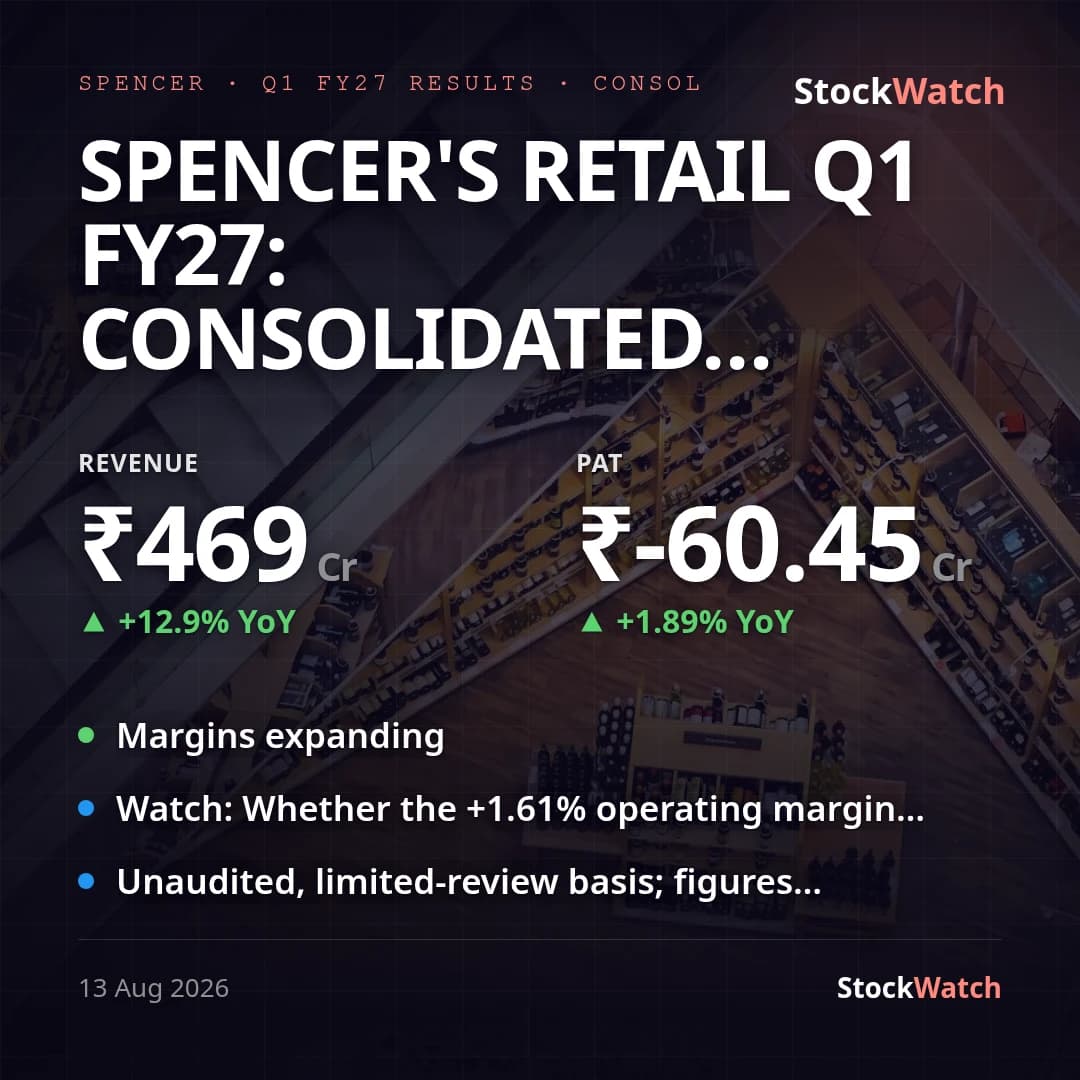
Spencer's Retail's consolidated (primary) revenue from operations for Q1 FY27 (quarter ended June 30, 2026) rose 12.9% YoY to ₹469.47 Cr (₹415.84 Cr) and 7.6% QoQ (₹436.15 Cr) — the QoQ pickup in a retail business is partly seasonal and shouldn't be read as the headline signal. The company posted a consolidated net loss of ₹60.45 Cr, only marginally narrower than the ₹61.61 Cr loss a year ago (-1.9%) and the ₹65.58 Cr loss in Q4 FY26 (-7.8%). Net margin improved to -12.83% of total income from -14.42% YoY and -14.72% QoQ. The more meaningful shift is at the operating level: EBITDA (revenue less cost of goods, employee costs and other opex, before finance costs and depreciation) turned positive at +1.61% of revenue this quarter, versus -1.60% a year ago and -1.64% last quarter — the first positive print in this comparison window. Standalone (parent-only) numbers were smaller in scale: revenue of ₹407.94 Cr and a net loss of ₹34.03 Cr, roughly half the consolidated loss, indicating the subsidiaries add revenue but widen the group's overall loss.
Management's May 2026 concall guidance was to reach EBITDA breakeven within FY27 on the back of store productivity, inventory efficiency, the rewards program and judicious online expansion, targeting 8% store EBITDA and minimal reliance on other income; this quarter's swing to positive operating margin (ex-finance costs and depreciation) is consistent with that trajectory, so the operating-margin checkpoint reads as on track even as the bottom line stays loss-making. No formal analyst/street estimates for this quarter turned up in a web search — Spencer's Retail carries no visible sell-side coverage for Q1 FY27 — so vsStreet is unknown. The line still weighing on the P&L is finance costs, which rose 15.8% YoY to ₹46.43 Cr (₹40.10 Cr) even as management had guided to no significant increase in interest costs pending planned debt refinancing — a point of tension against the prior outlook; depreciation was roughly flat (₹23.45 Cr vs ₹23.01 Cr in Q4 FY26, down from ₹26.31 Cr a year ago). On the specific Nature's Basket turnaround management flagged last quarter, the subsidiary's results show just ₹7.88 Cr of revenue against a ₹6.81 Cr net loss this quarter — a loss nearly the size of revenue, with no visible progress yet. The results are unaudited, subject to limited review by S.R. Batliboi & Co. LLP, with no exceptional items disclosed in either statement.