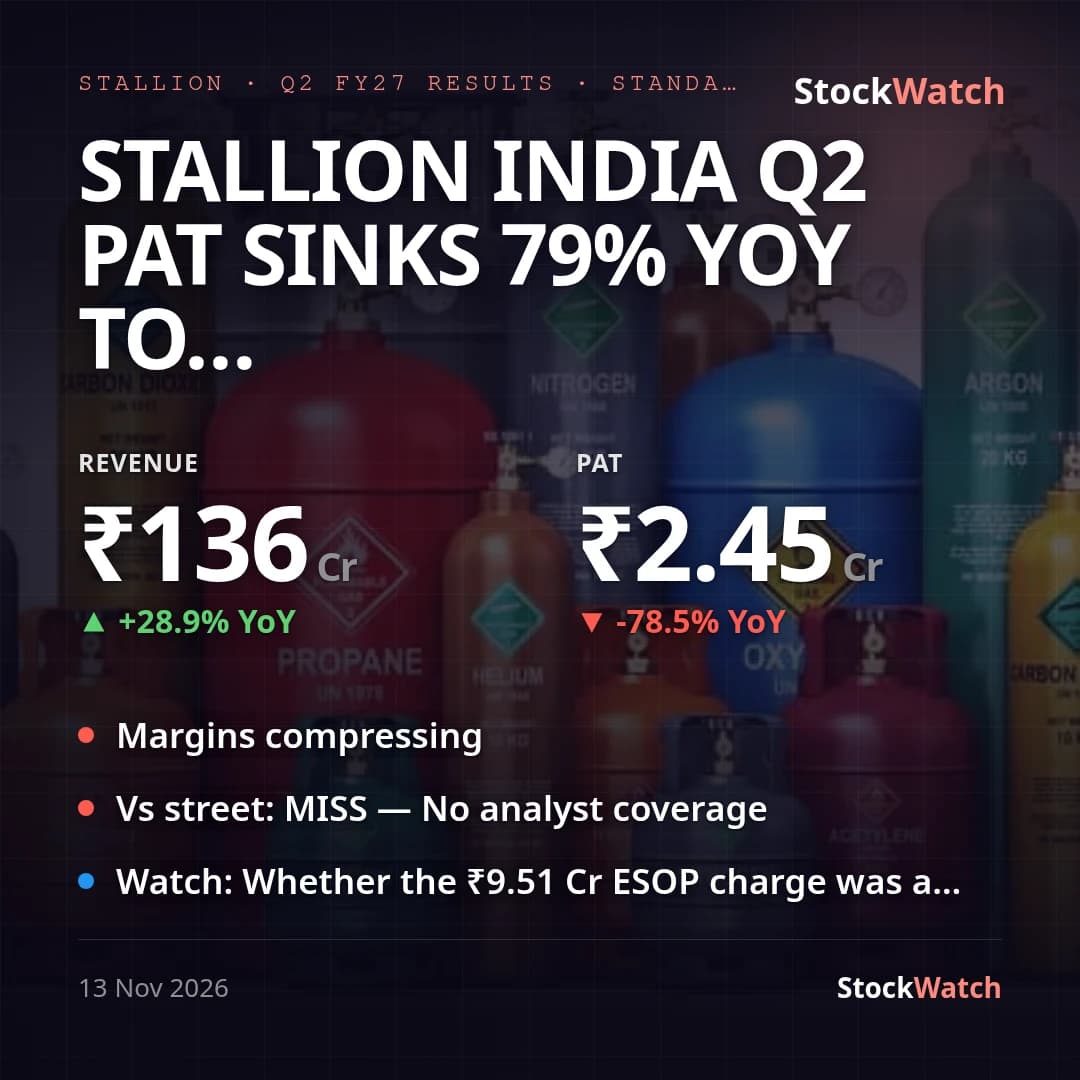
Stallion India Q2 PAT sinks 79% YoY to ₹2.45 Cr as input costs, ESOP charge crush margins
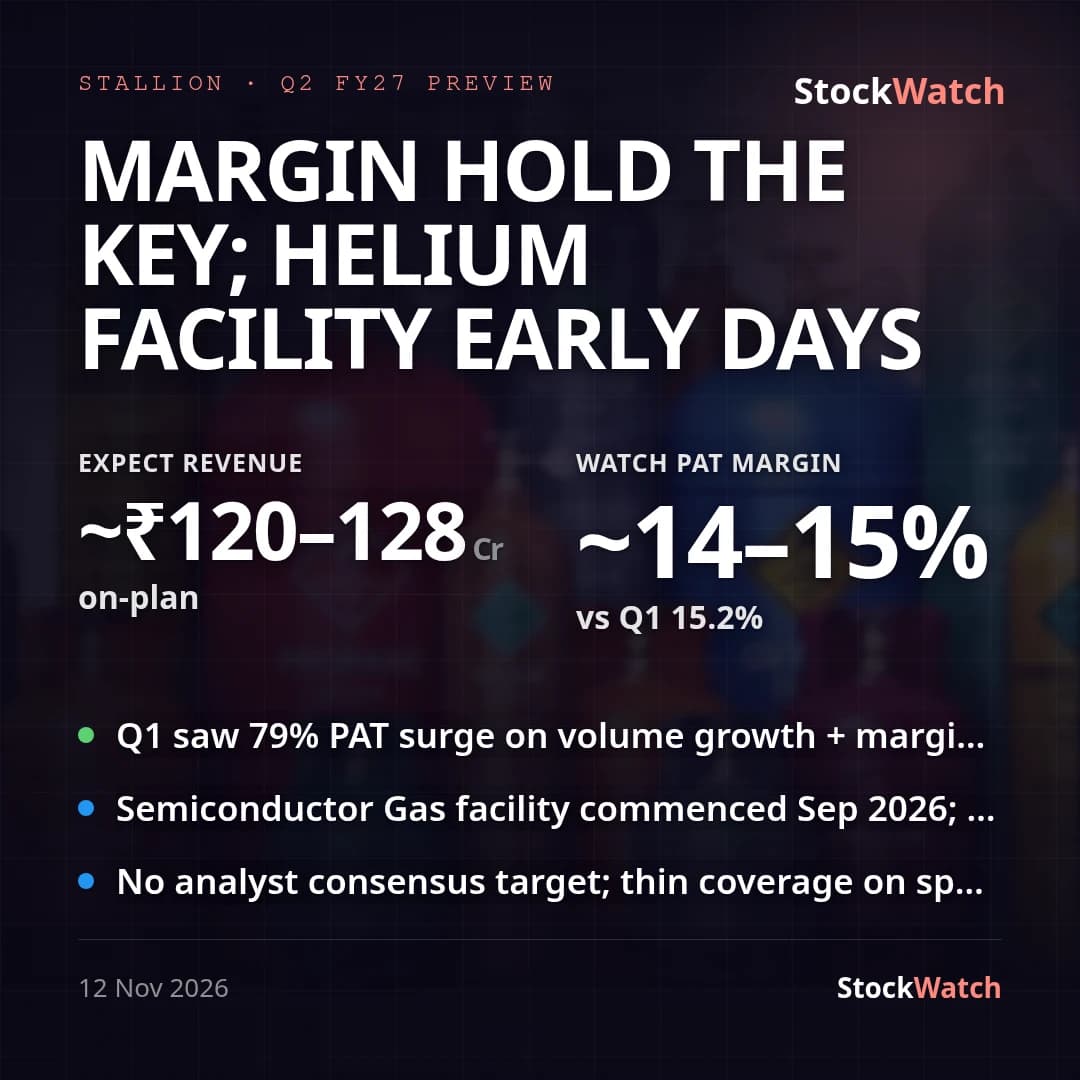
Stallion India Fluorochemicals' standalone Q2 FY27 print is a clear miss on profitability even as revenue held up: revenue from operations grew 28.9% YoY (and 12.0% QoQ) to ₹136.03 Cr, ahead of our pre-result on-plan range of ₹120-128 Cr, but PAT collapsed 78.5% YoY and 86.8% QoQ to just ₹2.45 Cr, with EPS falling to ₹0.21 from ₹1.60 in Q1 FY27 and ₹1.42 a year ago. There is no formal sell-side coverage on this stock (0 analysts per public trackers), so the only external yardstick is our own preview, which had flagged ~14-15% PAT margin and ~₹20-23 Cr EBITDA as the on-plan bar; actual PAT margin came in at 1.8% and reported EBITDA (PBT less other income, plus finance costs and depreciation) at just ₹2.98 Cr — a clear miss on profitability despite the revenue beat.
Two factors drove the collapse. First, a one-off: the company booked a ₹9.51 Cr non-cash ESOP expense (15,86,505 options granted at a Black-Scholes fair value of ₹128.69/option) entirely within Q2, per Note 5 of the filing — this alone explains most of the ~5x jump in employee costs. Adjusting for it, PAT would have been roughly ₹11.96 Cr, a YoY growth of just +4.8% (essentially flat) rather than the reported -78.5%. Second, and more concerning, raw material costs consumed 88.2% of revenue this quarter versus 62.5% in Q1 FY27 and 75.1% in the year-ago quarter — even stripping out the ESOP charge, OPM works out to roughly 9.2%, still down sharply from 18.15% in Q1 FY27 and 14.75% a year ago. Management's prior guidance (Q1 FY27 concall) had called for EBITDA margins to improve 3-4 percentage points over the medium term; this quarter moved in the opposite direction by several hundred basis points even on an adjusted basis, a direct miss against that outlook. Revenue growth of 28.9% YoY is roughly tracking, if a touch below, the guided 30-35% three-year revenue CAGR.
No management press release or concall commentary for this specific quarter is available in our records, so there is no company framing to cross-check against the numbers beyond the filing itself. The quarter's other disclosed developments — commercial start-up of the Semiconductor Gas facility at Khalapur (Sept 21, 2026) and conclusion of a GST inspection with tax paid (Oct 15, 2026, quantum not separately disclosed in this filing) — sit alongside the print but aren't yet visible as margin drivers; the semiconductor ramp is still early. Half-year PAT (₹21.02 Cr) is down 3.5% YoY despite 19.2% YoY revenue growth to ₹257.48 Cr, showing the margin pressure is not confined to a single quarter's optics.