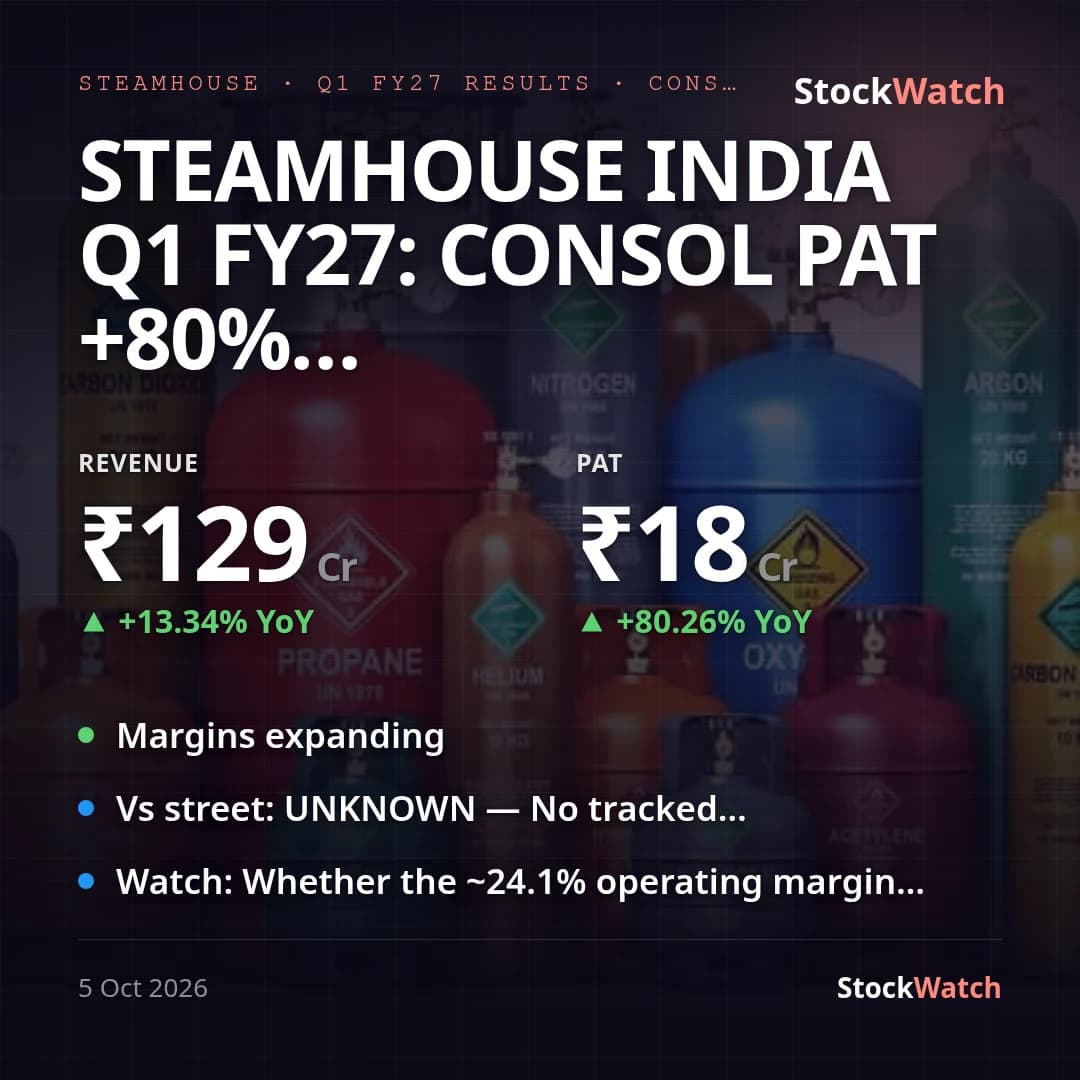
Steamhouse India's first quarterly print since its September 17, 2026 listing shows a strong start: consolidated revenue from operations rose 13.3% YoY to ₹128.62 Cr (June 30, 2025: ₹113.48 Cr), while PAT climbed 80.3% YoY to ₹18.34 Cr (₹10.18 Cr) — profit growing roughly six times faster than revenue. Sequentially, revenue dipped 7.1% QoQ even as PAT rose 30.1% QoQ, so the sequential profit jump is a margin story, not a volume one; with no exceptional items in either the current or comparative periods, the growth is fully operating in nature.
The margin bridge is the real story: net profit margin expanded to 14.26% from 8.97% a year ago and 10.18% last quarter, while EBITDA-level operating margin rose to roughly 24.1% — above the ~23% level management has pointed to as its historical/target operating margin (FY26 full-year OPM was 16.99%). Cost of materials, stock-in-trade purchases and other expenses grew slower than revenue even as employee costs and depreciation ticked up with capacity additions. Finance costs rose to ₹6.92 Cr as the company carries Tranche-1 of ₹50 Cr drawn against a ₹75 Cr sanctioned NCD programme, alongside a ₹50 Cr preferential equity placement (68.49 lakh shares at ₹73) that lifted paid-up capital to ₹46.57 Cr during the quarter.
There is no tracked sell-side consensus for this print — Steamhouse listed barely two weeks before the quarter closed and has no analyst coverage on record, so a vs-Street read is not assessable; the company gives no formal quarterly guidance either, but its own October 5 commentary calls Q1 FY27 "the strongest performance in the Company's journey," citing steam-supply volume growth of 11.52% QoQ and 16.70% YoY — directionally consistent with the reported numbers, though volumes outpaced revenue, implying some pricing/mix drag worth watching. The quarter also sits ahead of a ₹311 Cr EPC & O&M mandate win announced September 24, 2026, which is not yet in these numbers but is relevant to the order pipeline heading into Q2 FY27.