Studds Q1 FY27: consolidated PAT falls 39% YoY as input-cost inflation squeezes margins
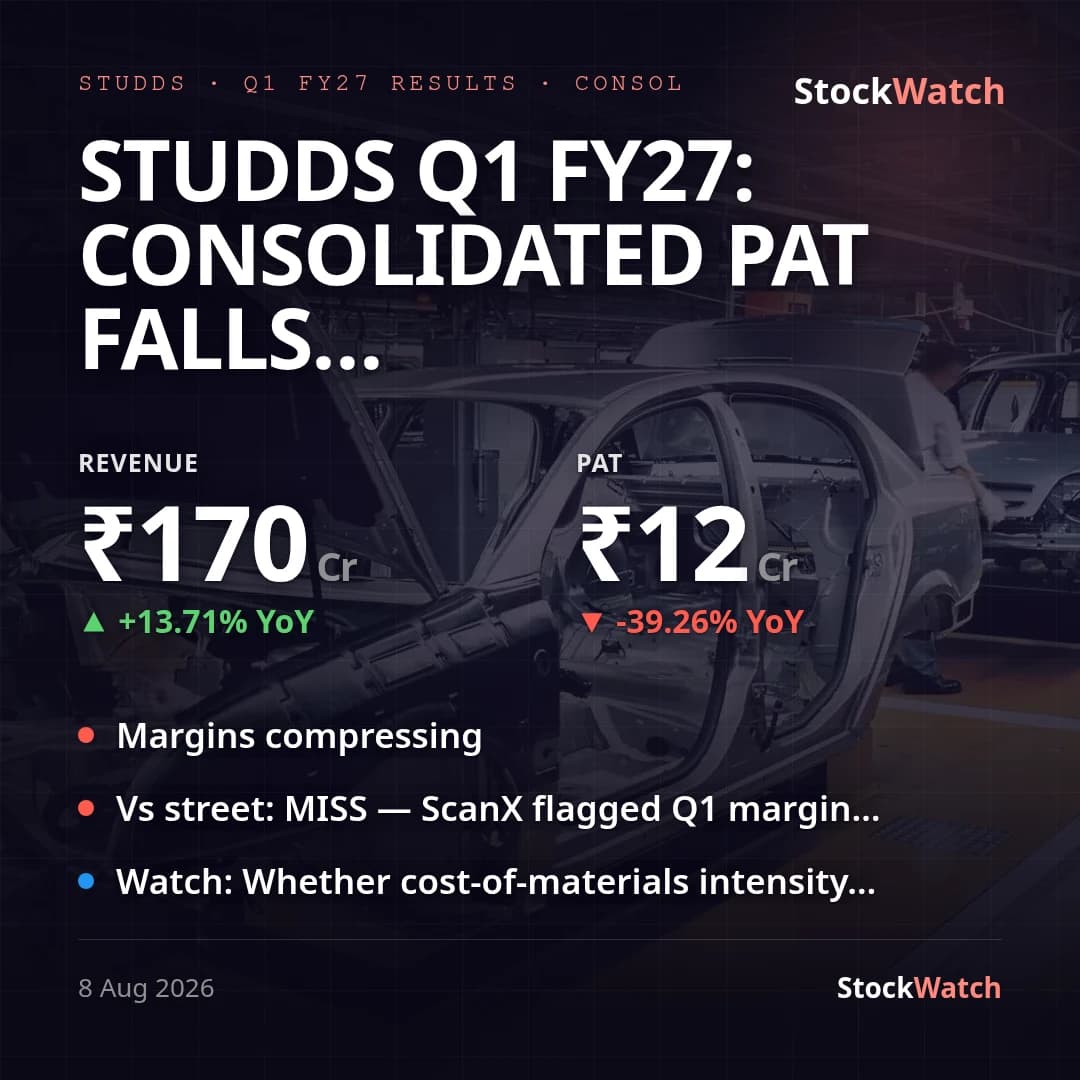
Studds Accessories' Q1 FY27 print is a clear miss on profitability: consolidated PAT fell 39.3% YoY to ₹12.30 Cr (from ₹20.25 Cr) and 41.7% QoQ (from ₹21.10 Cr), even as consolidated revenue grew 13.7% YoY to ₹169.68 Cr. Standalone tells a similar but less severe story — PAT down 35.2% YoY to ₹13.25 Cr on revenue up 12.7% YoY to ₹166.94 Cr — the roughly 4-point gap between the two traces to the two new wholly-owned subsidiaries dragging the consolidated line. No exceptional items were booked in either the current or year-ago quarter, so this is a genuine underlying margin story, not a one-off distortion.
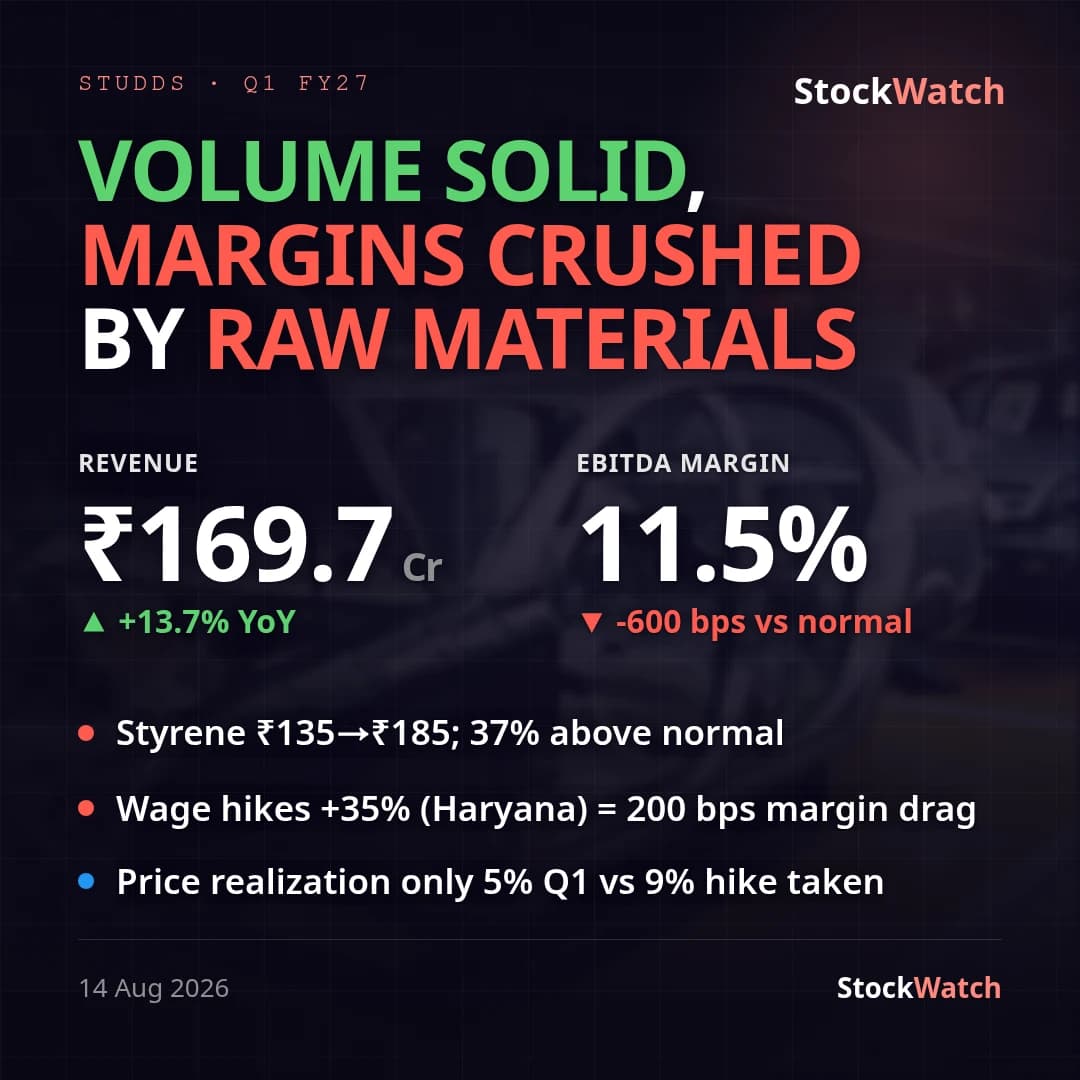
The squeeze sits almost entirely on the cost-of-materials line: consolidated cost of materials consumed rose 32.9% YoY to ₹81.03 Cr against 13.7% revenue growth, pushing material intensity from 40.9% to 47.8% of revenue and pulling consolidated net profit margin (PAT/total income) down to 7.1% from 13.3% a year ago and 12.4% last quarter. Employee costs (+14.5% YoY) and other expenses (+24.8% YoY) also outgrew revenue, though materials remain the dominant driver — consistent with a helmet manufacturer facing plastics/resin input-cost inflation. Adding to the drag, the two new subsidiaries — Bikerz US Inc. (₹3.54 Cr revenue, ₹0.18 Cr net loss) and newly incorporated SMK Helmets Europe SRL (no revenue yet, ₹0.90 Cr net loss) — together cost the Group ₹1.08 Cr this quarter, explaining most of the standalone-consolidated divergence.
The result runs against management's own May 2026 concall guidance of 17-18% FY27 revenue growth with margins "broadly similar" to the prior year — Q1's 13.7% YoY growth trails that pace, and margins compressed rather than held. Ahead of the print, analysts had specifically flagged near-term margin pressure from elevated input costs and initial European set-up expenses (ScanX earnings-call preview), which is exactly what materialised; but the broader FY27 analyst expectation of 15-20% full-year PAT growth now looks stretched after a quarter where consolidated PAT fell 39% YoY. No separate management press release was available with this filing to check against the numbers directly. The quarter also carried a CFO transition (Manish Mehta stepped down, Bharat Goyal appointed effective July 1, 2026) and board approval for further capital infusion into both loss-making subsidiaries — EUR 10 lakh into SMK Helmets Europe SRL and USD 99,936 into Bikerz US Inc — signalling continued investment in the international build-out despite the near-term cash drag.