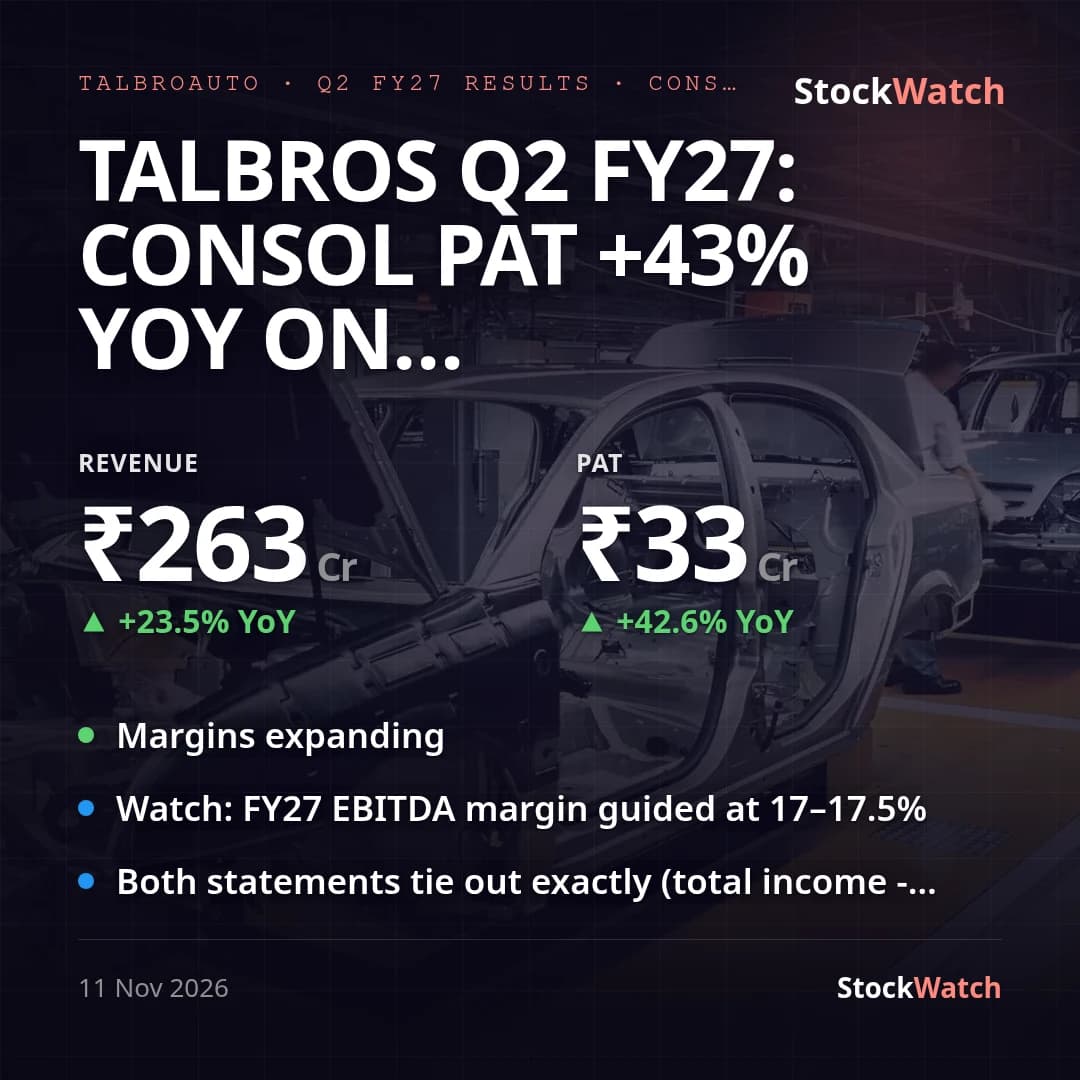
Talbros Q2 FY27: consol PAT +43% YoY on 23.5% revenue growth; margin still trails 17% guidance
Talbros Automotive's consolidated PAT rose 42.6% YoY to ₹32.94 Cr (₹23.10 Cr a year ago) on revenue up 23.5% YoY to ₹263.21 Cr, with no exceptional items on either side of the comparison — the growth is clean, not one-off-driven. Sequentially the print is more modest: revenue +10.4% QoQ and PAT +9.8% QoQ, so the YoY acceleration is the real story, not the quarter-on-quarter move. Standalone PAT of ₹27.78 Cr (+41.6% YoY) tracks the consolidated trend closely (<3% divergence), so the two bases tell the same story this quarter.
Margins expanded YoY but did not move QoQ: operating margin (EBITDA/revenue) was ~16.31%, up from 14.92% a year ago but flat against Q1 FY27's 16.35%, and net margin was 12.32% versus 10.65% YoY and 12.39% in Q1. The YoY expansion sits on operating leverage from the higher volumes rather than a cost line improving in isolation — cost of materials, employee costs and other expenses all grew roughly in line with revenue. Against management's own FY27 guidance of 17–17.5% EBITDA margins (raised alongside the revenue target on the Q1 call), the company is still running below the bottom of that band, both this quarter and on an H1 basis (~16.3%), so the margin leg of guidance is not yet being met even as the topline leg is.
On revenue, the picture is better: H1 FY27 revenue of ₹501.61 Cr is up 19.5% YoY, sitting within the 18–20% FY27 growth guidance the company raised on its last call (from 15–20% previously), and this quarter's 23.5% YoY print is running ahead of that band. Management's division-level guidance (gasket +17% FY27, forging 15–20% growth by year-end) cannot be checked against this filing — the company reports Auto Components & Parts as its only segment, so no gasket/forging split is disclosed here. The ₹6.58 Cr JV contribution (Marelli Talbros Chassis Systems, Talbros Marugo Rubber) to consolidated PAT this quarter, versus ₹8.90 Cr a year ago, is the main source of the ~1-point gap between standalone and consolidated YoY PAT growth. No management press release accompanied this filing, and no reliable Street consensus estimate for this specific quarter was found in a search, so vsStreet is left unknown rather than guessed. The board also approved a 15% interim dividend (₹0.30/share, record date November 20, 2026) alongside the results, and the quarter's governance activity (new independent director appointment, AGM) is routine and not tied to the numbers.