Tata Elxsi: standalone PAT +10% YoY to ₹170 Cr as EBITDA margin recovers a quarter early
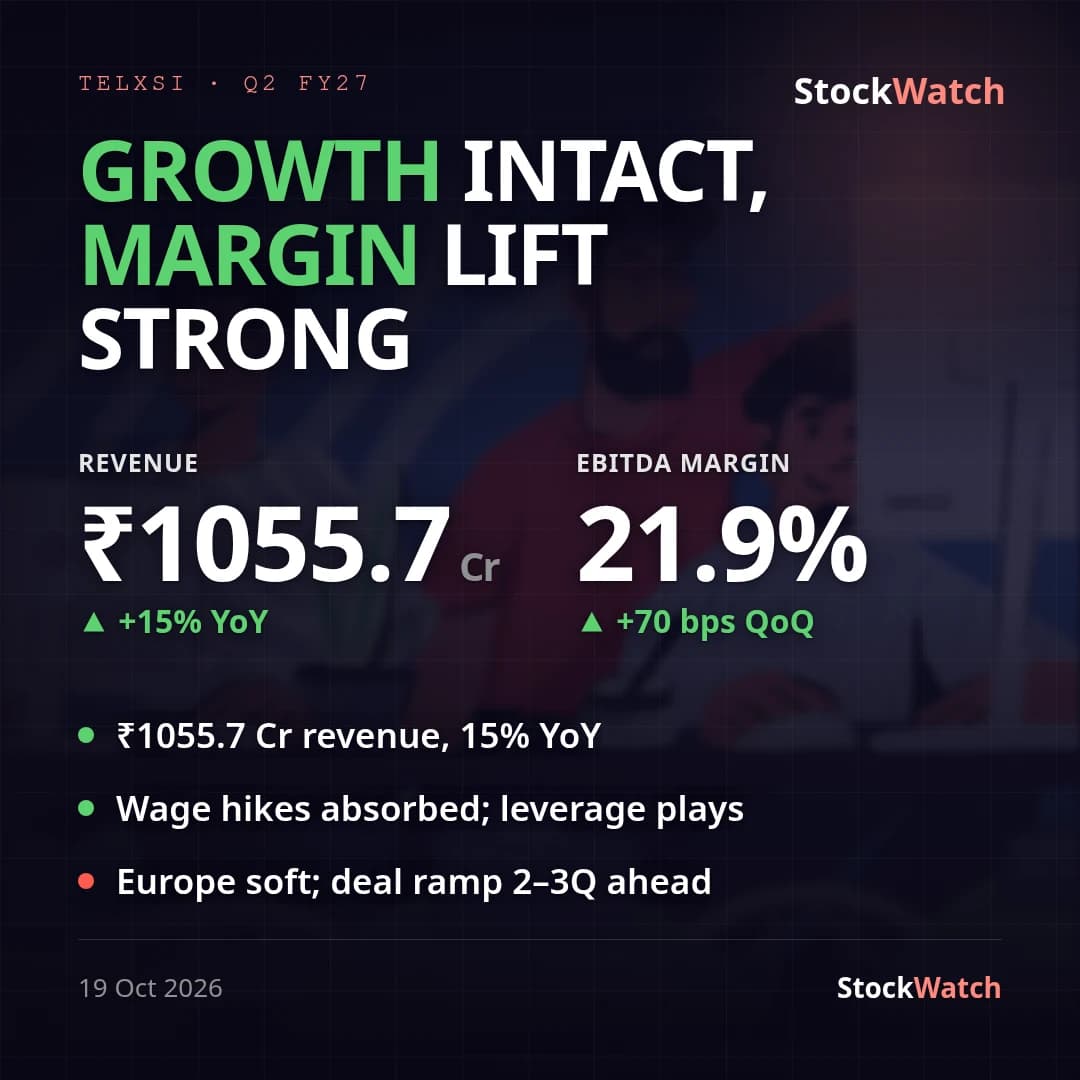
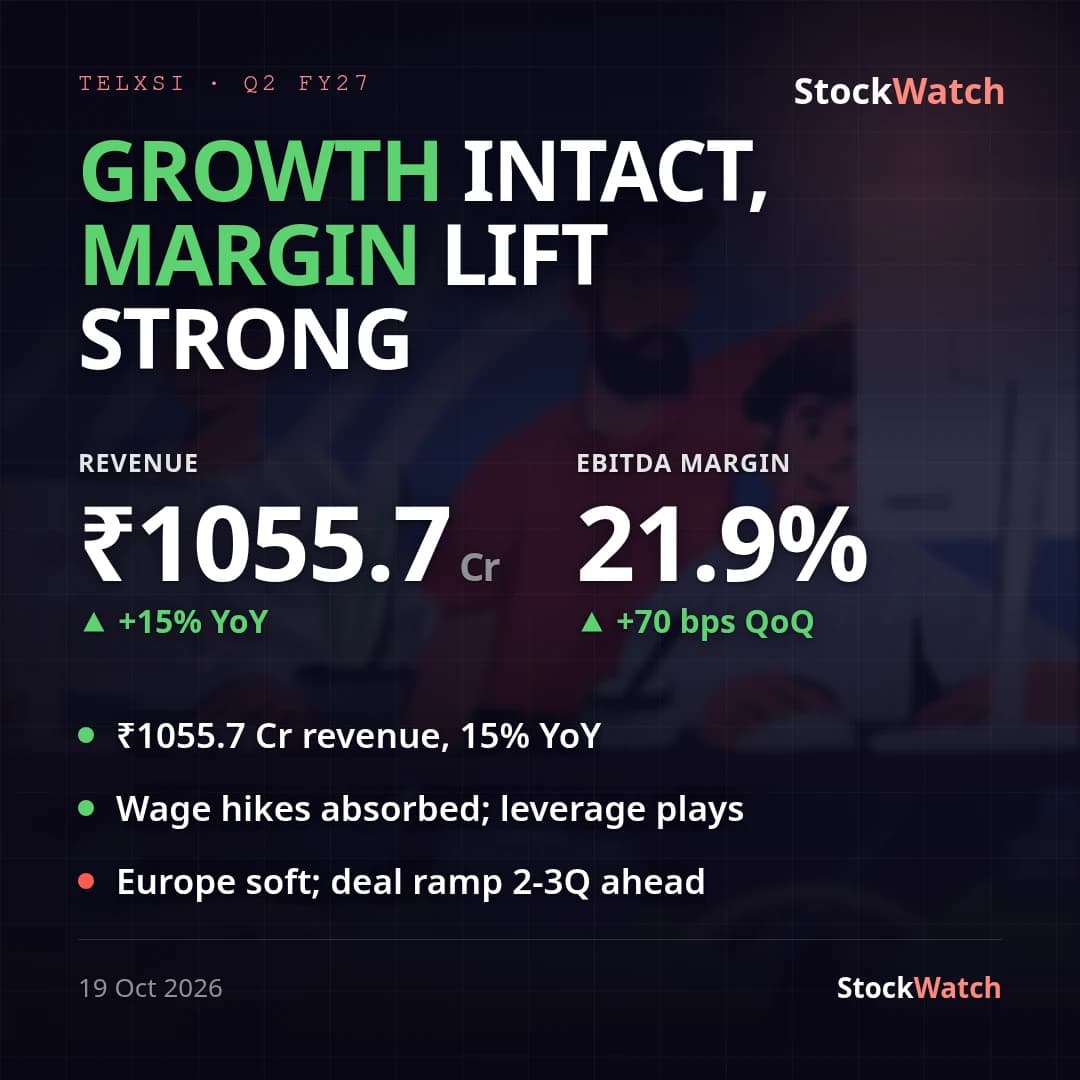
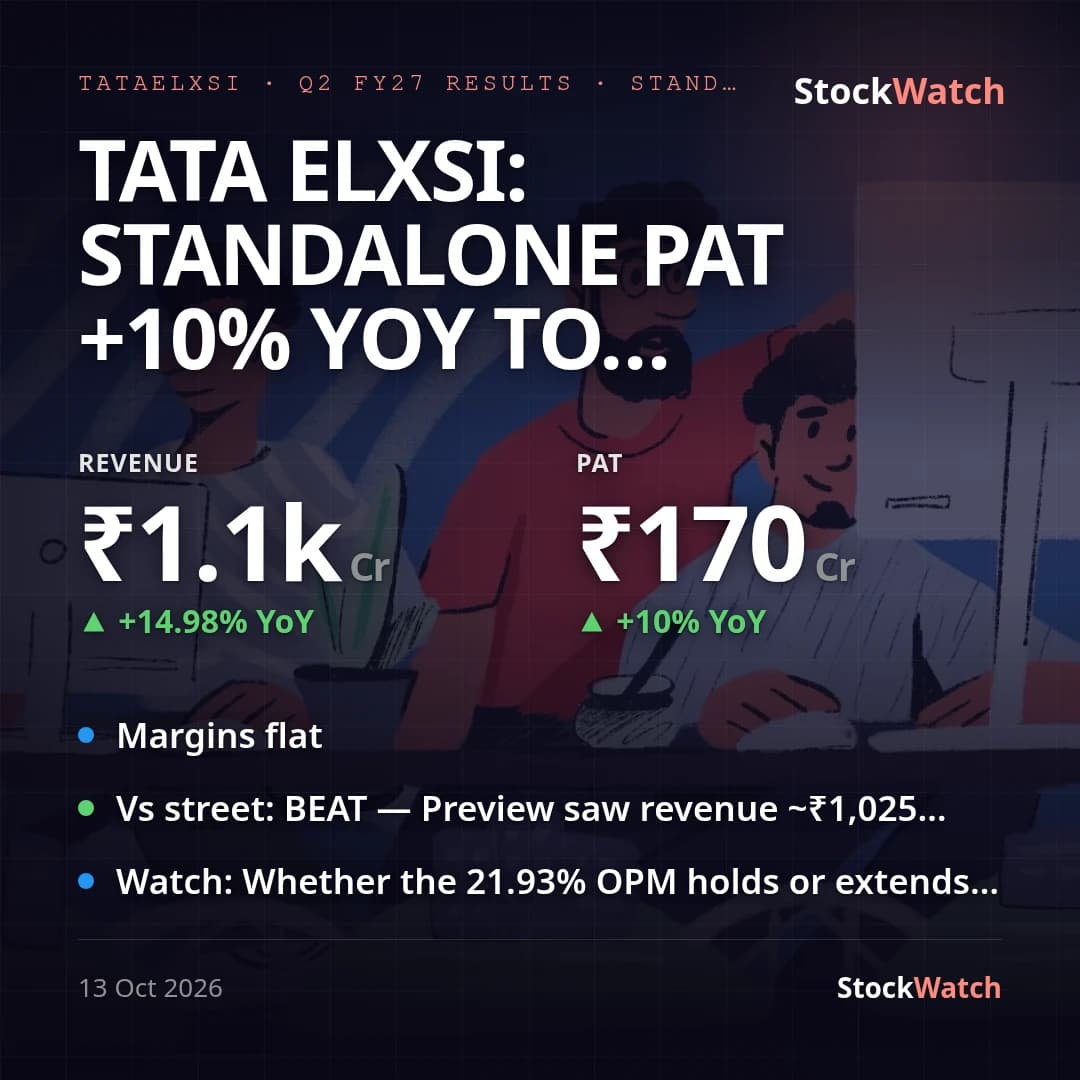
Tata Elxsi's standalone Q2 FY27 (quarter ended September 30, 2026) results — audited, not a limited review — show revenue from operations of ₹1,055.66 Cr, up 14.98% YoY (₹918.10 Cr) and 3.38% QoQ (₹1,021.11 Cr). Net profit rose 10.0% YoY to ₹170.30 Cr (₹154.82 Cr a year ago) but was essentially flat QoQ, down 0.18% from ₹170.60 Cr in Q1 FY27. Basic EPS was ₹27.34 against ₹27.38 in Q1 and ₹24.85 a year ago. The company has no subsidiary, associate or joint venture as of September 30, 2026, so this standalone statement is the complete, primary picture — there is no separate consolidated filing to reconcile against.
The margin picture is split. Core operating margin (EBITDA on revenue — revenue less materials, employee cost and other expenses) expanded to 21.93% from 21.15% in Q1 FY27 and 21.06% a year ago, even as employee benefits expense rose 5.4% QoQ on wage hikes. That is notable against management's own Q1-call guidance, which flagged margin pressure in Q2 from wage hikes with only a "sequential margin ramp-up from Q3 onwards" — the ramp arrived a quarter early. Operating profit (revenue less total expenses) climbed 23.1% YoY to ₹204.19 Cr, outgrowing both revenue and PAT. But net margin (PAT on total income) actually slipped to 15.62% from 16.06% in Q1 and 16.01% a year ago, because other income fell 28.6% YoY and 15.8% QoQ to ₹34.91 Cr, and the effective tax rate rose to 28.77% from 26.61% in Q1 and 27.90% a year ago. In short: the core business margin genuinely recovered ahead of schedule; the bottom-line ratio compression sits on lower non-operating income and a higher tax charge, not on operating execution.
Our pre-result preview flagged this quarter as a "margin recovery credibility test," with Street split between Sell-leaning brokerages (ICICI Securities, Motilal Oswal) and a minority of bulls (HDFC Securities, Prabhudas Lilladher); its on-plan estimates were revenue of ~₹1,025 Cr and PAT of ₹80-100 Cr. Actual revenue of ₹1,055.66 Cr and PAT of ₹170.30 Cr both came in well above those markers — a clear beat — though the PAT estimate range looks stale against trailing actuals (Q1 FY27 PAT alone was already ₹170.60 Cr) and should be read with that caveat. H1 FY27 revenue of ₹2,076.76 Cr is up 14.72% YoY, already running ahead of management's stated "high-single-digit" FY27 growth aspiration from the Q1 call, though that aspiration was made contingent on the healthcare segment, which this filing's two-way segment split (software development & services; system integration & support services) does not break out. Segment-wise, software development & services — 98% of revenue — grew 15.0% YoY to ₹1,027.87 Cr at a 30.5% segment margin; system integration & support was flat at ₹27.79 Cr. No management press release was available in our records to cross-check against the numbers. The quarter also saw a strategic AI investment in KAVIA AI (Sep 10), an eVTOL partnership with Sarla Aviation (Sep 1) and a healthcare-tech tie-up with SCTIMST (Jul 27) — none yet revenue-bearing — and a ₹67.3 lakh income-tax penalty order (Jul 20) that is immaterial to the P&L.
Going into Q3 FY27, the key markers are whether the operating margin gain holds or extends (management had guided a Q3-onward ramp, which this quarter already partly delivered), whether revenue growth sustains its mid-teens YoY pace against the lower high-single-digit full-year aspiration, and whether other income and the effective tax rate normalize so they stop dragging on net margin even as the operating line improves.