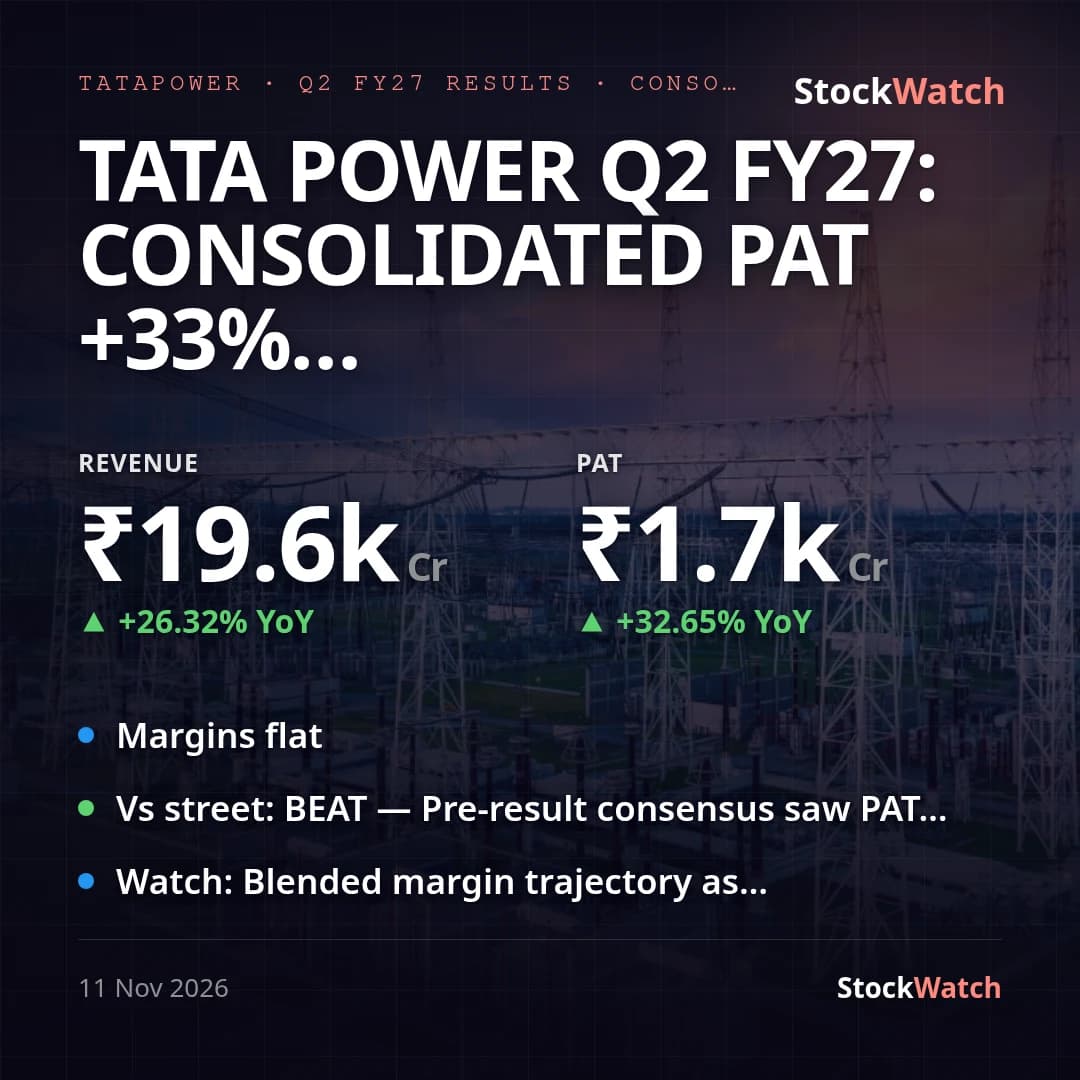
Tata Power Q2 FY27: Consolidated PAT +33% YoY to ₹1,652 Cr, ~22% on adjusted basis
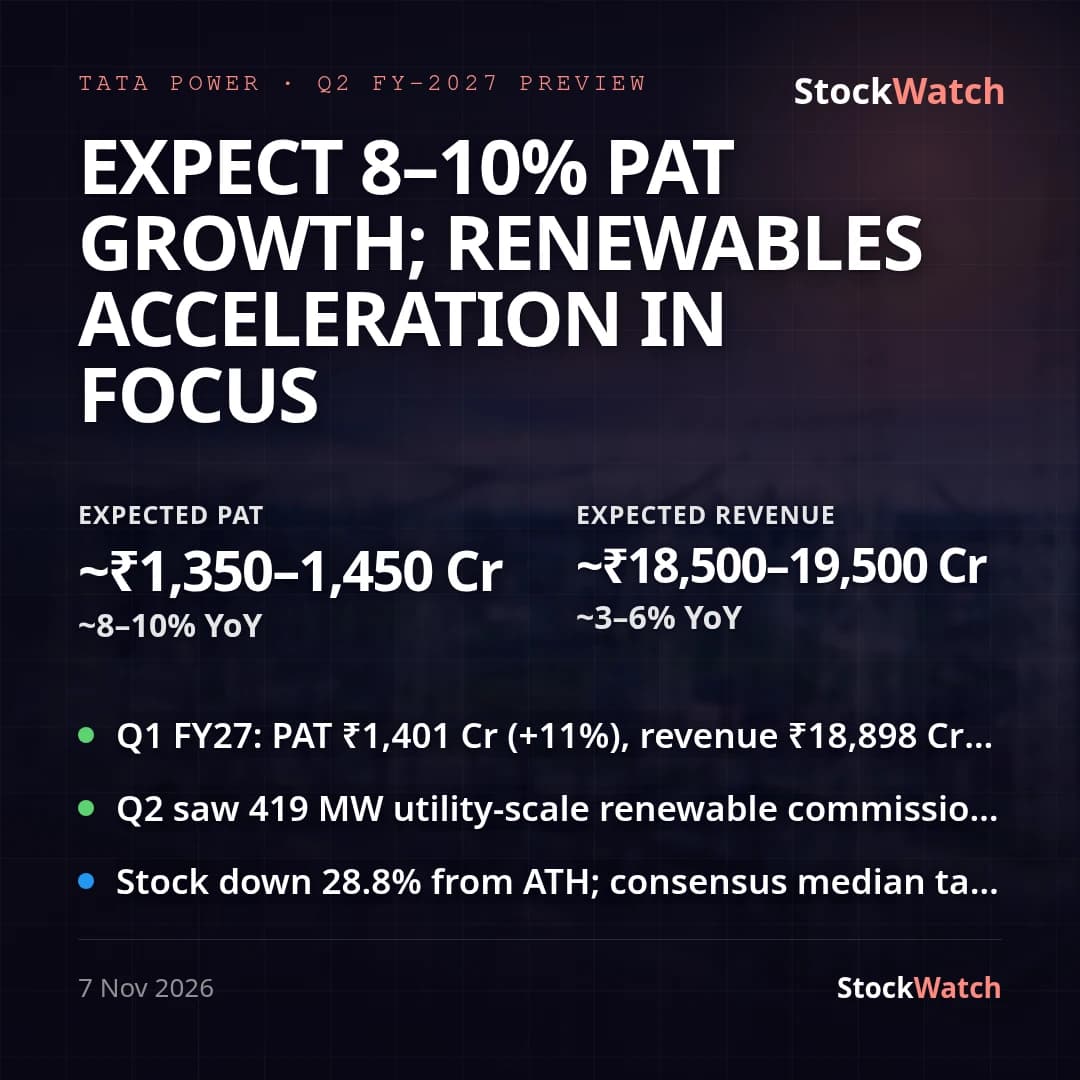
Tata Power's consolidated PAT rose 33% YoY (and 18% QoQ) to ₹1,652 Cr on revenue of ₹19,636 Cr, up 26% YoY and 3% QoQ — comfortably clearing the pre-result Street range of ₹1,350–1,450 Cr PAT and ₹18,500–19,500 Cr revenue flagged in our preview, even stripping out one-offs. Adjusted for a net ₹119.18 Cr exceptional gain (a ₹317.36 Cr gain on losing significant influence over associate Tata Projects Ltd as its stake was diluted from 22.70% to 19.31%, net of ₹102.28 Cr impairment on the Chembur SRA investment property and ₹95.90 Cr impairment on the ABV joint-venture stake held for sale), PAT growth moderates to ~22% YoY (₹1,521 Cr) — still a beat, but the headline +33% overstates underlying earnings power.
The revenue surge is not broad-based: standalone (parent-only) revenue, where the Mundra thermal plant sits, more than doubled YoY (₹2,625 Cr to ₹6,107 Cr, +133%) as the plant resumed full operations under the new SPPA with Gujarat Urja Vikas Nigam from April 2026 (Note 2), after being suspended between July 2025 and March 2026 for overhauling. Consolidated growth is milder (+26%) because subsidiaries in renewables and transmission & distribution grew only modestly, diluting the thermal rebound. Reported NPM rose to 8.3% of total income from 7.2% (QoQ) and 7.8% (YoY), but on an adjusted-PAT basis margin is roughly flat YoY (~7.6%) and the near-quadrupling of JV/associate profit contribution (₹487 Cr vs ₹129 Cr YoY) — not core operations — did much of the lifting, consistent with the margin-resilience question our preview flagged going in.
On management's prior guidance (2.5–3 GW renewable capacity adds for FY27, ₹25,000 Cr capex, Mundra SPPA operational with state approvals expected Aug–Sep): the SPPA is confirmed operational and has since been extended to 31st December 2026 pending remaining procurer sign-offs, so that marker is on track. Renewables added ~419 MW of utility-scale capacity this quarter plus a 300 MW Karnataka solar project commissioned just after quarter-end (Nov 5) — real progress, but the quarterly run-rate still trails the pace implied by the full-year 2.5–3 GW target. No standalone management press release/commentary was available in the context to corroborate or contrast management's own framing of the quarter. Separately, the Singapore arbitration matter (Note 3) escalated materially: SICC dismissed the company's appeal and an enforcement order was served on 6th November attaching Tata Power's shareholding in Singapore subsidiaries up to SGD 830.77 Cr; the company has appealed to the Apex Court (submissions due 23rd November, hearing 19th January 2027) and taken no P&L provision — a contingent, not a reported, risk this quarter.
Going into Q3, the print sets up a test of whether margin can hold as the thermal/renewable mix shifts further and whether the still-elevated JV profit contribution normalises.