Tata Technologies Q2: revenue up 28% YoY, but PAT nearly flat as margins compress
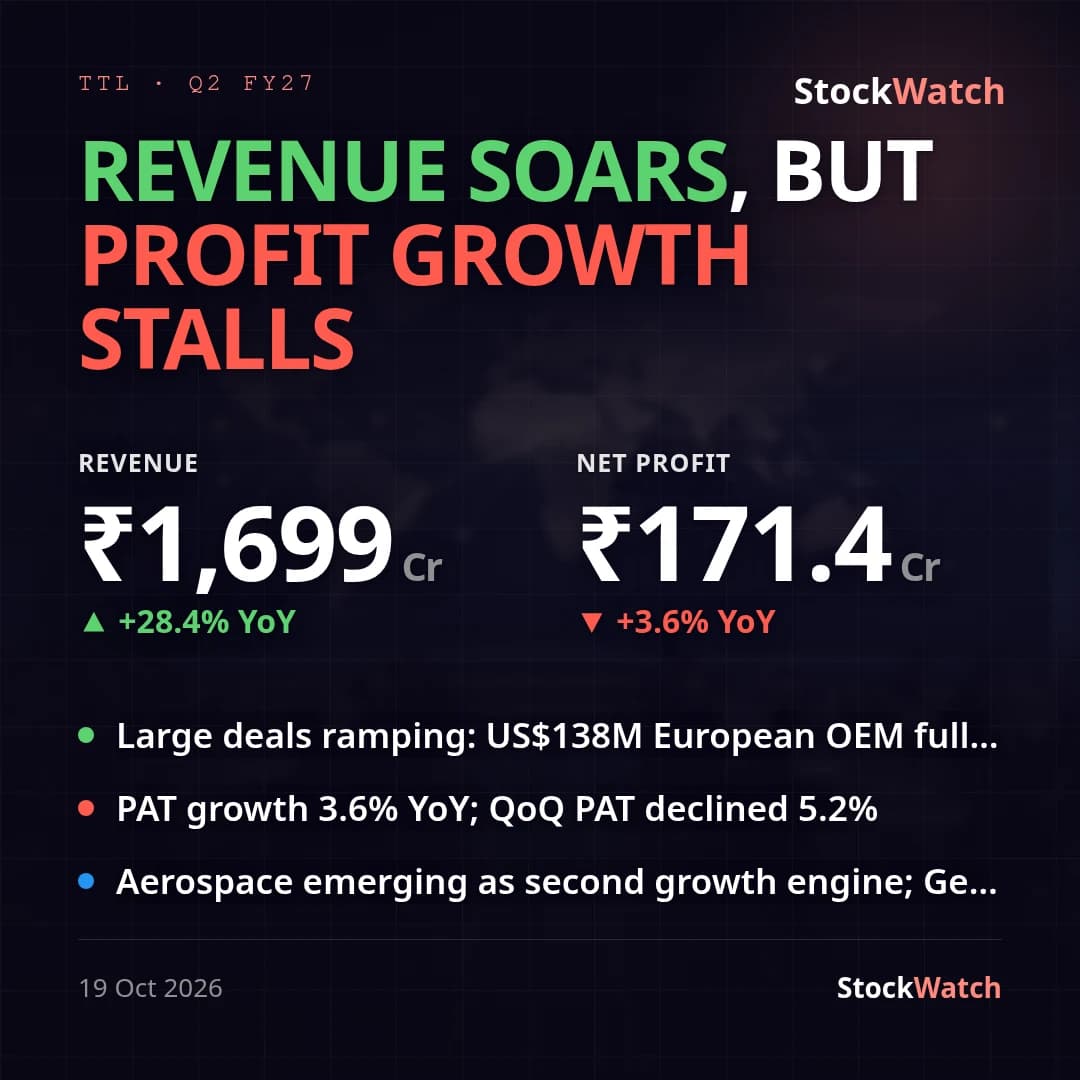
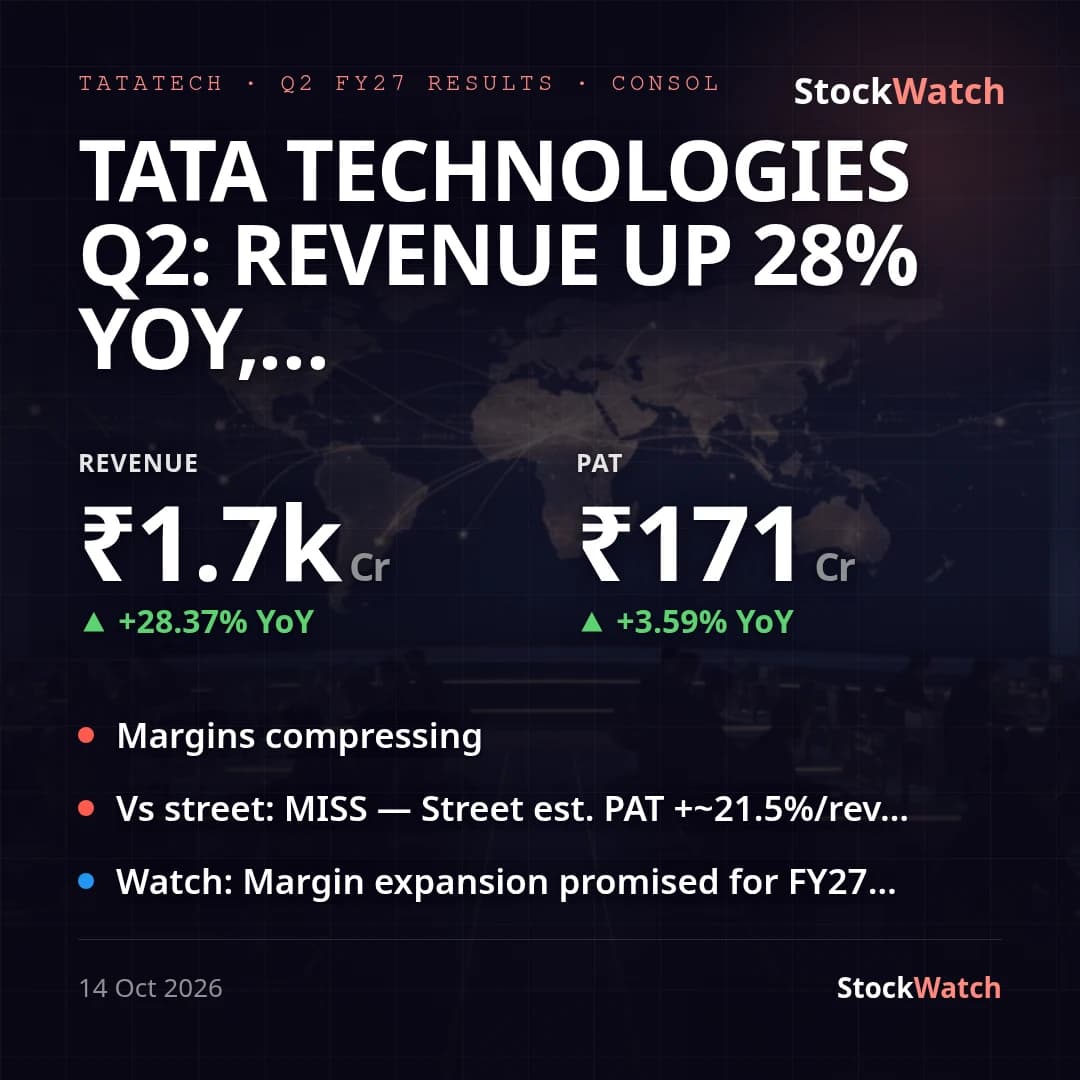
Tata Technologies' consolidated revenue for Q2 FY27 (quarter ended September 30, 2026) rose 28.4% YoY to ₹1,698.80 Cr (+2.1% QoQ), led by the Services segment (+33.9% YoY to ₹1,355.65 Cr), while Technology Solutions grew a slower 10.5% YoY to ₹343.15 Cr and actually slipped 6.7% QoQ. Profit growth did not keep pace: consolidated PAT was ₹171.44 Cr, up just 3.6% YoY and down 5.2% QoQ from ₹180.75 Cr, with basic EPS at ₹4.22 (₹4.08 a year ago, ₹4.45 last quarter). Street consensus (sharpely.in) had modeled roughly 26.5% YoY revenue growth and 21.5% YoY PAT growth for the quarter — the topline came in slightly ahead, but profit badly missed that bar.
The gap sits almost entirely below the segment line. Segment margins were stable — Services held near 30% (30.1% vs 30.0% a year ago) and Technology Solutions firmed to 19.1% from 18.0% — so the compression in net margin to 9.9% of total income (from 12.1% a year ago and 10.6% last quarter) came from items growing faster than revenue: finance costs more than quadrupled YoY to ₹19.85 Cr (from ₹4.57 Cr), depreciation and amortisation nearly doubled to ₹54.27 Cr (from ₹30.89 Cr), and unallocable corporate expenditure rose 39.4% YoY to ₹254.79 Cr (from ₹182.75 Cr) — all consistent with absorbing the Es-Tec GmbH acquisition completed in FY26, whose provisional purchase-price allocation was revised again this quarter (goodwill down ₹18.63 Cr, intangibles down ₹10.35 Cr, earnout down ₹28.98 Cr, per note 5). Other income also fell 35.4% YoY to ₹31.15 Cr. The one offset: profit from the BMW TechWorks India associate more than doubled YoY to ₹11.43 Cr (from ₹5.31 Cr), lifting PBT 7.0% YoY to ₹241.72 Cr even as PAT growth lagged on a higher effective tax rate (29.1% vs 26.7% a year ago).
Management's July 2026 concall guidance called for accelerating double-digit organic revenue growth through FY27 alongside margin expansion from scale, utilisation, AI-led efficiencies and cost discipline. Revenue is tracking ahead of that bar in headline terms, though the 28.4% YoY consolidated growth is flattered by the Es-Tec acquisition and the BMW associate, so underlying organic growth is narrower than the print suggests. The margin side of the guidance has not materialised — net margin moved the wrong way both YoY and QoQ — making this a guidance miss on margins even as revenue guidance is being met. Standalone (parent-only) results diverge from the consolidated picture: standalone PAT rose 9.3% YoY to ₹145.76 Cr on slower 14.5% YoY revenue growth to ₹912.16 Cr, driven by a swing in standalone other income (₹44.35 Cr this quarter versus ₹147.64 Cr last quarter, which included a larger dividend upstream from the Pte Ltd subsidiary) rather than operations. No exceptional items hit either statement this quarter, so the comparisons above are clean and need no further adjustment.
Going into Q3 FY27, the quarter sets up three things to track: whether the promised margin expansion shows up as Es-Tec integration costs normalise, whether the sharp rise in finance costs recedes as acquisition-related debt/leases are serviced, and whether Technology Solutions — down 6.7% QoQ this quarter — stabilises, given Services alone is carrying the growth.