Tracxn Q2 FY27: revenue near-flat, operating margin craters to -28% as staff costs surge
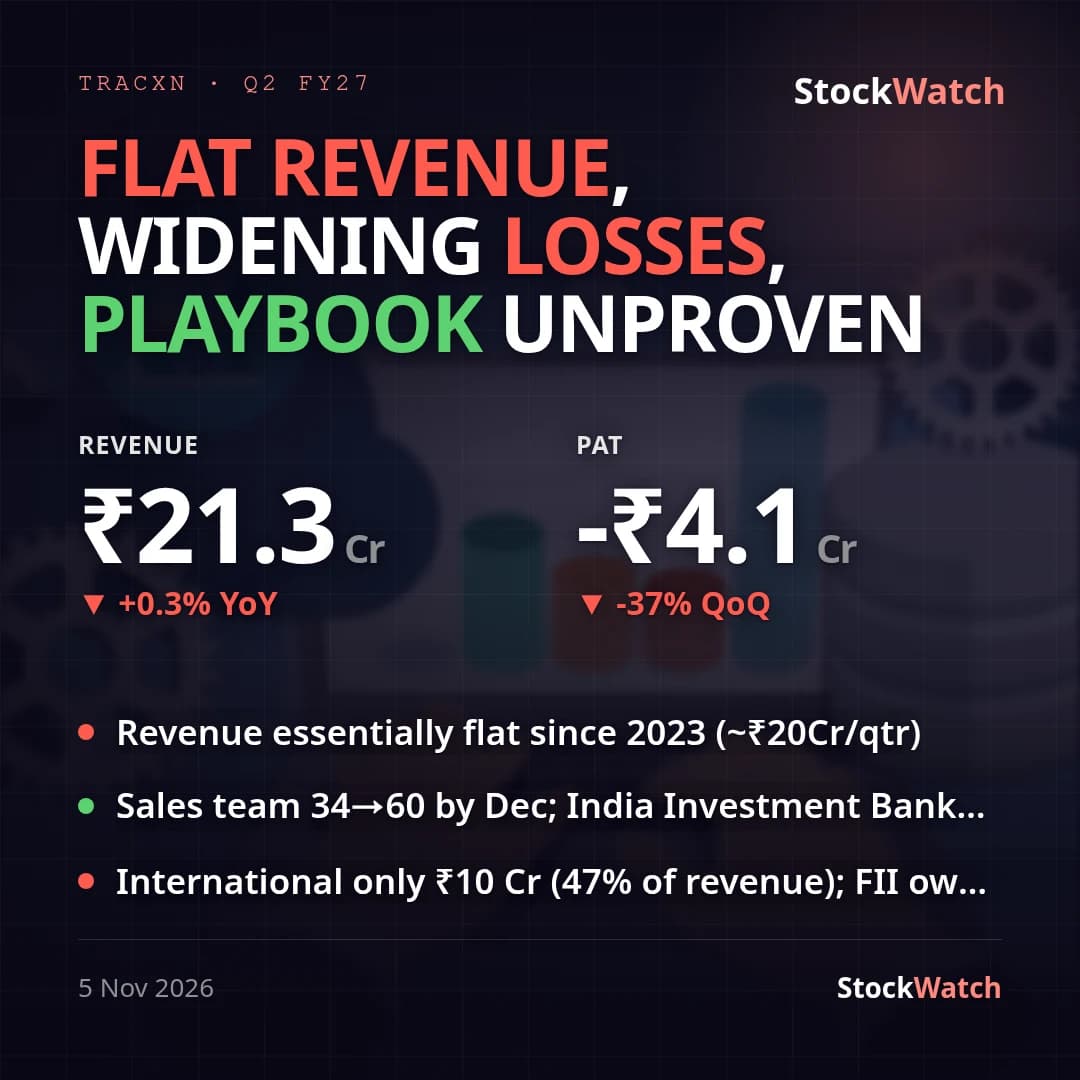
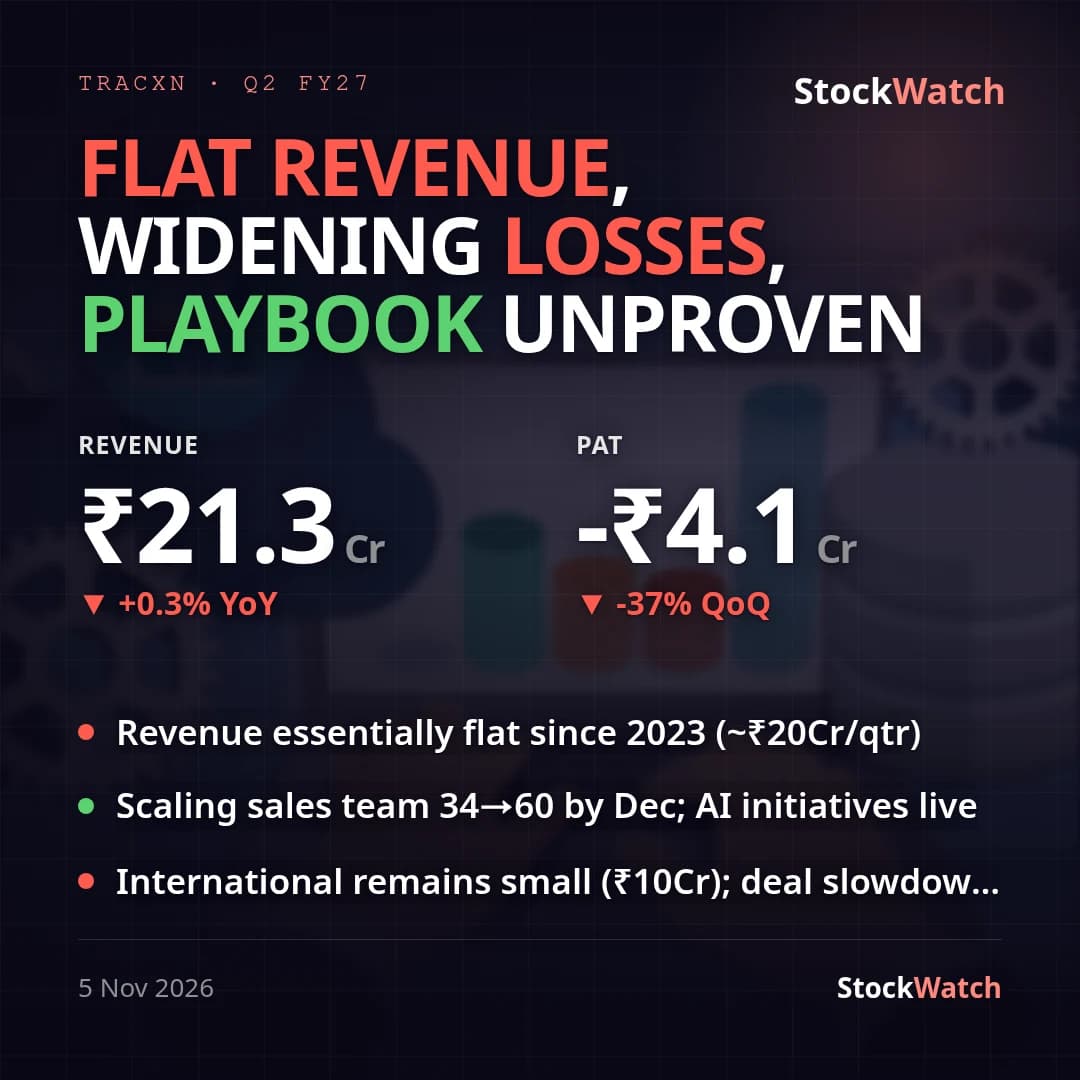
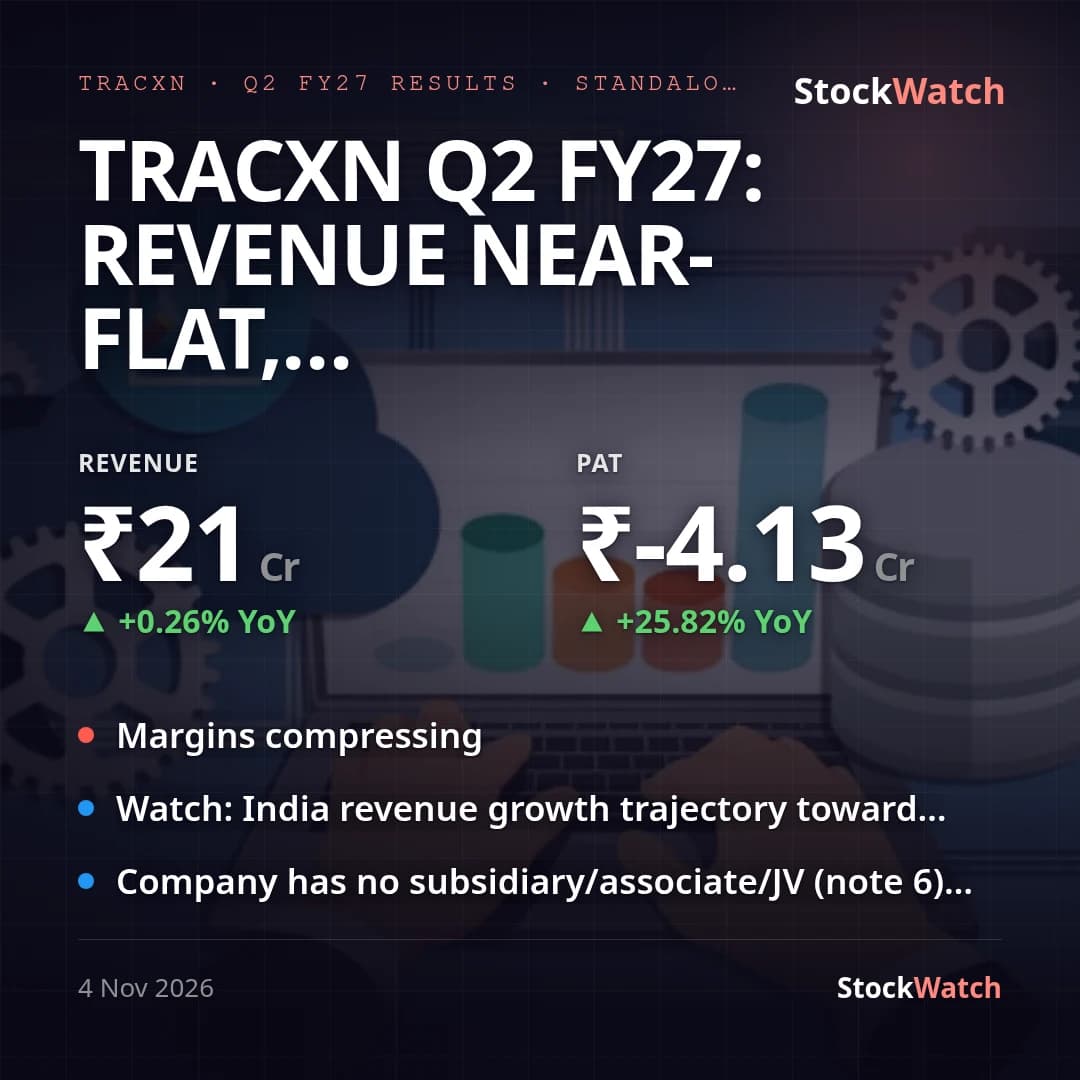
Tracxn's standalone revenue from operations came in at ₹21.30 Cr, up just 0.26% YoY and 1.06% QoQ — effectively flat against management's own FY27 guidance of 15-20% India growth given on the Q1 call. The company swung to an operating loss of ₹5.95 Cr (OPM -27.9%) from an operating margin of -2.7% a year ago and -20.1% last quarter, as employee benefit expense rose 22.5% YoY (₹19.04 Cr → ₹23.33 Cr) and 6.1% QoQ (₹21.98 Cr → ₹23.33 Cr) — well ahead of the ~10% annualized expense growth management had guided to. Net loss for the quarter was ₹4.13 Cr, widening 37% from ₹3.01 Cr in Q1 FY27. On a YoY basis the headline loss looks smaller (₹4.13 Cr vs ₹5.56 Cr, -26% narrower), but that comparison is distorted: Q2 FY26 carried a one-off-looking ₹6.19 Cr tax charge against a near-breakeven ₹0.62 Cr pretax profit, while this quarter booked a small ₹0.52 Cr tax credit. The H1 FY27 loss of ₹7.14 Cr versus ₹4.44 Cr in H1 FY26 (a 61% YoY widening) is the more reliable comparison and confirms profitability deteriorated, not improved.
No formal street estimates could be located for this print — Tracxn is a small-cap (equity base ~₹10.70 Cr paid-up) with thin analyst coverage and no identifiable published Q2 FY27 preview, so vsStreet is marked unknown rather than guessed. Against the company's own prior guidance the quarter missed on both counts that matter: India growth was expected at the higher end of 15-20% for FY27, but standalone revenue barely moved, and expense growth of ~10% annualized was the stated ceiling while employee costs alone grew more than double that pace YoY. No company press release accompanying this filing was available to cross-check management's own framing of the quarter.
The margin squeeze sits almost entirely on the employee benefits line — ESOP expense was a trivial ₹0.58 Cr (versus ₹0.576 Cr in Q1), so the increase is driven by cash employee costs (hiring/wage growth), not stock compensation. Other expenses also rose, up 17.7% QoQ (₹3.33 Cr → ₹3.92 Cr) and 41% YoY. On the developments side, the company closed its trading window ahead of results (Sep 25), granted 135,404 ESOPs (Aug 27), and — most relevant to the revenue story — launched an 'AI Suite for Company Research' on October 15, 2026, part of the AI-product push management said in the Q1 call would start contributing revenue in FY27; that contribution is not yet visible in a topline growing well under 1% YoY.
Going into Q3, the quarter sets up a clear tension: management's FY27 growth and cost-discipline guidance versus two consecutive quarters of flat revenue and expense growth running at more than double the guided rate. The AI Suite is too recent to have shown up in this print.