Travel Food Services Q1 FY27: PAT +35.6% YoY to ₹128.8 Cr, Core Margin Compresses
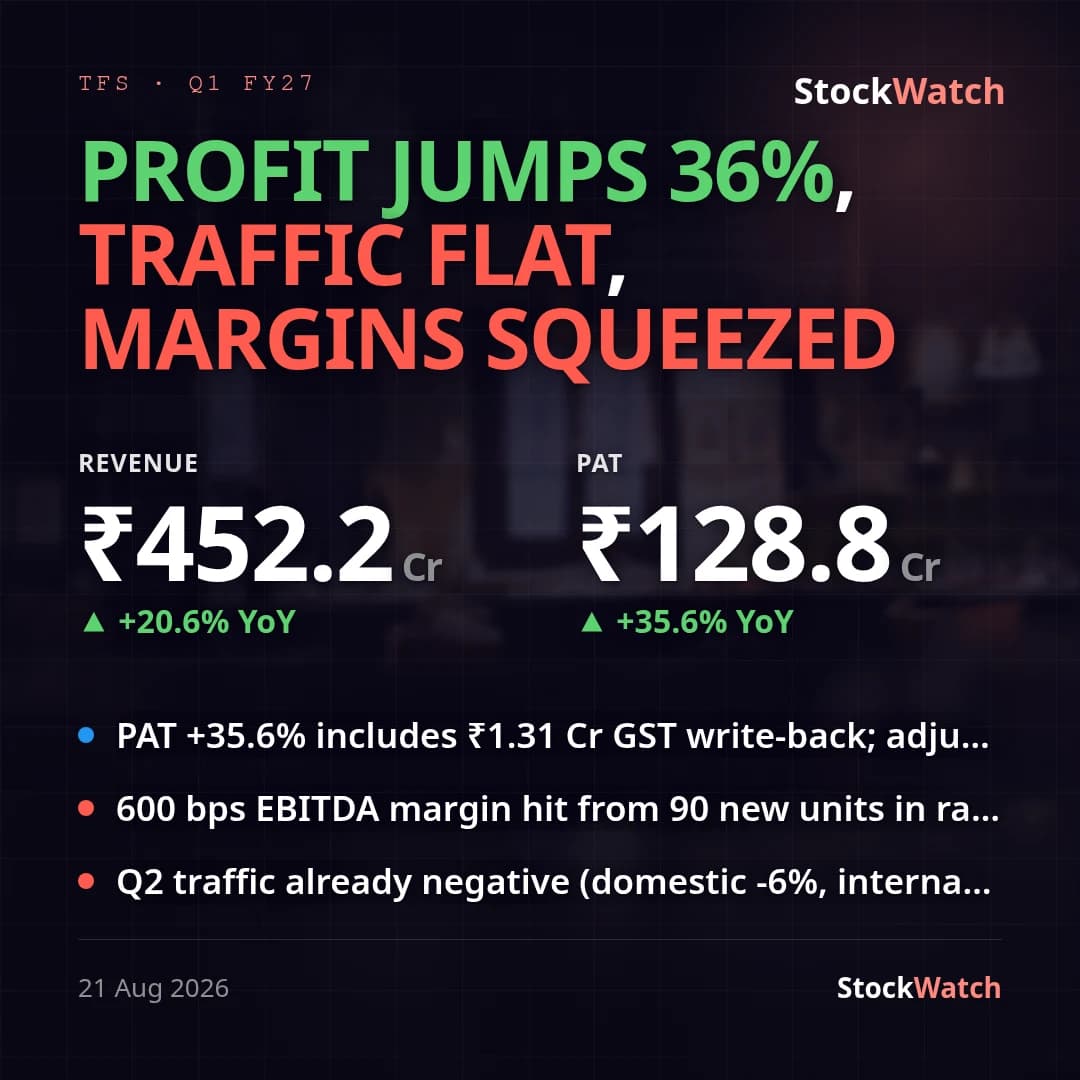
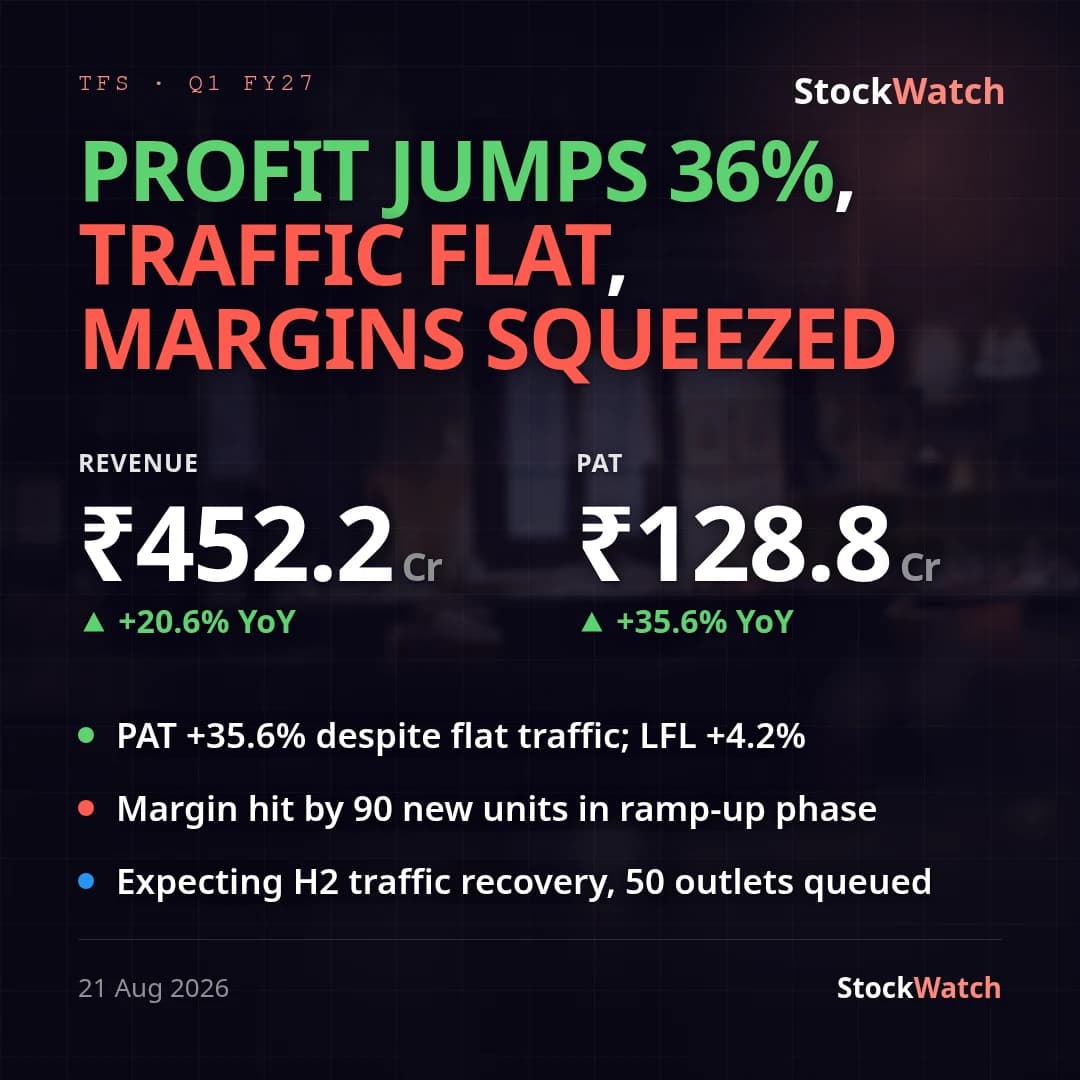
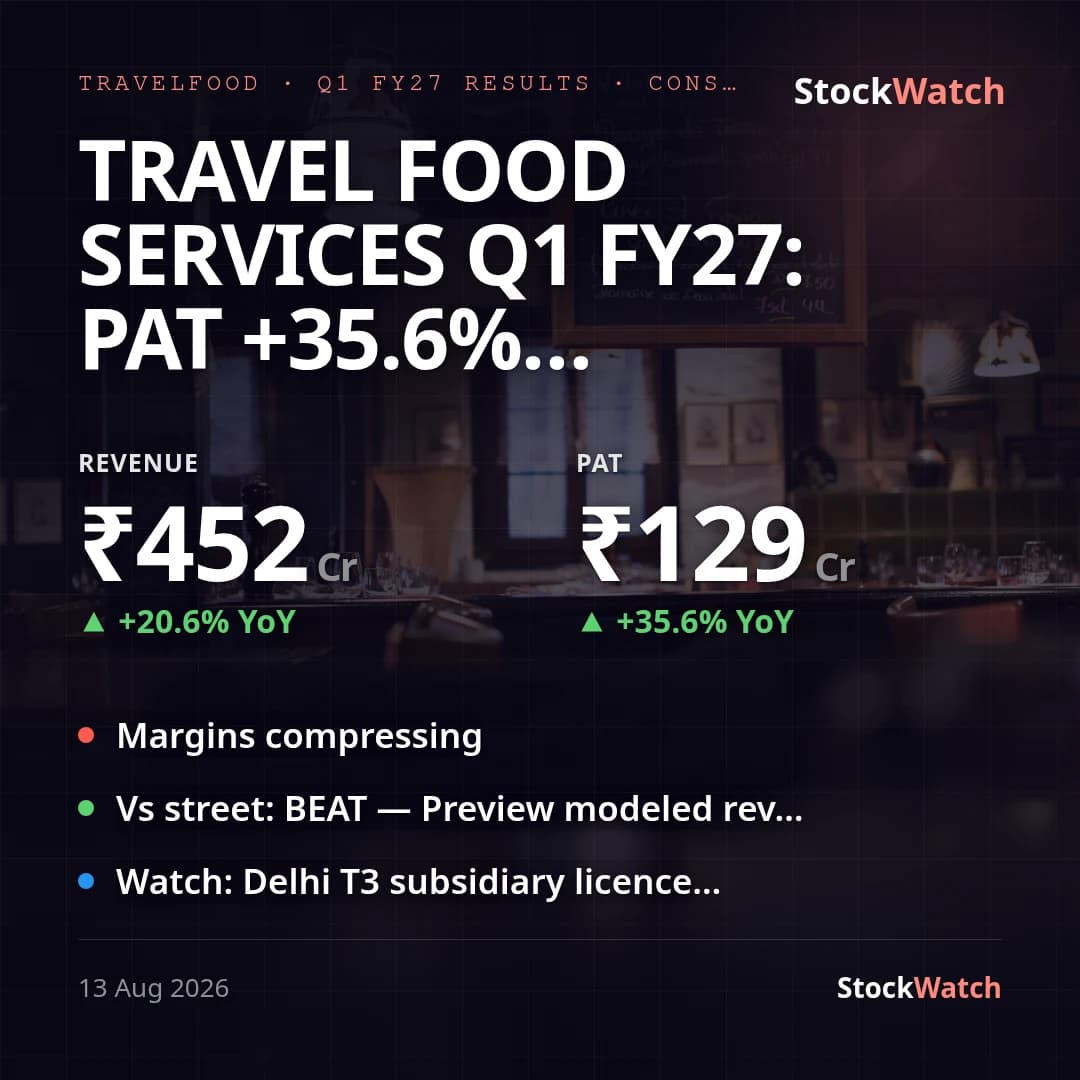
Travel Food Services posted consolidated revenue of ₹452.2 Cr (+20.6% YoY, -1.8% QoQ) and consolidated PAT of ₹128.8 Cr (+35.6% YoY, +5.0% QoQ) for Q1 FY27, with basic EPS at ₹9.62 versus ₹6.97 a year ago. Both lines beat the bands our pre-result preview had modeled going in — reported revenue growth ~12-18% YoY and PAT growth ~15-20% YoY — and the revenue pace also sits at the upper end of management's guided 18-20% FY27 like-for-like growth range, ahead of the 5% passenger-traffic growth it had flagged on the last call.
The headline profit growth, however, is not purely operating-driven. EBITDA-basis operating margin (revenue less material, employee and other operating costs, excluding other income) compressed to 35.8% from 38.9% a year ago and 40.4% last quarter, as other expenses jumped 45.2% YoY (₹99.0 Cr to ₹143.8 Cr) and employee costs rose 21.2%, both growing faster than the 20.6% topline. Net margin nonetheless expanded to 25.8% from 24.0% YoY: other income more than doubled to ₹46.2 Cr from ₹20.7 Cr, and the Group's share of associates'/JVs' profit rose 44.1% to ₹11.6 Cr from ₹8.0 Cr, together offsetting the operating-cost pressure. Finance costs eased slightly YoY (₹7.9 Cr vs ₹8.7 Cr) after an unusual one-quarter spike to ₹37.4 Cr in Q4 FY26 that is not repeated here.
Management's own release calls Q1 "a strong quarter... despite a challenging operating environment impacted by disruptions arising from the Middle East conflict," and points to the Noida International Airport go-live — multiple Travel QSR outlets plus the airport's first lounge — as the quarter's network highlight; that explains the revenue beat but not the cost inflation. The quarter also carried a new 5-year airport F&B outlet licence win (June 18) and an auditor change at a subsidiary (August 12), alongside an extended trading-window closure to August 15 tied to the results process — none of which are financially material on their own. Standalone (parent-only) figures were smaller but directionally similar — revenue ₹347.4 Cr, PAT ₹111.1 Cr, EPS ₹8.44 — with consolidated the primary read given the scale of JV/subsidiary contribution, including a new Indonesia subsidiary added in September 2025. Management gave no specific numeric guidance for this quarter in the filing itself; capex spend also isn't separately disclosed here, so the ₹50-60 Cr annual capex guidance from the last call can't be checked against this print.
The Delhi Terminal 3 subsidiary's licence — flagged by the auditors as a material uncertainty at the subsidiary level — is scheduled to expire September 30, 2026, and is the nearest-term item to watch given the entity is 60%-owned and consolidated. The other open question heading into Q2 FY27 is whether this quarter's other-expenses inflation was a one-off tied to new-outlet ramp-up (Noida, in particular) or a more structural drag on the 38-40% operating margin the company ran through FY26.