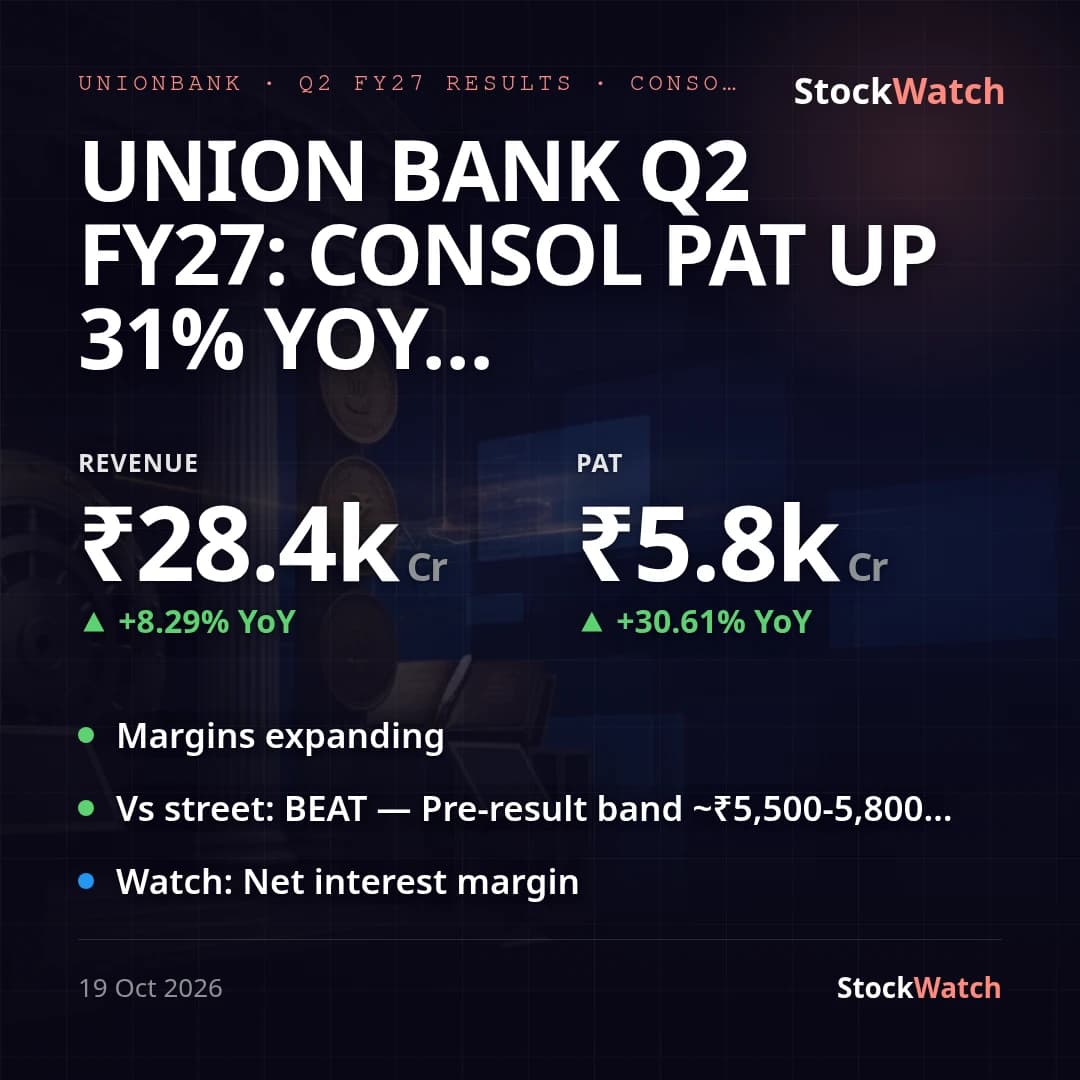
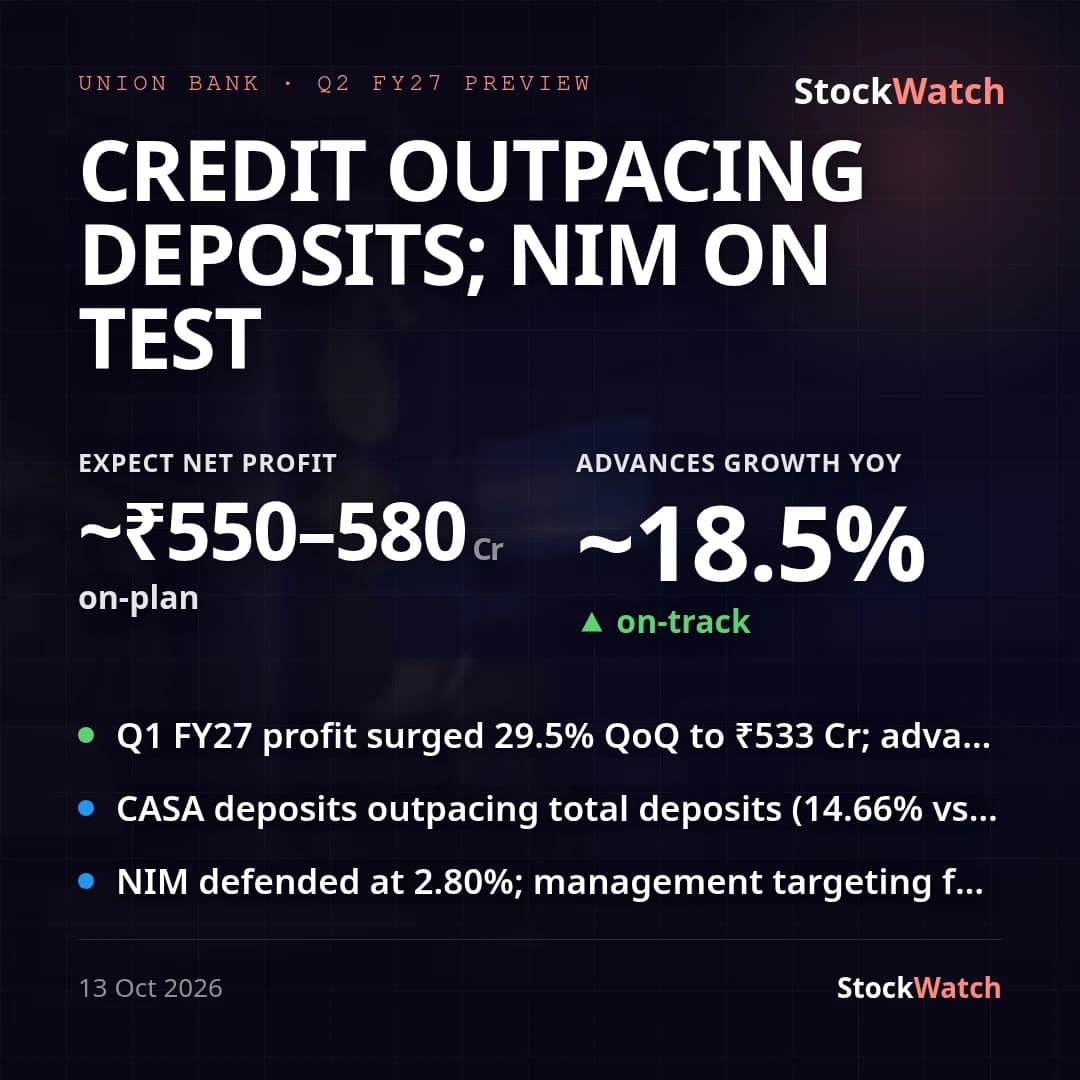
Union Bank of India's consolidated net profit rose 30.6% YoY to ₹5,781 Cr for Q2 FY27 (quarter ended September 30, 2026), with standalone PAT up 30.3% YoY to ₹5,537 Cr — both against ₹4,426 Cr / ₹4,249 Cr a year ago. Consolidated revenue (interest earned) grew a comparatively modest 8.3% YoY to ₹28,378 Cr, so profit growth significantly outran the topline. The gap was bridged chiefly by a sharp pullback in provisioning: non-tax provisions & contingencies fell 49.6% YoY to ₹702 Cr (consolidated) as asset quality improved markedly — gross NPA fell to 2.42% from 3.29% a year ago and 2.65% in Q1, net NPA to 0.42% from 0.55% YoY. Sequentially, momentum cooled sharply from Q1's pace: consolidated PAT rose just 2.5% QoQ (standalone +3.8%) on 3.5% QoQ revenue growth, exactly the kind of deceleration our pre-result preview flagged as the "credit momentum stress test" after Q1's much stronger run.
Net profit margin expanded to 17.27% from 13.94% a year ago, though it was flat versus Q1 (also 17.27%); operating margin improved to 24.35% from 21.55% YoY but eased slightly from Q1's 24.62% — the small QoQ OPM dip suggests some opex/NII pressure crept in even as the lighter provisioning load kept the bottom line steady. No exceptional items appear in either the current or comparative periods, so the full YoY jump is attributable to core operating performance plus the provisioning tailwind, not one-offs. Consolidated basic EPS rose to ₹7.57 from ₹5.80 YoY (₹7.39 in Q1), tracking the PAT trend almost exactly since the share count is unchanged.
Standalone PAT of ₹5,537 Cr lands within the ~₹5,500-5,800 Cr band our pre-result preview had set out (17-analyst coverage, consensus target ₹197 vs. a pre-result CMP of ₹172), effectively meeting the Street's bar; the bigger beat is on asset quality, with gross NPA at 2.42% comfortably better than the preview's flagged 3.2-3.4% watch range. Net interest margin — which the preview pegged at an expected 2.80-2.90% — is not disclosed in this regulatory filing and remains unverified pending the investor presentation/concall; Q1's reported NIM was 2.80%. Management's prior (Q1) guidance centred on sustaining CASA growth, improving NIM, and keeping credit growth in line with or above industry; this quarter's profitability and asset-quality trajectory is directionally consistent with that framing, though the statement itself doesn't disclose the specific NIM, CASA or advances-growth figures needed to fully verify it, and no management press release was available for this result to cross-check tone. Among this quarter's disclosed corporate developments, the bank also reported ₹16,083 Cr of debt securities outstanding as of September 2026 and was fined ₹1,33,850 by the RBI for currency-chest deficiencies (September 11) — both minor/procedural and not drivers of the P&L above.
With GNPA/NNPA trending down and provisioning easing, the bank heads into Q3 FY27 — for which it has already flagged "strong growth" in provisional figures per its October 1 update — needing to show NIM holds near 2.80% amid the funding-cost pressure the Street has flagged as the key swing factor in the stock's bull/bear debate.