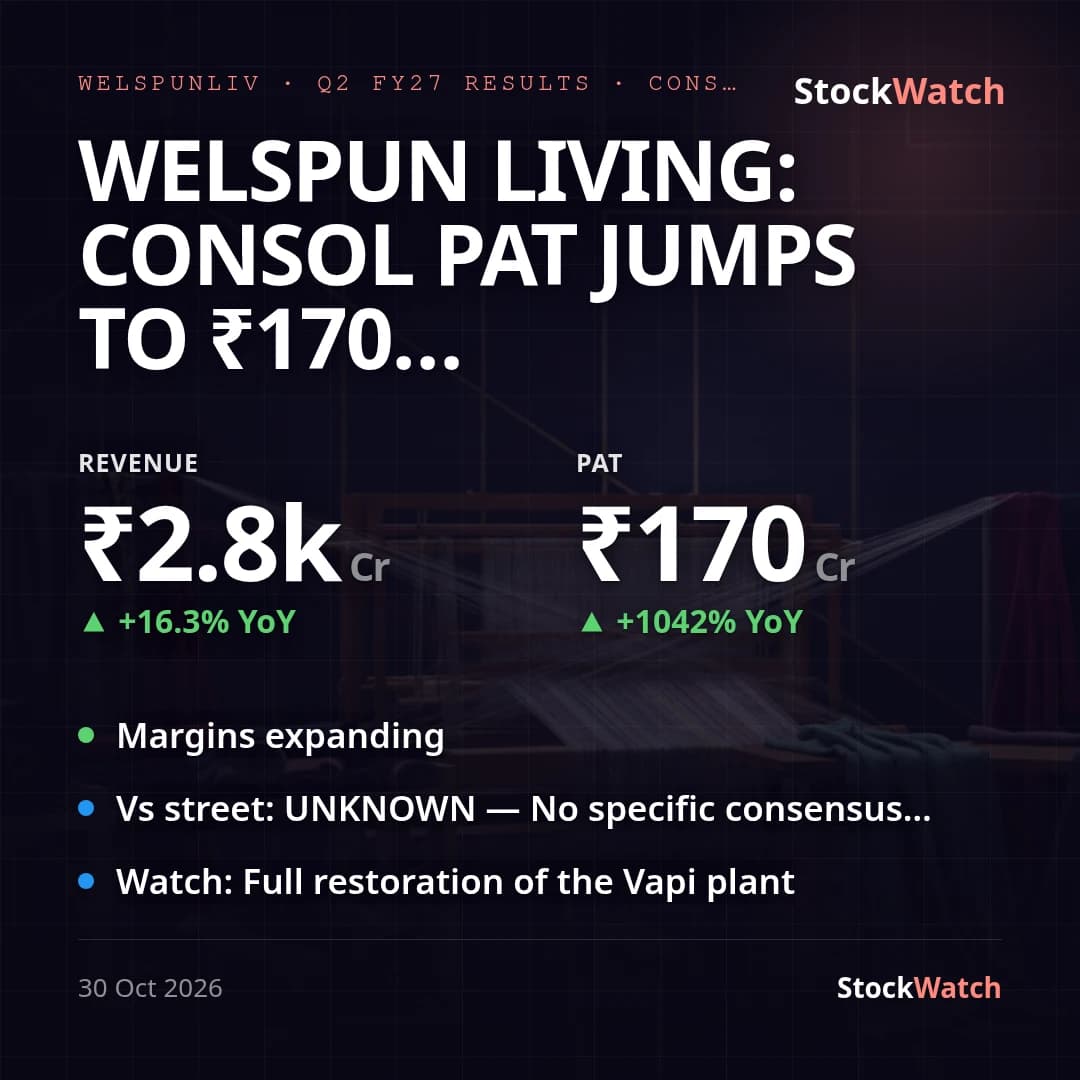
Welspun Living: consol PAT jumps to ₹170 Cr on 16.3% revenue growth, margin hits 12.9%
Welspun Living's consolidated PAT surged to ₹169.7 Cr for Q2 FY27 (owners' share ₹169.1 Cr, up ~13x YoY on the company's own owners-only framing) from a depressed ₹14.9 Cr a year ago, as revenue grew 16.3% YoY to ₹2,838 Cr and EBITDA margin expanded 600 bps YoY to 12.9% (₹370 Cr EBITDA). Sequentially the move was modest — revenue up 1.5% QoQ and PAT up 4.3% QoQ — a normal slowdown after a strong Q1 FY27 print rather than a trend change. No specific Street consensus figure for this print could be sourced; ahead of the quarter, Motilal Oswal and Jefferies had both flagged that the Vapi plant closure would "hurt" Q2, yet the company still delivered double-digit growth and margin expansion, so the outcome ran ahead of that cautious framing even without a hard number to beat.
A ₹7.16 Cr exceptional charge tied to flood damage at the Vapi plant sits inside PBT, but an equal offsetting deferred-tax credit (linked to the insurance recoverable) left the net PAT impact close to nil, so the YoY PAT growth is effectively already "adjusted." The expansion was broad-based operationally: Home Textiles segment profit (before interest/tax) rose to ₹323 Cr from ₹152 Cr a year ago, and Flooring's EBITDA margin improved to 10.8%. Standalone PAT, by contrast, fell 26% YoY to ₹108.7 Cr — not an operating miss, but because the year-ago standalone quarter carried roughly ₹154 Cr of one-off intercompany dividend income (consolidated away at the Group level) that also came with a Section 80M tax credit, inflating that period's base; readers checking standalone filings will see a decline where the consolidated, economically relevant number shows strong growth.
Against management's Q1 FY27 guidance of double-digit FY27 revenue growth, low-teens EBITDA margins, ₹400-500 Cr capex and ROCE improving to low teens, this quarter tracks on or near target: revenue growth of 16%+ is comfortably double-digit, the 12.9% margin sits within the low-teens band, and ROCE improved to 12.7%. The balance sheet also strengthened: the company moved to a net-cash position versus ₹775 Cr net debt in March 2026, with the cash conversion cycle shortening to 44 days from 82 days. At the segment level, the US pillow business grew 2.4x YoY, with management reiterating it remains "on track to double revenues in FY27," while the domestic Welspun-branded business grew 37%. Management's press release framed the quarter as reflecting "continued progress in driving profitable growth and strengthening our financial position" — a characterization the margin and balance-sheet data support, though the headline PAT multiple is flattered by an unusually weak year-ago base. The RoSCTL/tariff-refund uncertainty flagged on the last call (no guarantee beyond Q2 FY27) was not directly addressed in this release.