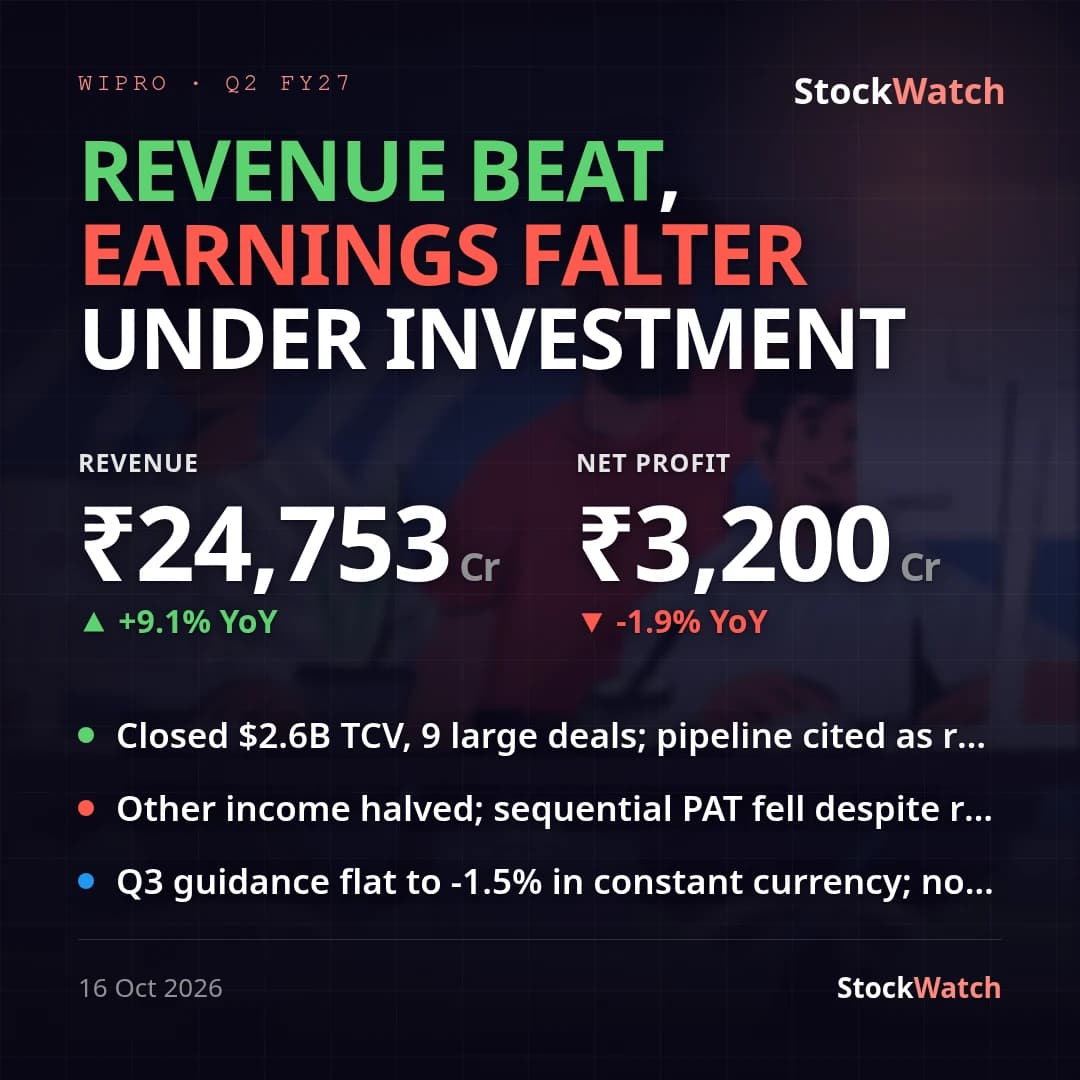
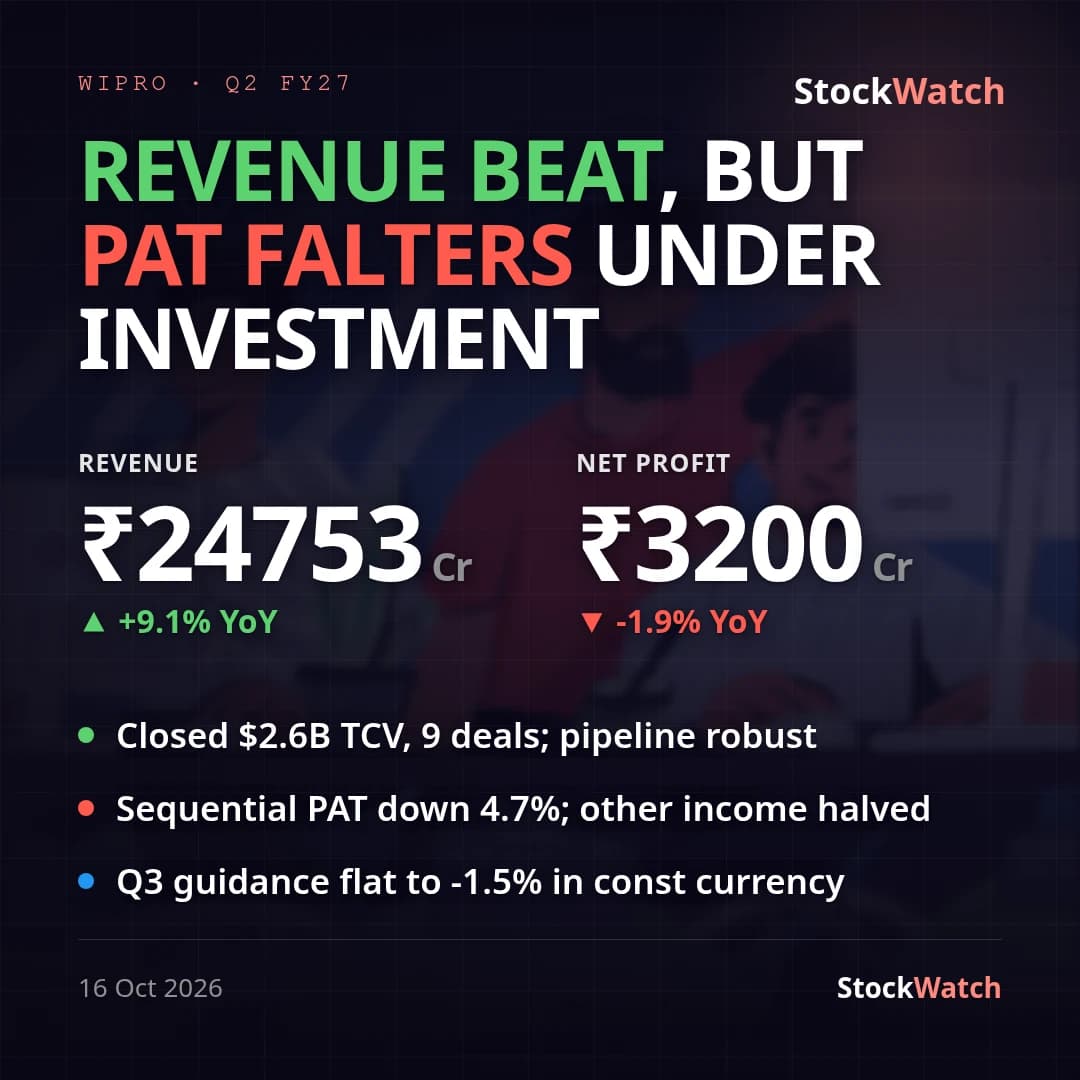
Wipro Q2 FY27: Consol. PAT falls 1.9% YoY to ₹3,201 Cr, margins compress, misses Street
Wipro's consolidated PAT (profit attributable to equity holders) for Q2 FY27 (quarter ended September 30, 2026) was ₹3,200.6 Cr, down 1.9% year-on-year from ₹3,262.4 Cr and down 4.6% sequentially from ₹3,356.3 Cr, missing Street consensus of roughly ₹3,264 Cr (Business Standard poll of analysts) and further short of Prabhudas Lilladher's ₹3,340 Cr estimate. Consolidated revenue of ₹24,752.7 Cr grew a healthier 9.1% YoY and 1.1% QoQ, so the YoY story is revenue growth outrunning profit — net profit margin fell to 12.93% from 13.80% a year ago and from 13.18% last quarter, confirming the margin contraction the Street had braced for pre-result.
Consolidated PBT of ₹4,204.7 Cr was down 1.8% YoY and 3.0% QoQ despite the topline growth. Two cost lines outpaced revenue: depreciation and amortisation jumped 26.7% YoY to ₹876.7 Cr, driven by intangible-asset amortisation nearly doubling to ₹284.0 Cr from ₹167.0 Cr a year ago as acquisition-related intangibles were recognised; and finance costs rose 51% YoY to ₹545.4 Cr alongside higher short-term borrowings (₹18,502.1 Cr at quarter-end versus ₹16,591.2 Cr in March). Employee costs, the largest expense line at ₹14,837.0 Cr, grew roughly in step with revenue (+9.0% YoY), so they were not the margin driver. The effective tax rate also crept up QoQ, from 22.6% to 23.9%, adding to the sequential PAT decline. On a segment basis, the IT Services unit's operating result of ₹4,072.6 Cr on segment revenue of ₹24,667.0 Cr implies an operating margin of ~16.5% — up from ~16.0% last quarter but below the year-ago 16.7% and still short of management's targeted 17%-17.5% band.
Growth wasn't evenly organic: Europe revenue grew 13.5% YoY and APMEA 23.6% YoY, both far ahead of the 9.1% overall rate, helped by the 100% acquisition of Mindsprint Pte Ltd (completed May 15, 2026) and incremental 20% stakes picked up in Aggne Global Inc. and Aggne Global IT Services Private Limited (effective June 2026) — moves that lifted consolidated goodwill to ₹40,393.8 Cr from ₹38,221.4 Cr in March. Sequentially, Americas 1 — the largest SMU — was the lone segment to shrink (-1.3% QoQ), while Americas 2, Europe and APMEA all grew 1.7%-4.0% QoQ. The Board also completed a ₹15,050.8 Cr buyback of 60 crore shares at ₹250 apiece during the quarter (settled June 24, 2026), trimming paid-up equity capital and likely supporting basic EPS, which rose to ₹3.23 from ₹3.10 YoY and ₹3.20 QoQ even as absolute PAT fell. No separate management press release or commentary was available in this filing to cross-check against management's own framing of the quarter.
Against the prior concall's guidance — sequential revenue growth of -1.5% to +0.5% in constant currency and a push back toward the 17%-17.5% margin band — the quarter is a mixed read: reported (INR) QoQ revenue growth of 1.1% is broadly consistent with the guided range (the constant-currency figure itself isn't disclosed in this filing), but the IT Services operating margin, at ~16.5%, remains outside the targeted band, so the margin-recovery goal management set out is not yet met. Post quarter-end, Wipro completed the Alpha Net Consulting acquisition (October 1, 2026) and a merger of step-down subsidiaries (October 3, 2026), and clarified that the US PERM visa suspension would have no material business impact (October 13, 2026) — developments that will shape, but are not yet reflected in, this quarter's numbers. The next checkpoints are whether IT Services margin closes the gap to the 17%-17.5% band and whether revenue growth becomes less dependent on recently acquired entities.