YES Bank Q2: consol PAT +63% YoY to ₹1,084 Cr; AT1 ruling leaves ₹5,213 Cr unbooked hit
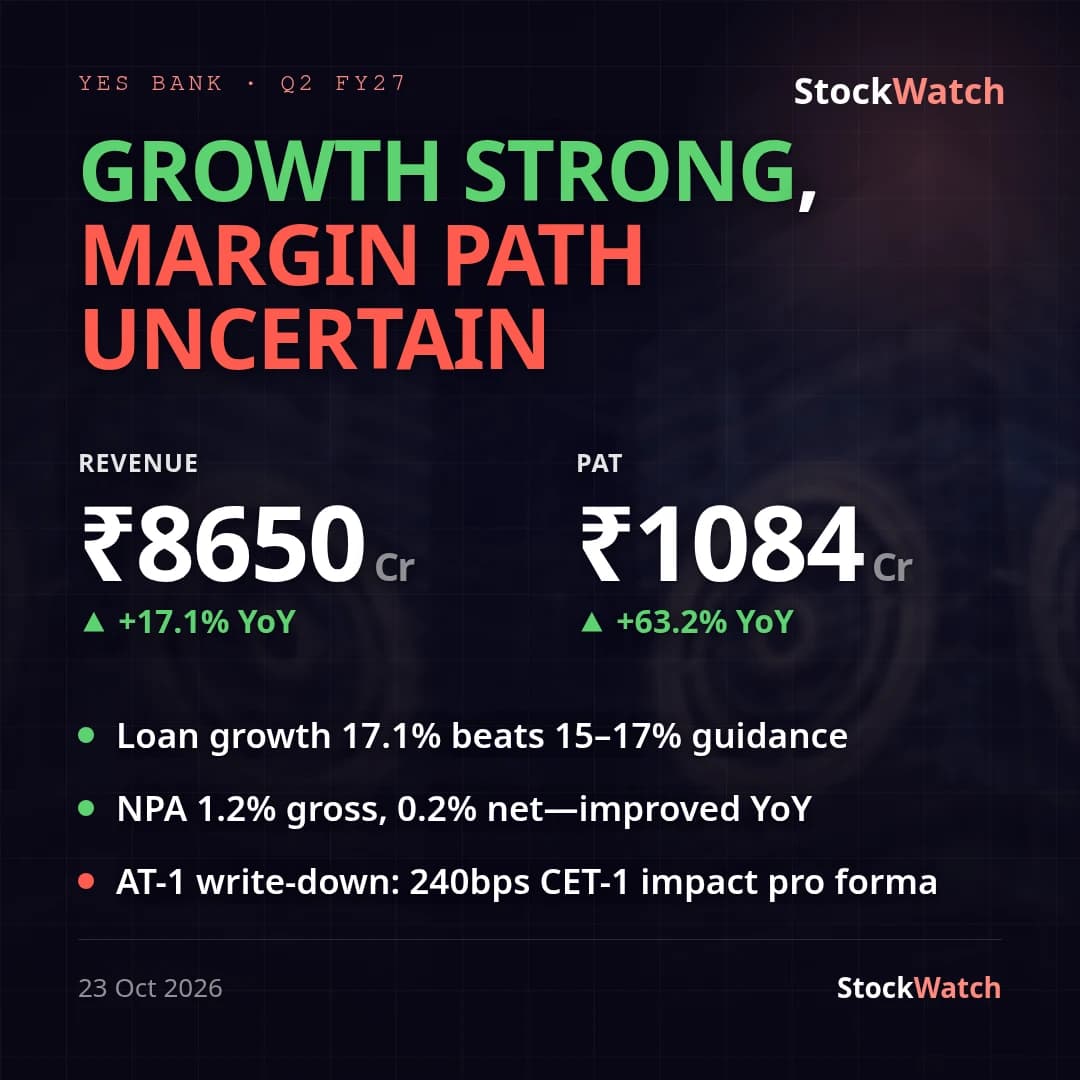
YES Bank's consolidated net profit rose 63.2% YoY to ₹1,084 Cr in Q2 FY27 (from ₹664 Cr a year ago) on interest income (revenue) of ₹8,650 Cr, up 17.1% YoY — comfortably ahead of our pre-result preview's ~₹1,100+ Cr expectation range, essentially in line. Sequentially the print was flat: PAT rose just 1.1% QoQ versus ₹1,072 Cr in Q1 FY27, even as revenue grew a faster 7.4% QoQ, so the YoY strength is the real story while the quarter-on-quarter trajectory has stalled. Standalone PAT of ₹1,080 Cr tracks within 0.4% of the consolidated number, so the two bases tell the same story.
Margins expanded YoY but compressed sequentially: net profit margin was 10.23% of total income versus 7.29% a year ago but down from 10.80% in Q1 FY27, and operating margin (on interest income) was 19.46% versus 17.73% YoY but down from 21.17% QoQ. The QoQ squeeze shows up in net interest income, which grew only 1.3% QoQ (₹2,820 Cr vs ₹2,785 Cr) even as gross interest income grew 7.4% QoQ — cost of funds is rising faster than yields, consistent with the deposit-competition and NIM-pressure risks our pre-result preview flagged. Loan growth, by contrast, ran well ahead of management's own guidance: advances rose 23.7% YoY to ₹3.10 lakh Cr (matching the Bank's own provisional 23.8% update) against a guided 15–17% FY27 range, and deposits grew 19.5% YoY to ₹3.54 lakh Cr. Annualised ROA held at 0.9%, up from 0.6% a year ago and tracking toward management's stated FY27 aspiration of 1% ROA, though not yet there. Asset quality improved on both counts — gross NPA eased to 1.2% from 1.3% QoQ (1.6% YoY), net NPA held steady at 0.2% — while capital adequacy (Basel III) slipped to 14.6% from 15.2% QoQ. No management press release was available in our records for this filing, so there is no fresh commentary from the Bank to cross-check against the print beyond the figures themselves.
The dominant development this quarter sits outside the P&L: the Hon'ble Supreme Court, in a judgment dated October 15, 2026 — two days before this result — dismissed the Bank's appeal and upheld the Bombay High Court's 2023 ruling that the Bank's March 2020 write-down of ₹8,415 Cr of Additional Tier-1 bonds was invalid. The Bank states it is still evaluating the legal, accounting and timing implications and has NOT recognized any impact in these results. For transparency it discloses proforma numbers: had the reversal been booked, consolidated net profit for the quarter would have been a loss of roughly ₹5,213 Cr (₹4,141 Cr for the half year) instead of the reported ₹1,084 Cr profit, with annualised ROA swinging to roughly -4.3%. This is a live, unresolved contingency of a scale that dwarfs the quarter's reported earnings and will be the key item to track into Q3. Separately, the Bank's ESG rating improved to 79 (Oct 16) and it disclosed a pending ₹363 Cr tax refund (Sep 30) — both minor relative to the AT1 overhang.
Against the Street, coverage going into the print was split — Nomura Neutral with a ₹23 target citing positives already priced in, while Citi, Investec, Morgan Stanley and JPMorgan were Sell/Underweight on valuation and structural margin concerns (Bloomberg consensus target ₹21.10). The operating print itself — strong YoY profit and loan growth, improving asset quality — broadly supports the bulls' case on execution, but does nothing to resolve the AT1 legal overhang that was the bears' core worry, and the sequential NIM pressure is visible exactly where the skeptics said to look.