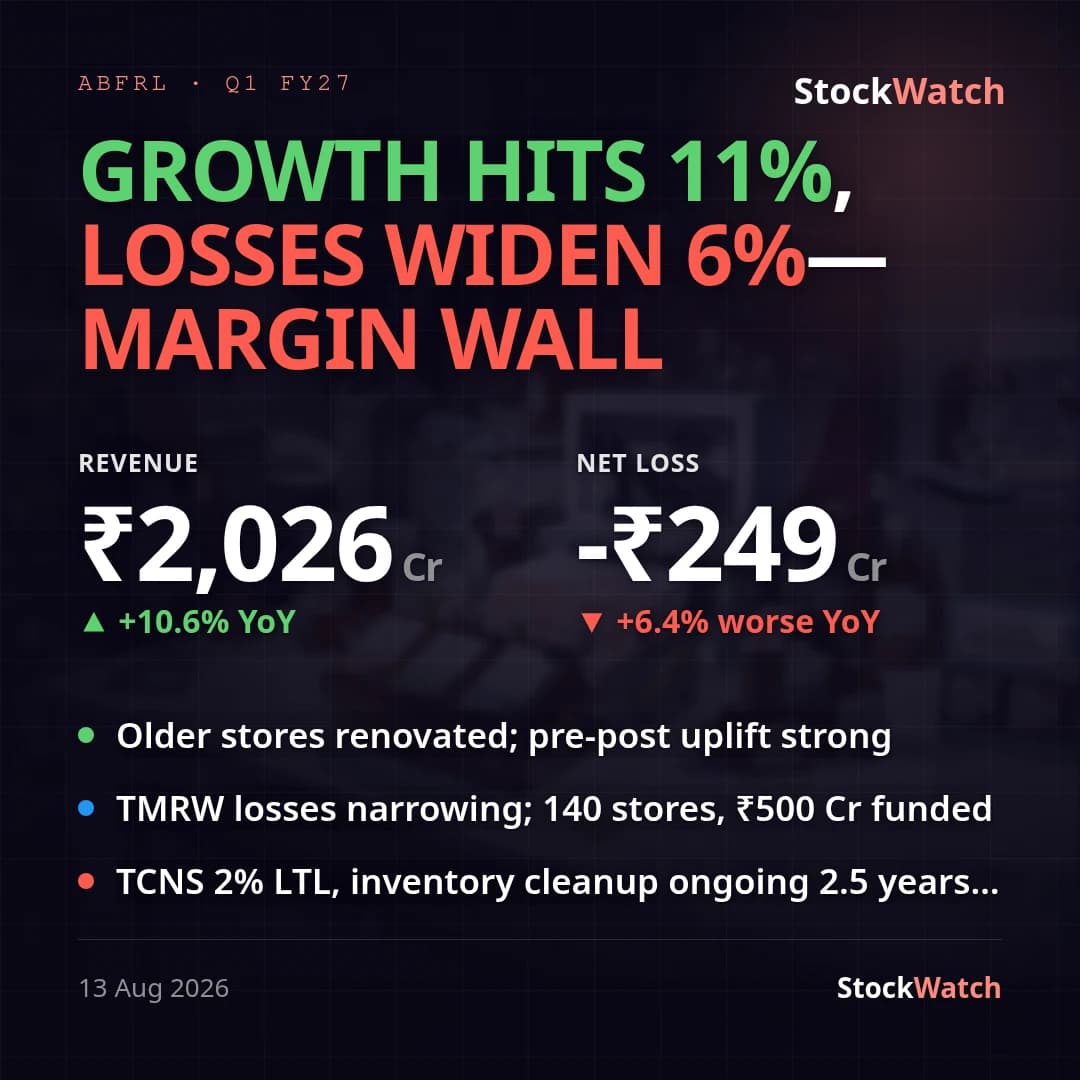
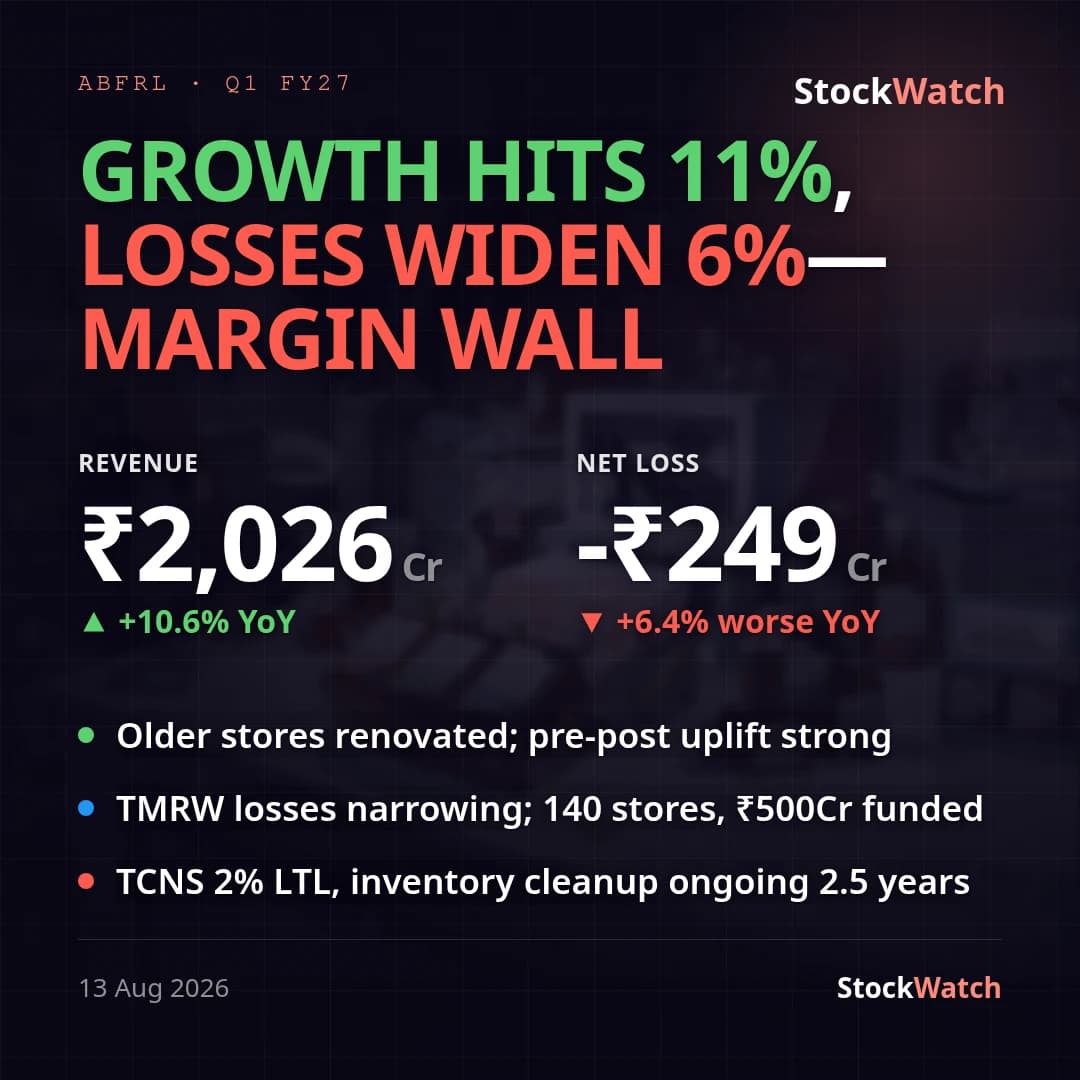
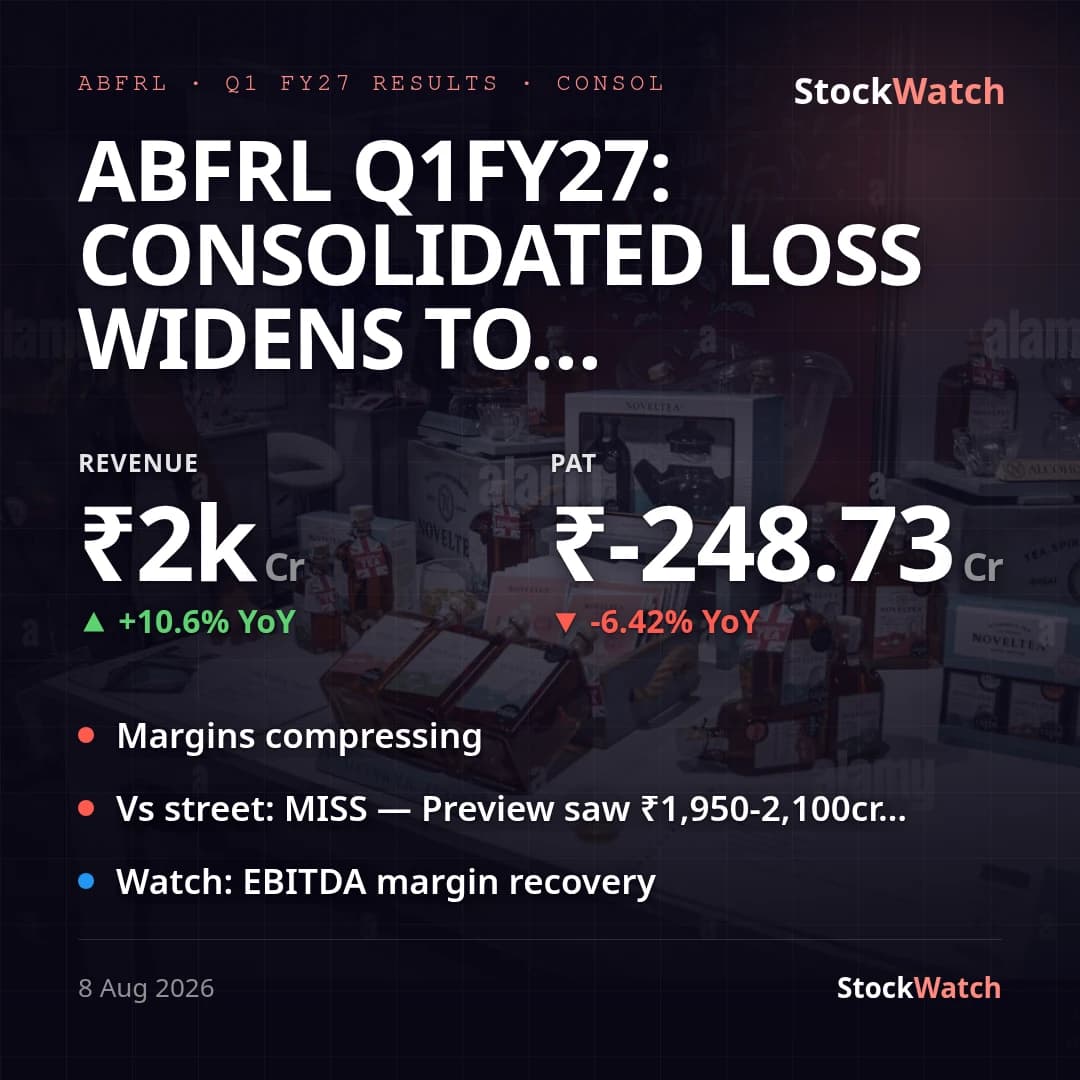
ABFRL Q1FY27: consolidated loss widens to ₹249 Cr as revenue rises 11%, margin slips
Aditya Birla Fashion and Retail's consolidated (primary) numbers show revenue from operations up 10.6% YoY to ₹2,025.6 Cr (+1.8% QoQ), but the consolidated net loss widened to ₹248.7 Cr (owners' share ₹215.2 Cr) from ₹233.7 Cr a year ago — a 6.4% deterioration — and ballooned versus Q4FY26's ₹163.8 Cr loss, though the QoQ jump is largely the usual Q1 seasonal air-pocket for Indian fashion retail (Q4 carries EOSS and wedding-season tailwinds). Against our pre-result preview, which flagged revenue of ₹1,950-2,100 Cr, an EBITDA margin of 11-12% and a net loss of ₹100-150 Cr as the bar, the print lands revenue in-range but misses badly on both margin and the bottom line: self-computed EBITDA margin (segment EBIT + D&A, on revenue) came in near 8.2%, and the loss ran ₹65-100 Cr wider than the preview's expected range — a clear miss versus Street's own framing, not just a beat/miss on revenue alone. We found no fresh independent brokerage consensus specific to this print beyond our own preview (JM Financial Buy/₹75 target, ICICI Securities Neutral/₹68, ~₹72 consensus as of June 2026), so vsStreet is graded against that internal bar.
The margin miss traces to the Ethnic & Others segment (TMRW, digital, ethnic portfolio), which grew revenue 10.1% YoY to ₹830.8 Cr but saw its segment loss widen to ₹188.5 Cr from ₹178.8 Cr a year ago — still the group's core drag despite the segment growing faster than Pantaloons in percentage terms. Pantaloons itself grew revenue 10.1% YoY to ₹1,204.4 Cr and stayed roughly breakeven (₹3.5 Cr segment profit vs ₹3.7 Cr a year ago), a swing from a ₹26.4 Cr segment loss in Q4FY26. Finance costs rose 20.9% YoY to ₹137.1 Cr, keeping the standalone interest service coverage ratio deeply negative (-8.56x). Standalone (secondary) loss was just ₹106.4 Cr, less than half the consolidated ₹248.7 Cr loss — the divergence sits almost entirely in loss-making digital/ethnic subsidiaries that consolidate only at group level, so readers should not read the smaller standalone loss as the group's real picture.
Management's Q4FY26 concall guidance called for continued double-digit growth (delivered: +10.6% YoY) alongside improved operating leverage and margin profile (not delivered: consolidated segment EBIT loss widened to ₹184.5 Cr from ₹175.1 Cr YoY) — so guidance was met on the top line but missed on the more consequential margin promise. No separate management press release was available with this filing; the only management-flagged items in the notes are the completed Jaypore E-Commerce/TG Apparel & Decor amalgamation (NCLT order July 2, 2026, effective August 1, 2026, restating standalone comparatives) and the ₹175 Cr rights-issue investment that lifted ABFRL's stake in Indivinity Clothing Retail (TMRW) to 89.29% from 85.54%. Company developments this quarter also include a ₹51.5 lakh GST penalty from Hyderabad authorities (immaterial), the FY26 BRSR/Integrated Annual Report release, and the 19th AGM notice for August 25, 2026 — none of which move the P&L narrative. The August 10, 2026 earnings call is the next checkpoint for whether management still stands behind its TMRW-profitable-by-FY29 and Tasva-breakeven-by-FY28 timelines given this quarter's widening ethnic-segment loss.