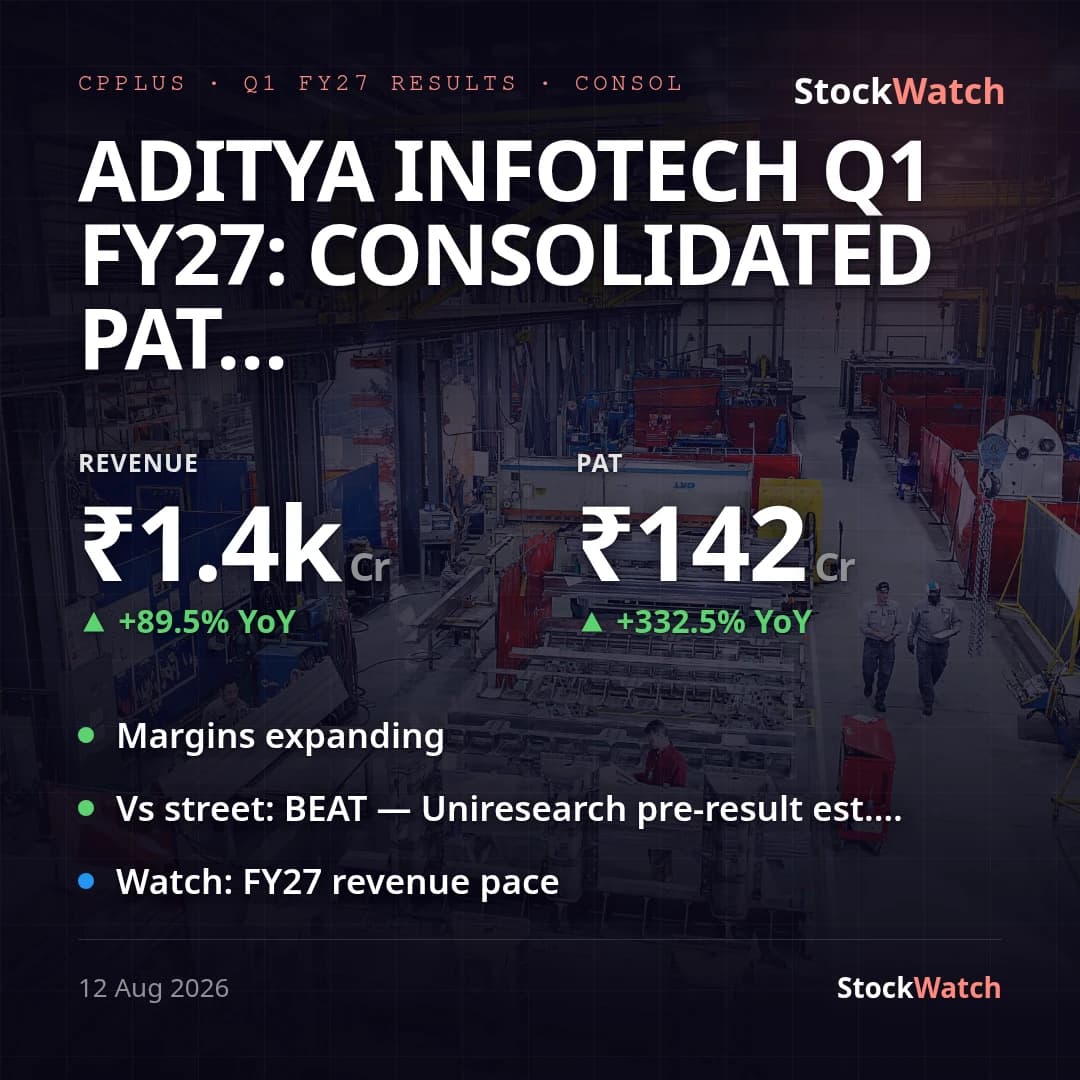
Aditya Infotech Q1 FY27: Consolidated PAT Jumps 332% YoY to ₹142 Cr, Margins Expand
Aditya Infotech's consolidated Q1 FY27 (quarter ended 30 June 2026) revenue came in at ₹1,402.4 Cr, up 89.5% YoY from ₹740.0 Cr, while PAT more than quadrupled to ₹142.2 Cr from ₹32.9 Cr a year ago (+332.5% YoY). Both figures crushed pre-result Street estimates — Uniresearch had modeled ~₹840 Cr revenue and ~₹40 Cr PAT for the quarter — a beat of roughly 67% on revenue and 255% on profit, confirming the print is a genuine outperformance rather than a base-effect artifact alone. Sequentially, revenue was flat (-1.4% QoQ) and PAT fell 15.9% QoQ off Q4 FY26's ₹169.1 Cr, but Q4 (Jan-Mar) is this company's seasonally heaviest quarter on enterprise/govt capex cycles, so the QoQ dip should not be read as momentum loss — the YoY comparison is the primary signal here.
Margins expanded sharply on a YoY basis: OPM (EBITDA/revenue) rose to 14.8% from roughly 8.2% a year ago, and NPM to 10.1% from 4.4%, driven by operating leverage on the higher volumes and a large favourable swing in inventory movement as the manufacturing/backward-integration push (reflected in a new 'cost of materials consumed' line this quarter) scales. Against management's FY27 guidance from the May 2026 concall — revenue ₹6,000-6,500 Cr, EBITDA margin 14-15%, PAT margin 8.5-9.5% — this quarter's OPM of 14.8% sits inside the guided band and NPM of 10.1% is already above the top of the guided PAT-margin range, a beat on the profitability leg of guidance one quarter in. Revenue of ₹1,402 Cr is about 21-23% of the FY27 target, plausible given Q4 typically carries a disproportionate share (Q4 FY26 alone was ₹1,691 Cr of FY26's ₹4,220.8 Cr).
Standalone results tell a consistent story (revenue +91.4% YoY to ₹1,398.6 Cr, PAT +353.0% YoY to ₹140.9 Cr), confirming the growth and margin trends are not a consolidation artifact — the three subsidiaries reviewed by other auditors contributed a modest ₹94.4 Cr revenue and ₹6.4 Cr PAT combined. The quarter's corporate actions reinforce the capacity-building narrative flagged pre-result: the 50:50 cable manufacturing JV with Orient Cables, Corelink Cable Technology, was incorporated on 10 June 2026 and is consolidated for the first time this quarter, and the Taiwan subsidiary (onboarded February 2026) is also now in the group numbers. The board's FY26 final dividend of ₹1.64/share was ratified at the 4 August 2026 AGM, and IPO proceeds (₹476.4 Cr) stand fully utilised toward debt repayment and general corporate purposes.
One gap versus the pre-result watch list: the $5M ICC arbitration claim from Avathon/SparkCognition, flagged as a key disclosure to watch, does not appear as a note or contingent liability anywhere in this unaudited statement — management has not yet quantified estimated liability, loss probability, or insurance coverage in this filing, leaving that item unresolved heading into Q2. Management's own exchange disclosure headline ('Q1 FY27 Revenue Surges 89.5% to ₹1,402.4 Cr') matches the extracted numbers exactly; no separate press release commentary was available in the context to cross-check drivers beyond the financial notes.