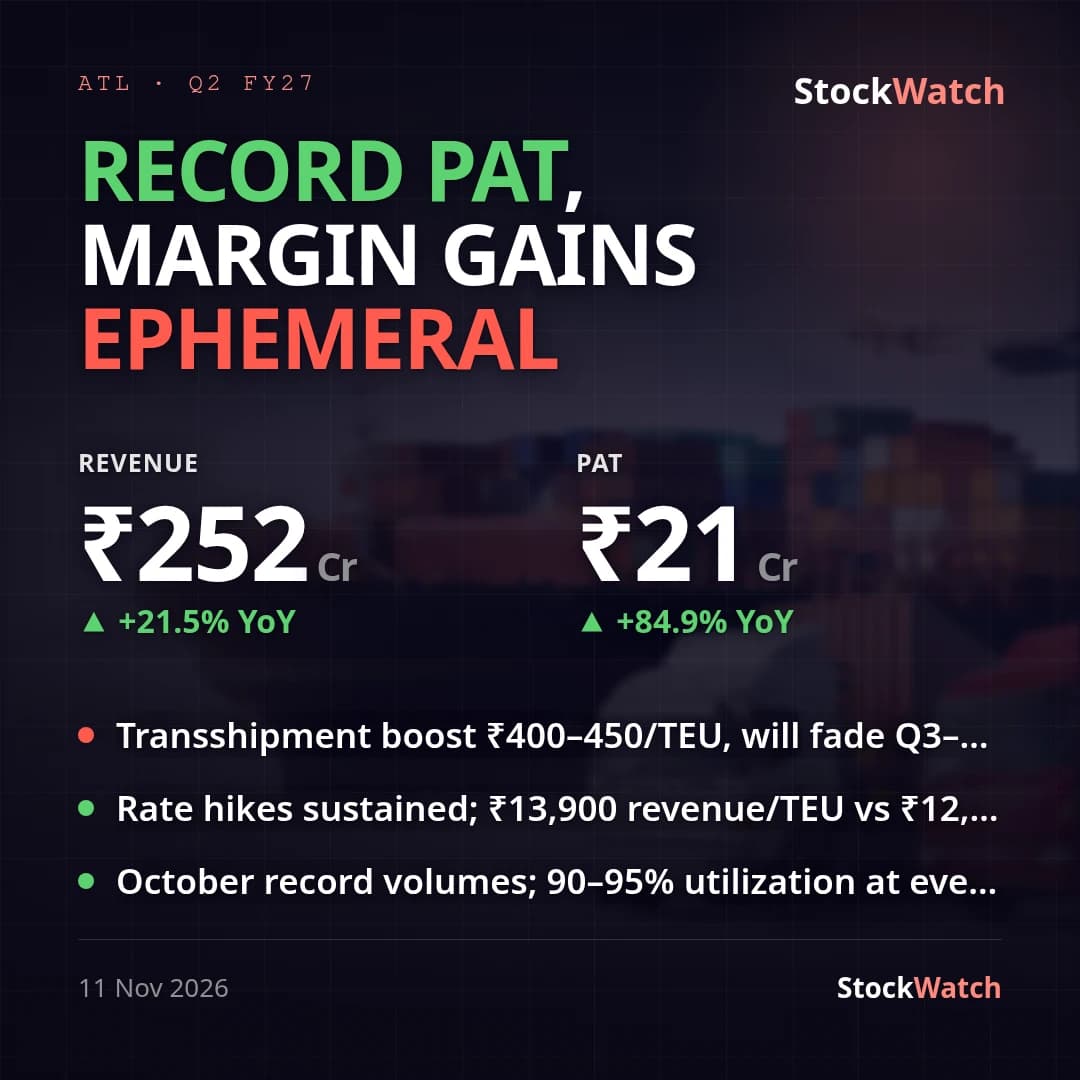
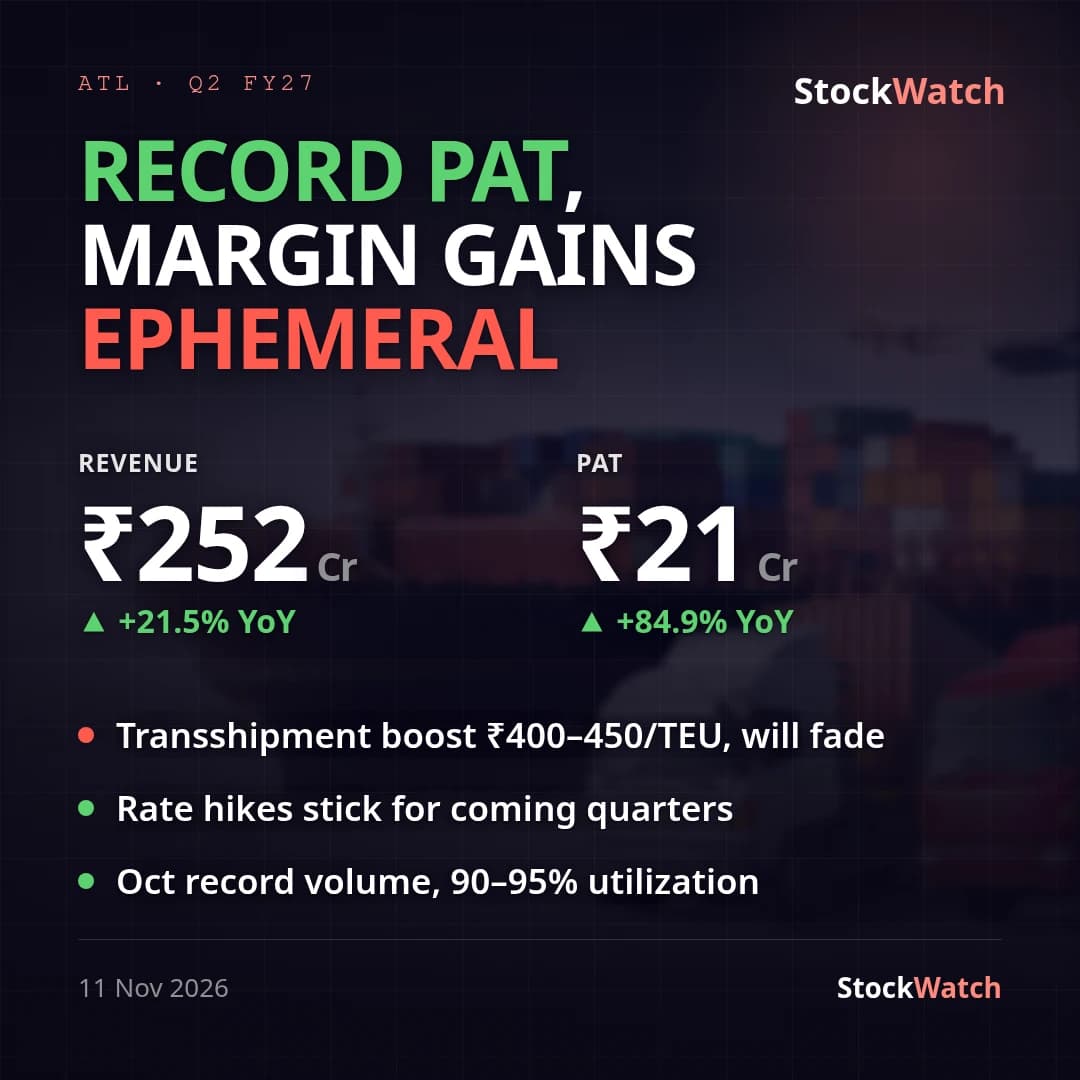
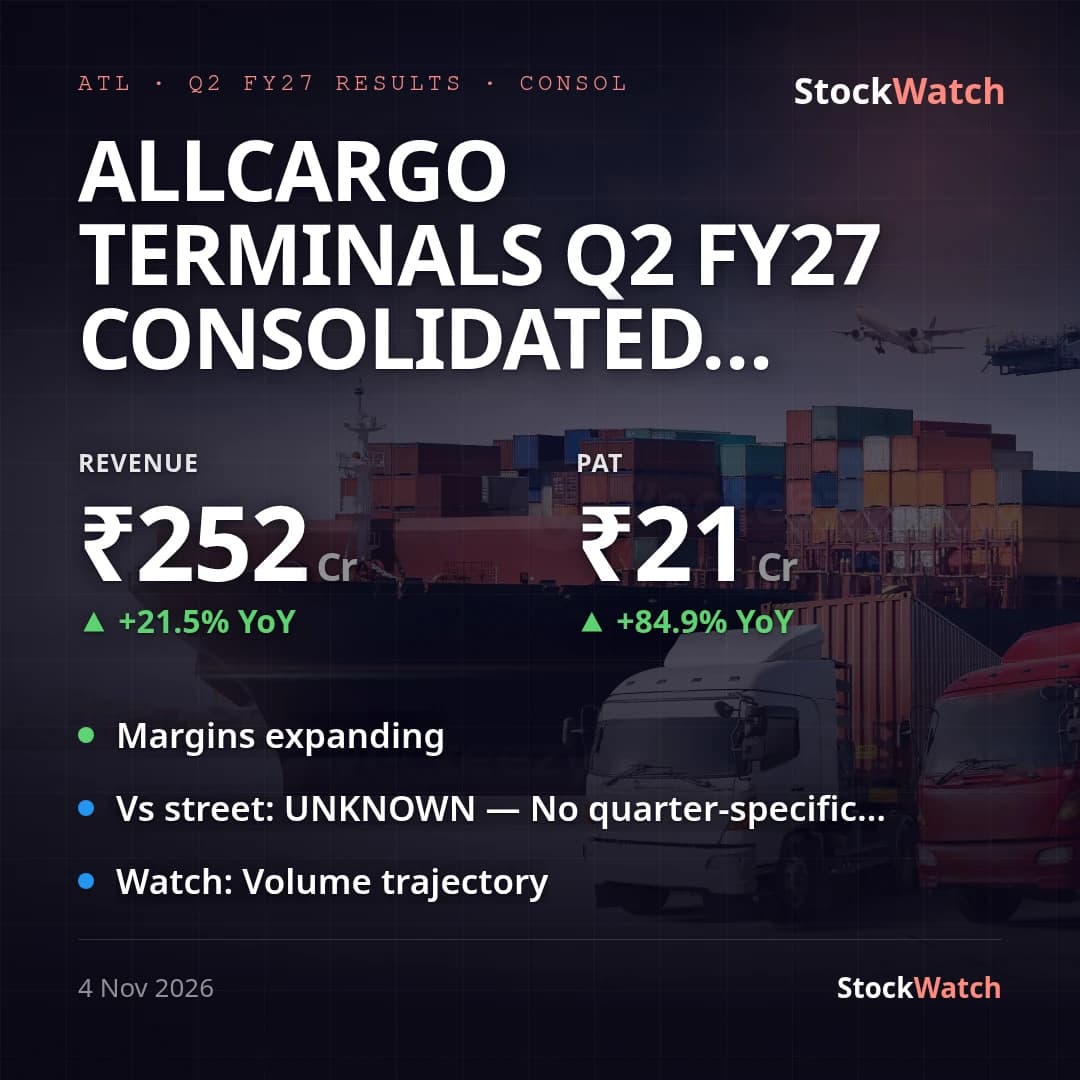
Allcargo Terminals Q2 FY27 consolidated PAT +85% YoY to ₹20.9 Cr as margins expand
Allcargo Terminals' consolidated PAT (owners) came in at ₹20.89 Cr for Q2 FY27, up 84.9% year-on-year from ₹11.30 Cr in Q2 FY26, on revenue of ₹251.63 Cr, up 21.5% YoY from ₹207.16 Cr. Sequentially, PAT jumped 228% from Q1 FY27's ₹6.37 Cr and revenue grew 17.4% from ₹214.41 Cr — but the QoQ profit number is flattered by a weak Q1 base, so the YoY read (profit growth nearly 4x revenue growth) is the real story: this is margin-led, not just volume-led, growth. No exceptional items sit in either the current or year-ago quarter, so the growth is clean/unadjusted.
The margin bridge: consolidated OPM (EBITDA/revenue) expanded to 23.39% from 19.47% a year ago (+392 bps) and from 22.14% last quarter (+125 bps); NPM rose to 8.21% of total income from 5.39% YoY. The expansion shows up mainly in operating leverage — operating, employee and other expenses together grew slower than revenue — while finance cost (₹15.89 Cr) and depreciation (₹20.88 Cr) stayed roughly flat YoY. Standalone PAT, by contrast, rose just 9.4% YoY to ₹7.77 Cr on revenue of ₹164.07 Cr (+16.8% YoY) — a materially slower pace than the consolidated number, meaning the bulk of this quarter's earnings growth came from subsidiaries/JVs: the Group's share of JV/associate profit was ₹2.27 Cr (vs ₹2.00 Cr YoY), and subsidiary Speedy Multimodes contributed total net profit of ₹11.14 Cr for the quarter per the auditor's consolidation note. Readers tracking the standalone print separately should note it tells a much more moderate growth story than the consolidated headline.
No formal Street consensus for this specific quarter was found (vsStreet: unknown) — Allcargo Terminals is thinly covered and this result was only just announced. The closest available read is a brokerage view (Univest) projecting 15-20% PAT growth for full FY27; H1 FY27 consolidated PAT of ₹27.26 Cr is already up 33.6% YoY (₹20.41 Cr), running ahead of that full-year range through the first half. On management's own prior guidance (Q1 FY27 concall): the FY30 aspiration is ~20% EBITDA margin, and this quarter's 23.39% OPM already clears that bar, suggesting the business is ahead of plan on margin execution even though FY30 revenue/volume scale (₹1,400 Cr revenue, 12.5-13 lakh laden TEUs) remains a multi-year build. On the ground, volumes were mixed within the quarter: September 2026 throughput fell 7% YoY to 61.8k TEUs, though October 2026 (just after quarter-close) already rebounded to +4% YoY — an early signal worth confirming in Q3. The company also ratified related-party transactions (Oct 14) and took a ₹1.06 Cr stake (25%) in associate Allcargo Group Services Pvt Ltd during the quarter, a small addition to the JV/associate portfolio rather than a material driver of the print.
Going into Q3 FY27, the watch items are whether the October volume rebound holds, whether the 23%+ OPM is sustainable as the Farukhnagar ICD (due Q3 FY27) and the 60k-TEU Speedy JNPT expansion (Jan-Feb 2027) come online and add depreciation/finance-cost load, and whether the consolidated-standalone profit divergence narrows or persists.