StockWatch
·

ANDHRA CEMENTS LTD.

BSE: 532141

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27·vs Q2 FY26
Revenue
166.95
+16.5%+112.8%
Expenditure
204.61
+7.1%+70.0%
Net Profit
-28.35
+21.1%+32.4%
OPM %
8.57%
+5.94pp+14.35pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
-80.45-1.5577.35156.25235.15Q2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

Andhra Cements Q2: loss narrows to ₹28.4 Cr YoY as revenue doubles, OPM turns positive

cement · margin expansion · capacity expansion

ResultsQ2 FY2730 Oct 20263 minIndustrials & Infra

The Distress Ladder: Three Stocks Sliding Down Different Rungs

distress · regulatory · operational losses

ResearchDeep dive27 Jul 20266 minEnergy & Oil/Gas

Andhra Cements Q1: PBT loss widens 61% YoY to ₹47.8 Cr despite 43% revenue growth

cement · loss widening · margin compression

ResultsQ1 FY2727 Jul 20263 minIndustrials & Infra
Latest
Quarterly Result30 Oct, 3:52 pm

Andhra Cements Q2: loss narrows to ₹28.4 Cr YoY as revenue doubles, OPM turns positive

Andhra Cements' standalone net loss narrowed to ₹28.35 Cr for the quarter ended September 30, 2026, from ₹41.94 Cr a year earlier and ₹35.93 Cr last quarter, as revenue from operations more than doubled YoY (+113%) to ₹165.98 Cr and grew 17% sequentially — the payoff from the grinding capacity expansion to 3.00 MTPA completed in late September 2026. No consolidated statement accompanies this filing; the company reports standalone only. The margin story is genuinely stronger: OPM swung to +8.57% from -5.78% YoY and 2.63% QoQ, and NPM improved to -17.0% from -53.5% YoY and -25.1% QoQ. But the 32% YoY narrowing in net loss overstates the underlying operating improvement — at the pre-tax level the loss narrowed only about 10% YoY (₹37.66 Cr vs ₹41.92 Cr), with the gap explained by a ₹9.31 Cr non-cash deferred-tax credit this quarter versus nil tax a year ago (Note 6, Section 115BAA remeasurement based on projected future taxable income). Finance costs (₹31.79 Cr) and depreciation (₹21.06 Cr) together still absorb roughly a third of revenue, as debt funding the expansion pushed total borrowings to ~₹1,184 Cr, up ~6% since March 2026. A separate ₹1.18 Cr MBL Cess provision reversal at the Dachepalli mines (Note 8) added a minor one-off credit to other expenses. There is no analyst coverage or consensus estimate for this micro-cap on record — a web search for Q2 FY27 previews turned up none — and the company has issued no formal guidance either in our records or found via search, so the print cannot be graded against street or management expectations. The larger corporate overhang is the proposed Scheme of Amalgamation merging Andhra Cements into parent Sagar Cements Limited (appointed date April 1, 2026, board-approved June 5, 2026), still pending Stock Exchange/SEBI/NCLT approval; once cleared it ends ACL's standalone listing. Statutory auditors B S R and Co issued an unmodified limited-review conclusion on these results. Going into Q3, the markers to watch are whether the OPM gain holds now that the expanded capacity is fully online, how much of future PAT improvement continues to depend on non-cash deferred-tax credits rather than operating cash flow, and the pace of regulatory clearance for the Sagar Cements merger.

30 Oct 2026, 03:52 pm

Quarterly Result27 Jul, 1:53 pm

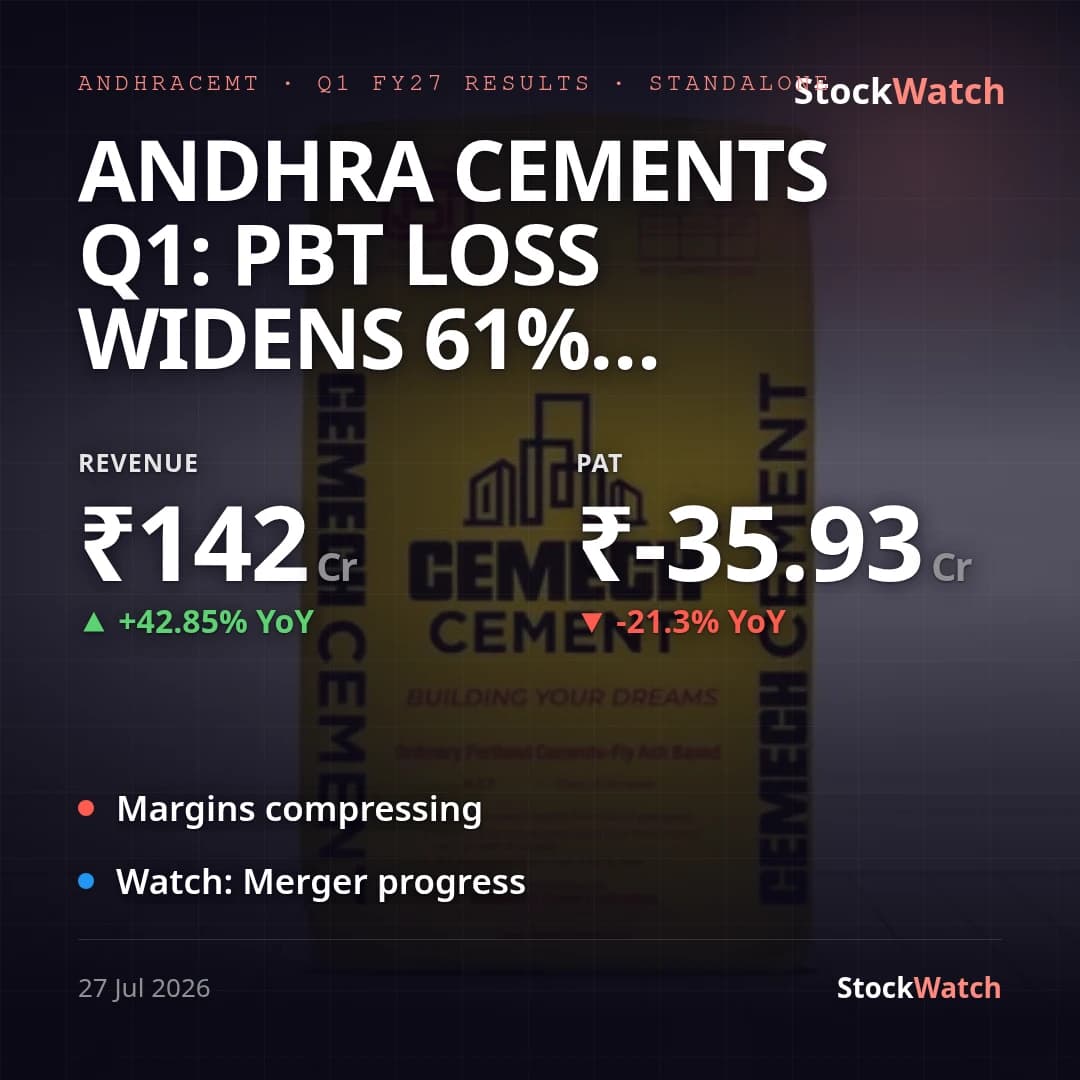
Andhra Cements Q1: PBT loss widens 61% YoY to ₹47.8 Cr despite 43% revenue growth

Andhra Cements' standalone Q1 FY27 (June 2026) results show revenue from operations of ₹142.17 Cr, up 42.85% YoY from ₹99.53 Cr but down 8.19% QoQ from ₹154.85 Cr in the seasonally stronger Q4 FY26. The company remained loss-making on both a YoY and sequential basis: net loss came in at ₹35.93 Cr (EPS -₹3.90) versus a ₹29.62 Cr loss (EPS -₹3.21) a year ago, and versus a ₹48.52 Cr profit in Q4 FY26 — this is not a turnaround, it is a continuation and deepening of losses. The pre-tax loss widened 61.3% YoY to ₹47.77 Cr as total expenses rose 46.8% YoY to ₹191.13 Cr, outpacing the 42.85% revenue growth. The biggest cost swings were an inventory drawdown that added ₹15.89 Cr to expenses (versus a near-nil ₹0.22 Cr impact a year ago), freight costs up 60.7% YoY to ₹33.55 Cr, finance costs up 55.5% YoY to ₹31.94 Cr, and power & fuel up 19.3% YoY to ₹49.14 Cr. Operating margin (EBITDA/revenue) compressed to 2.63% from 6.67% a year ago and 5.70% in Q4 FY26 — core profitability eroded even as the topline grew. The reported net loss was cushioned only by an ₹11.84 Cr non-cash deferred tax credit (nil current tax, Note 6); stripping out tax-line volatility, the pre-tax loss actually widened 61.3% YoY, materially worse than the 21.3% widening in reported net loss — the headline net-loss number flatters the underlying operating trend. No street estimates or brokerage Q1 FY27 previews for this stock turned up in a web search, so vsStreet is unknown; the company has also issued no formal guidance or outlook on record for this quarter, so vsGuidance is unknown too. No management press release accompanied this filing (only the regulatory cover letter and financials), so there is no management commentary to reconcile against the print. The dominant corporate development this quarter is the Board-approved Scheme of Amalgamation (approved June 5, 2026) merging Andhra Cements into parent Sagar Cements with effect from April 1, 2026, still subject to NCLT, SEBI, shareholder and creditor approvals — a process that overshadows the standalone operating numbers since ACL's independent listing is itself headed for wind-down. Separately, Sagar Cements' OFS across January–March 2026 cut its stake in ACL from 90% to 75% to meet minimum public shareholding norms. Going forward, the merger timeline is the primary swing factor for the stock since standalone reporting will cease once the amalgamation completes; near-term operating monitorables are whether deferred tax asset recognition (based on projected future taxable income per Note 6) continues to be booked to cushion losses, and whether the freight/finance cost pressure behind the 61% pre-tax loss widening persists into Q2 FY27.

27 Jul 2026, 01:53 pm

Corporate Events

Board MeetingACL
2026
30Oct

Board Meeting

The Board of Directors meeting is scheduled to consider and …

BSE Filing ↗
Board MeetingACL
2026
27Jul

Board Meeting

The Board Meeting will be held to consider and take on recor…

BSE Filing ↗
Board MeetingACL
2026
5Jun

Board Meeting

The board meeting is scheduled to consider and approve a Sch…

BSE Filing ↗
Board MeetingACL
2026
21Jan

Board Meeting

Notice of the Board Meeting, Consider and approve un-audited…

BSE Filing ↗
Board MeetingACL
2025
23Oct

Board Meeting

Consider and approve Intimation of board meeting and other m…

BSE Filing ↗
Board MeetingACL
2025
21Jul

Board Meeting

consider and approve, consider and take on record

BSE Filing ↗
Board MeetingACL
2025
12May

Board Meeting

Intimation of board meeting, Consider and approve audited fi…

BSE Filing ↗
Board MeetingACL
2025
24Jan

Board Meeting

consider and approve Board Meeting, consider and take on rec…

BSE Filing ↗
Board MeetingACL
2024
18Jul

Board Meeting

Consider and approve Intimation of board meeting, take on re…

BSE Filing ↗
Board MeetingACL
2024
14May

Board Meeting

Consider and approve audited financial results of the compan…

BSE Filing ↗
Board MeetingACL
2024
28Mar

Board Meeting

consider and approve fund raising

BSE Filing ↗
Board MeetingACL
2023
19Oct

Board Meeting

consider and approve un-audited standalone financial results

BSE Filing ↗