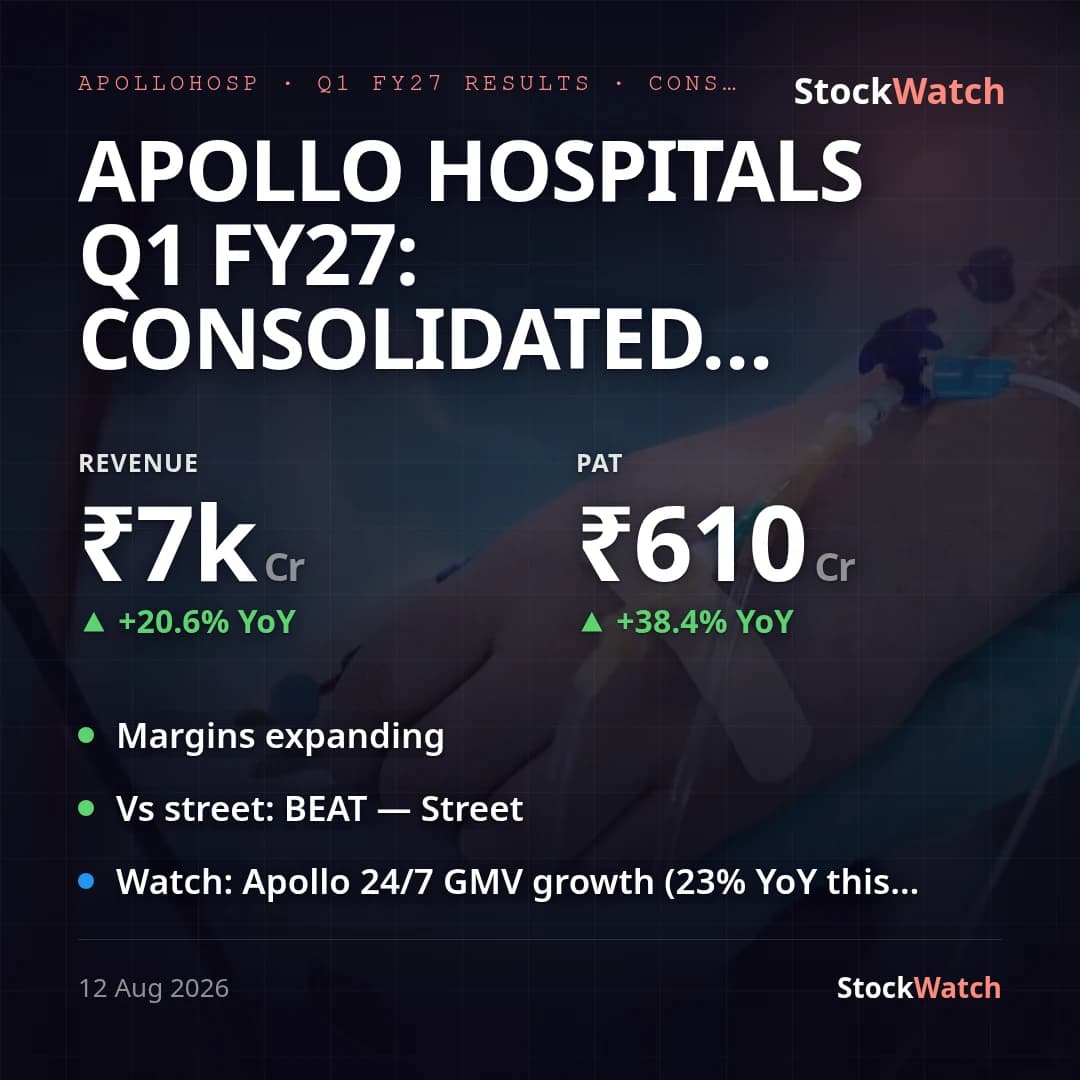
Apollo Hospitals Q1 FY27: consolidated PAT +38% YoY to Rs.610 Cr as revenue grows 21%, margins expand
Apollo Hospitals' consolidated Q1 FY27 (three months to June 30, 2026) revenue rose 21% YoY and 6.6% QoQ to Rs.7,043.5 Cr, with consolidated EBITDA up 28% YoY to Rs.1,092 Cr (margin ~15.5% vs 14.6% a year ago and 15.3% last quarter). Reported PAT for the period (before minority interest, matching the statement's PAT row) was Rs.610.4 Cr, up 38.4% YoY and 10.7% QoQ; the owners-attributable PAT the company headlines in its press release was Rs.580.7 Cr (+34% YoY), the Rs.29.7 Cr gap going to non-controlling interests in subsidiaries such as Apollo HealthCo and AHLL. There were no exceptional items in the quarter on either a standalone or consolidated basis, so the growth is clean — last year's Rs.19.2 Cr labour-code exceptional charge sat only in the FY26 full-year column, not in the Q1 FY26 base.
Growth was broad-based. Healthcare Services (hospitals) revenue grew 22% YoY to Rs.3,567 Cr with EBITDA up 20% YoY to Rs.862 Cr, even after absorbing a Rs.38 Cr EBITDA drag from newly launched capacity (Sarjapur plus the Financial District/Sonarpur/Pune/Delhi Oncology cohort); stripping that drag, underlying hospital EBITDA margin expanded over 100bps, consistent with management's guided margin offset from mature hospitals. Apollo HealthCo (pharmacy distribution + digital) grew revenue 20% YoY to Rs.2,977 Cr and lifted EBITDA margin to 6% from ~3.8%, narrowing its PAT loss to Rs.1 Cr from Rs.8 Cr a year ago. On a standalone (parent-only) basis, PAT grew a slower 25.5% YoY to Rs.385.2 Cr versus the consolidated 38.4% — a sizeable gap, since the faster-growing, higher-incremental-margin subsidiaries sit outside the standalone entity.
A pre-result preview (Univest) had flagged Q1 FY27 as a 'stable' quarter with revenue seen in a Rs.6,526-7,351 Cr range; the actual Rs.7,043.5 Cr print and 28% EBITDA growth came in ahead of that stable-quarter framing — a beat on the operating line, though no explicit street PAT consensus was found. Against management's own prior guidance (12-14% organic hospital growth plus 3-4% from new beds), Healthcare Services' 22% YoY growth beat the guided range; store-addition pace (151 net new stores this quarter, ~604 annualised vs a 600/year target) and new-bed start-up losses (Rs.38 Cr this quarter vs a guided ~Rs.150 Cr for all of FY27) are both tracking guidance. The one metric trailing its target is Apollo 24/7 GMV, up 23% YoY to Rs.535 Cr against a guided 30% FY27 growth rate. Separately, the board used the results meeting to approve PwC as incoming statutory auditor from the 46th AGM (succeeding Deloitte after two five-year terms), and noted the AHEL-AHL-Keimed Scheme of Arrangement (creating listed entity Apollo Healthtech) has moved to an NCLT sanction petition after June 24, 2026 shareholder/creditor approvals; AHL separately plans to slump-sell its ~Rs.3,610 Cr FMCG distribution undertaking to subsidiary Apollo Consumer Products by around October 1, 2026.
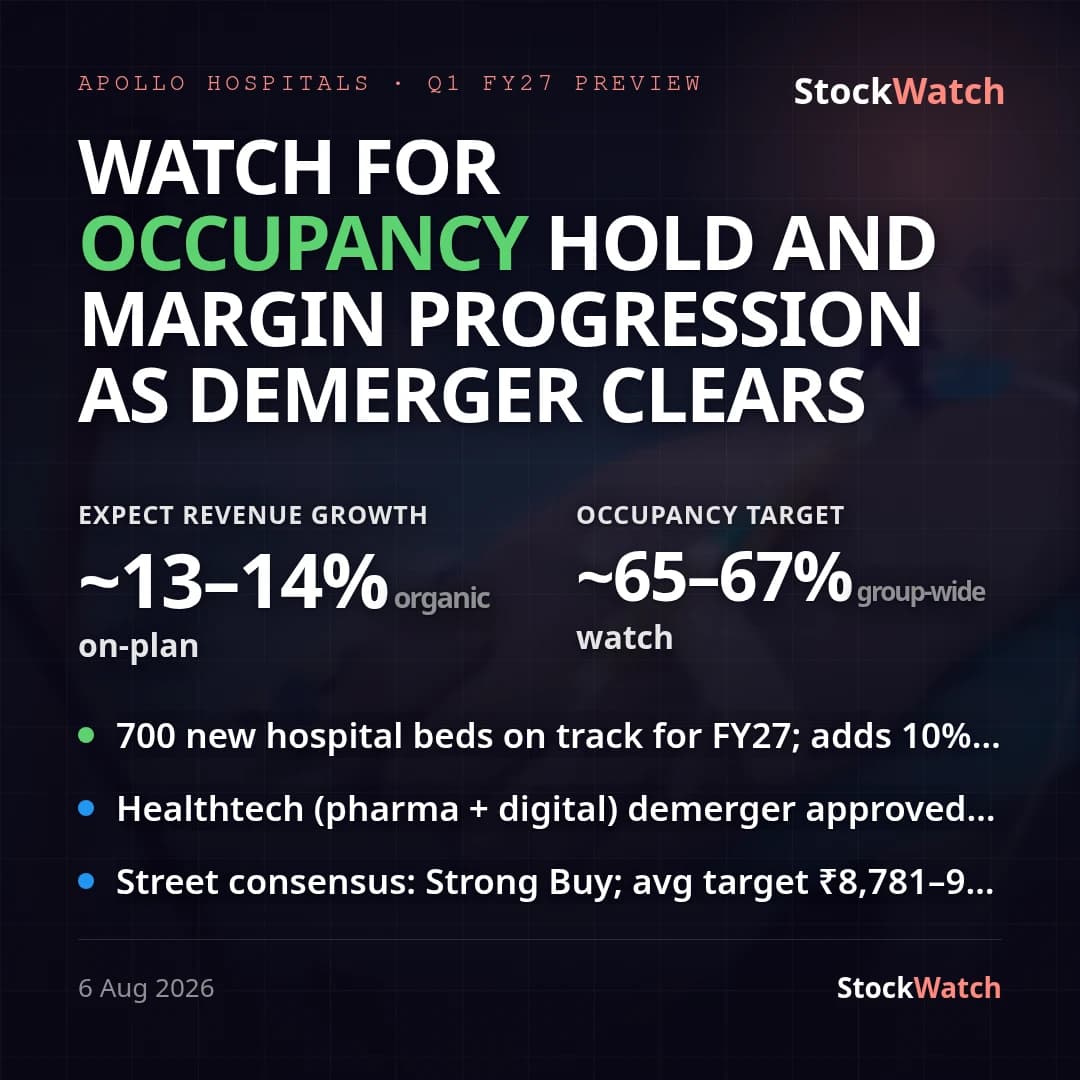
Founder-chairman Dr. Prathap Reddy's statement framed the quarter as reflecting 'the strength of our integrated model,' citing the 21% consolidated revenue growth across Healthcare Services, Diagnostics/Retail Health and Digital Health/Pharmacy — numbers that match the filing. Management's framing of steady international patient demand (IPS revenue +26% YoY) and disciplined capacity expansion (5,800 planned new beds over five years, four more hospitals announced in Indore, Dwarka, Delhi and Ranchi) sets up further near-term start-up-loss drag on hospital EBITDA even as the core network's occupancy (70% vs 65% YoY) and ARPP continue to climb. The next checkpoints are Apollo 24/7's GMV trajectory against the 30% FY27 guide, confirmation of digital cash-EBITDA breakeven (guided for this quarter but not separately broken out in this filing), and progress of the Apollo Healthtech demerger through the NCLT.