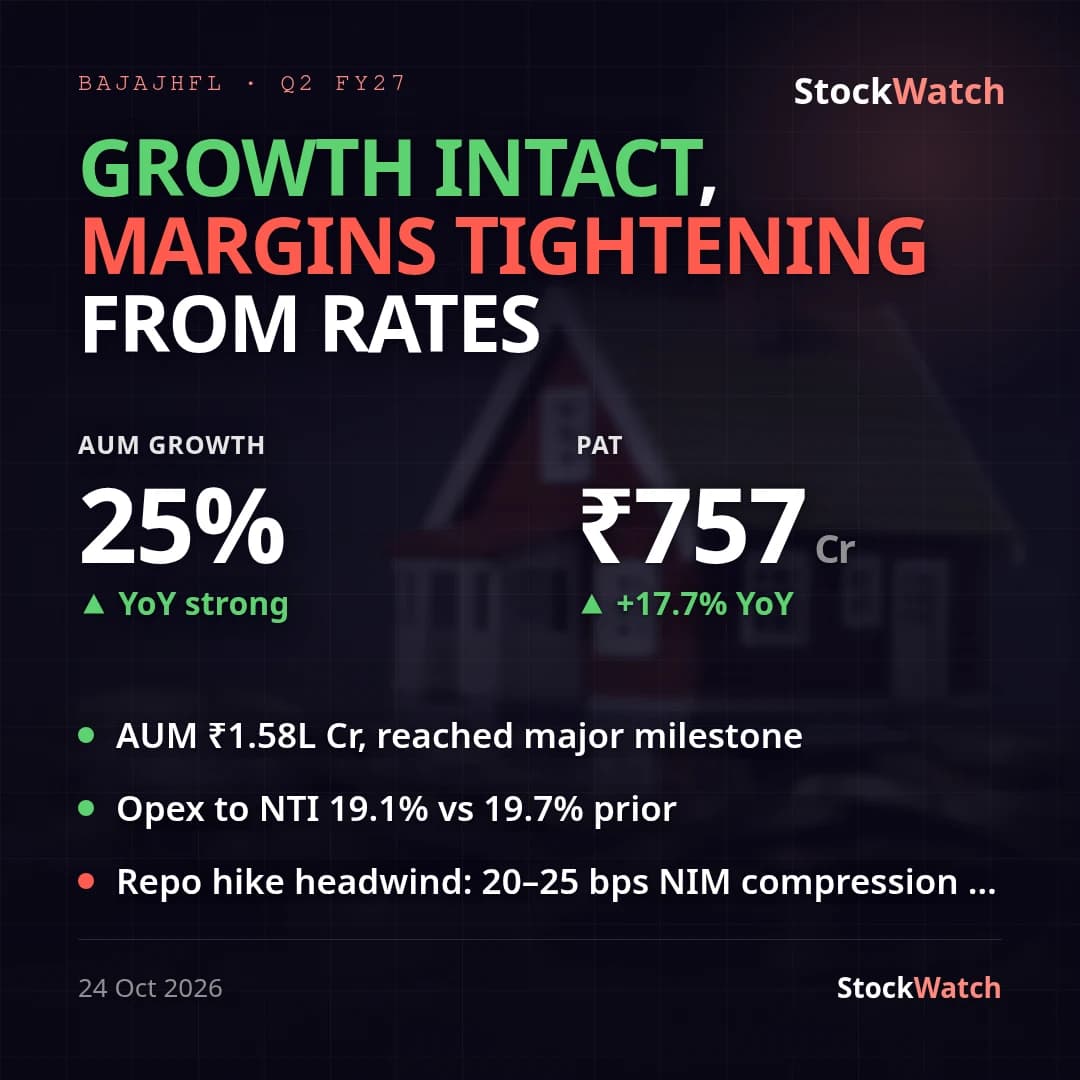
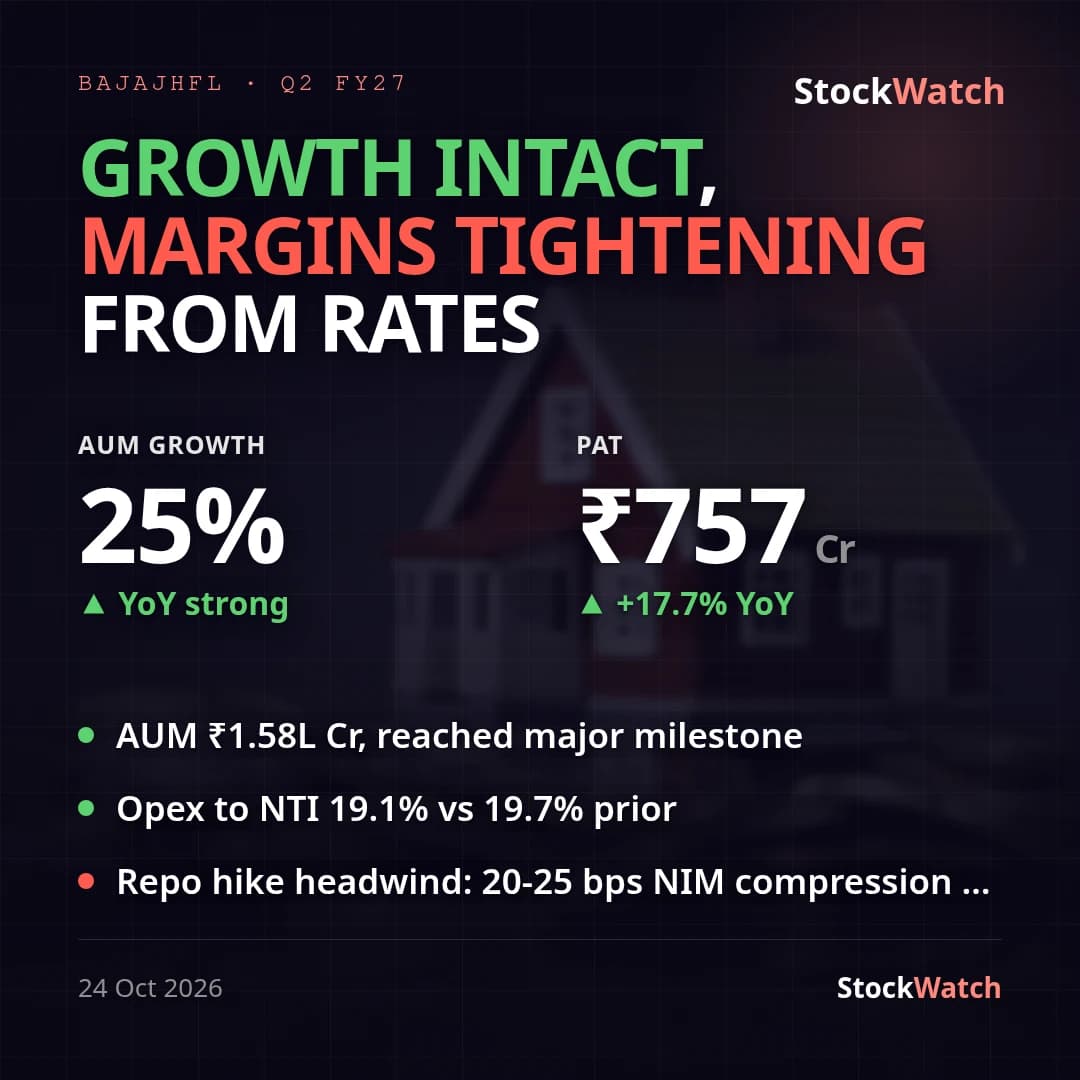
Bajaj Housing Finance Q2 FY27: standalone PAT +18% YoY to ₹757 Cr, margins steady
Bajaj Housing Finance's standalone PAT rose 18% YoY to ₹756.97 Cr (₹642.96 Cr in Q2 FY26) on revenue from operations of ₹3,250.57 Cr, also up 18% YoY. Sequentially the print was more modest — PAT +5.8% QoQ and revenue +6.1% QoQ versus Q1 FY27 — consistent with the YoY-anchored read: this is a steady scale-up, not an inflection. PAT comfortably beat the pre-result Street range of ₹540–600 Cr that our preview had flagged (consensus from 53 analysts, mostly Hold-rated), a clear beat on expectations, though the preview's NIM concern (3.5–3.6% expected) cannot be independently confirmed from this filing as BHFL does not disclose NIM directly.
Margins were flat to marginally down, not expanding: net profit margin was 23.28% of total income versus 23.35% in Q1 FY27 and 23.34% in Q2 FY26 — a sub-10bps move either way, effectively noise. The press release shows operating expenses at 19.1% of net total income (19.7% a year ago) and loan losses/provisions of ₹35 Cr, down from ₹43 Cr in Q2 FY26, so the modest margin give-back sits on the funding-cost side (finance costs rose to ₹1,996.65 Cr) rather than credit quality, which actually improved — GNPA 0.29% and NNPA 0.12% versus 0.26%/0.12% a year ago, still comfortably inside management's guided 30–35bps GNPA band.
On guidance, BHFL's FY27 management outlook (from the August 2026 concall) called for AUM growth of just 9–10.5%; actual AUM grew 25% YoY to ₹1,58,205 Cr, a large beat on that specific metric, with disbursements of ₹19,935 Cr (+25% YoY) spread across home loans (+22%), loan against property (+26%), lease rental discounting (+39%) and developer finance (+13%). ROA came in at 2.2% annualised, inside the guided 2.1–2.3% band, and opex-to-NTI at 19.1% is inside the guided 19–20% range, so on the quality/efficiency metrics the quarter tracked guidance precisely even as growth ran well ahead of it. Capital adequacy fell to 21.24% from 26.12% a year ago as the balance sheet scaled (debt-equity now 4.92x vs 4.44x), and the company funded growth partly through four NCD placements this quarter (₹2,439 Cr, ₹807.8 Cr, ₹495.5 Cr and ₹1,985 Cr) rather than fresh equity. Management's own press release framed the quarter around crossing the ₹1.5 lakh crore AUM milestone and highlighted the AAA/A1+ rating affirmation from CRISIL and India Ratings — both consistent with the reported numbers; there was no commentary flagging margin pressure beyond the modest NPM drift evident in the statement itself.