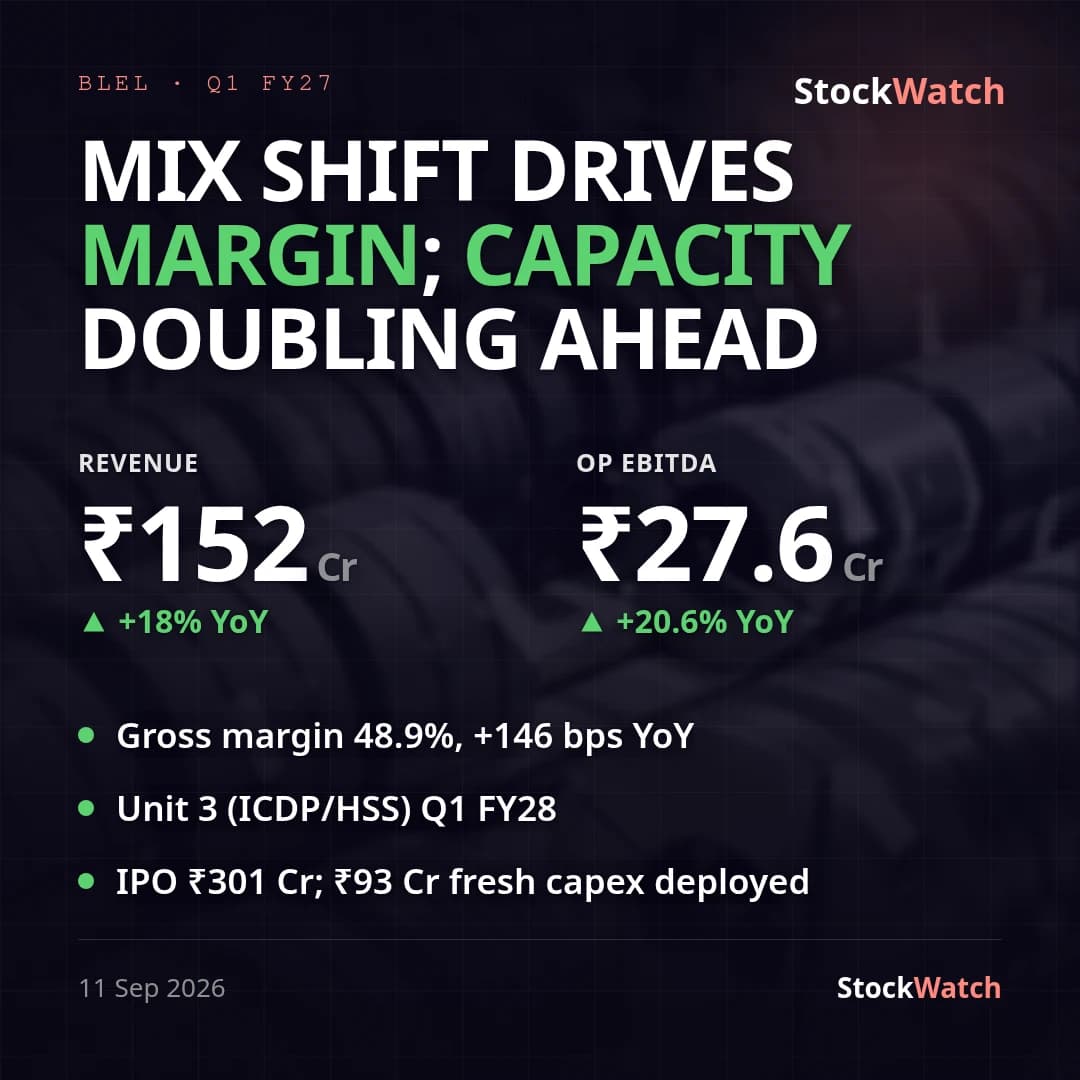
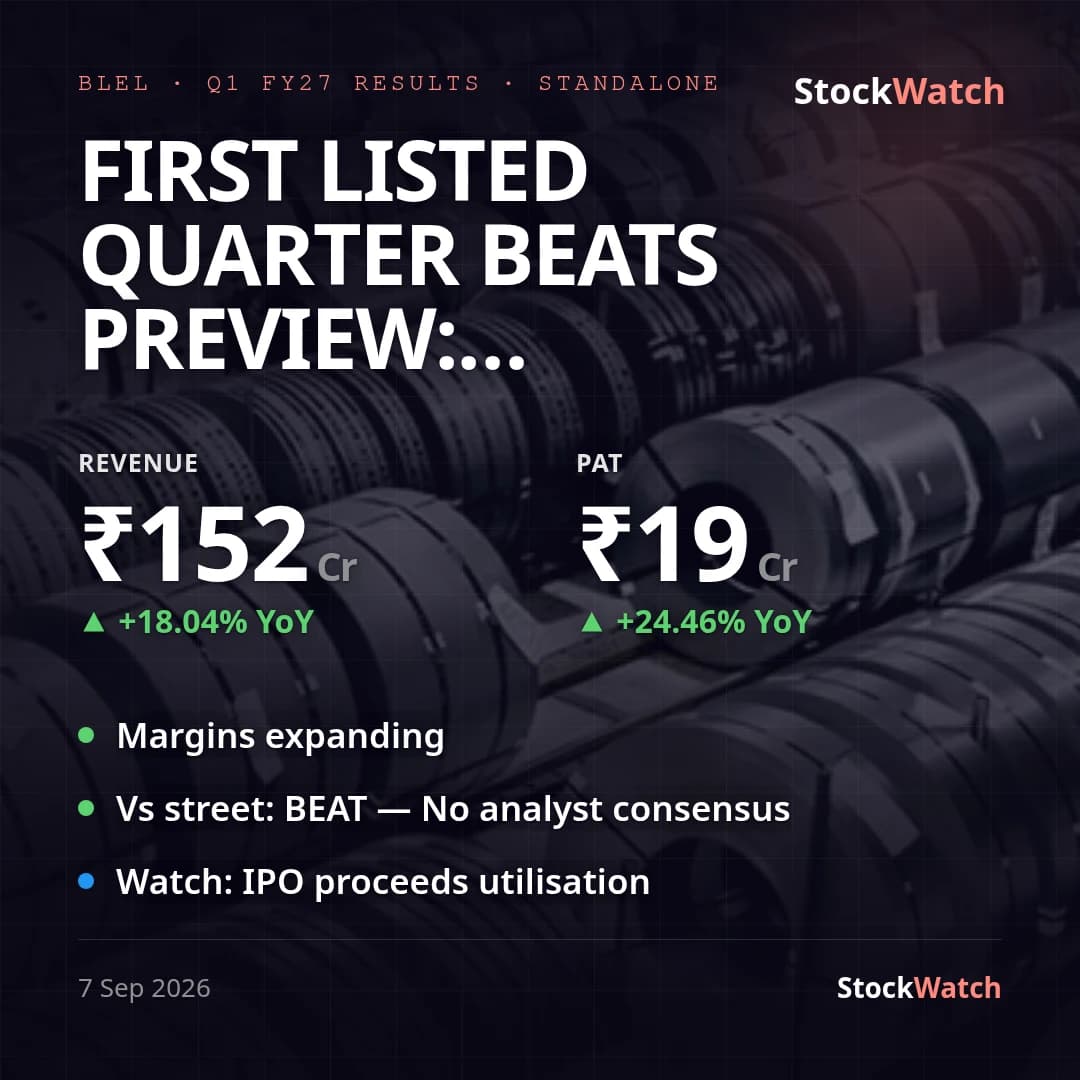
Behari Lal Engineering's maiden result as a listed company shows standalone revenue of ₹151.7 Cr (+18.0% YoY, +15.6% QoQ) and PAT of ₹19.2 Cr (+24.5% YoY), with no exceptional items on either side of the comparison. There is no formal management guidance on record and no established analyst consensus — our pre-result preview flagged "thin, forming" coverage post-IPO — but against our own on-plan expectations (revenue ₹130-140 Cr; PAT margin ~12%, i.e. ₹15.6-16.8 Cr) the company beat on both counts: revenue came in above the top of the range and PAT margin landed at 12.66% versus a ~12% target.
Core operating profitability actually improved on a clean basis: total expenses were 84.45% of revenue this quarter versus 84.67% a year ago and 85.35% in Q4 FY26 — the best of the three periods. The headline PAT dip of 10.3% QoQ (₹21.4 Cr to ₹19.2 Cr) is not an operating slowdown; it reflects Q4 FY26 carrying elevated other income (₹7.25 Cr versus ₹2.17 Cr this quarter) and an unusually low 19.2% effective tax rate (versus 25.5% now, 26.4% a year ago) from a deferred-tax credit. Strip those two items out and the underlying quarter is a continuation of the growth trend, not a reversal.
The quarter's corporate developments were mostly listing-related rather than operational: the company completed its IPO (fresh issue of 32,63,157 shares plus an OFS of 73,20,001 shares at ₹285) after the quarter closed, listing on NSE/BSE on August 19, 2026, and subsequently adopted a Fair Disclosure Code and authorised KMPs for disclosures ahead of its first results as a public company. The filing carries no management press release or commentary beyond the numbers, and gives no update yet on IPO-proceeds deployment — the company has explicitly deferred that disclosure to the next reporting period.