Bharat Forge swings to ₹90 Cr consolidated loss on ₹358 Cr German restructuring charge
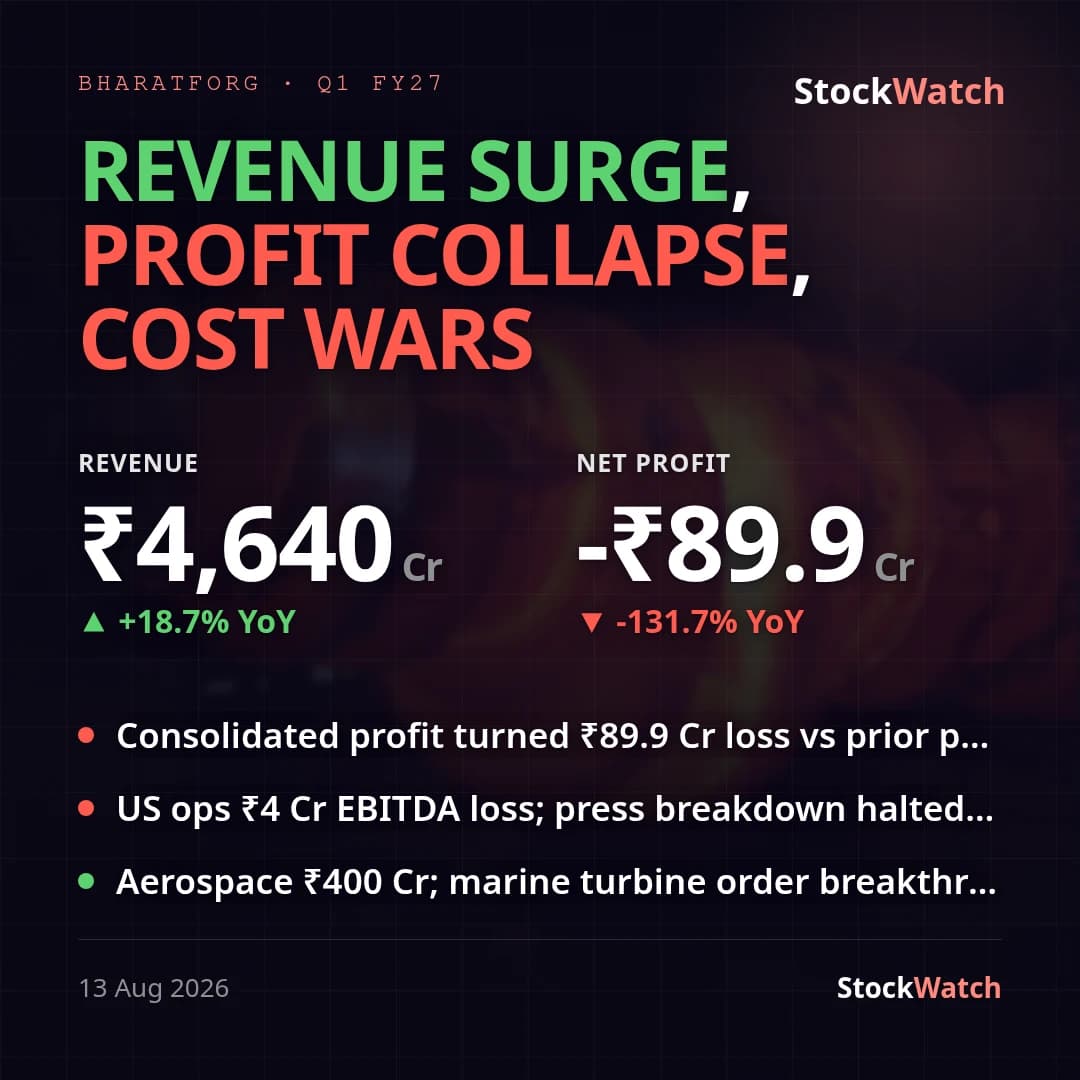
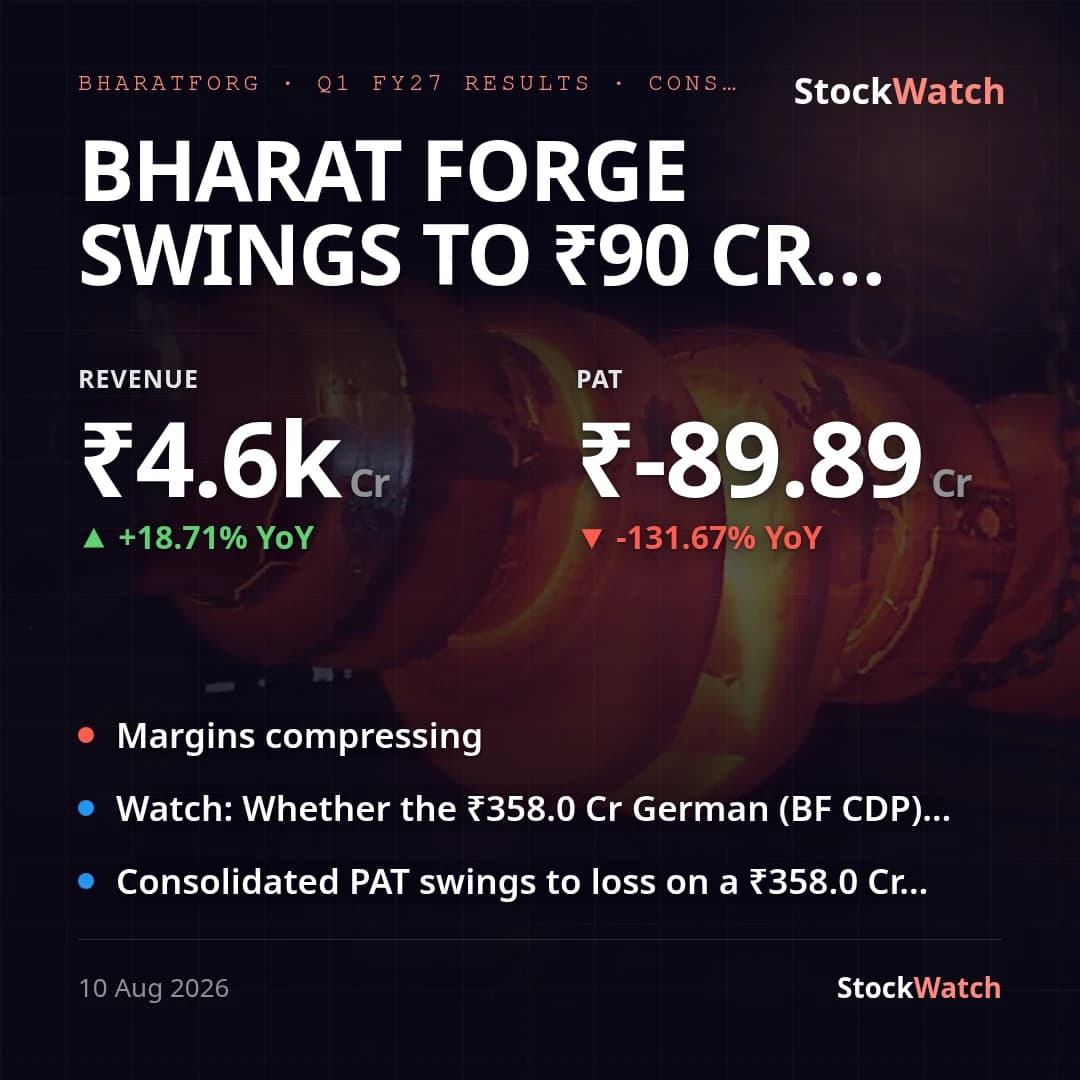
Bharat Forge's consolidated Q1 FY27 revenue rose to ₹4,639.9 Cr, up 18.7% YoY and 2.5% QoQ, but the consolidated bottom line swung to a loss of ₹89.9 Cr against profits of ₹283.9 Cr a year ago and ₹233.4 Cr last quarter. Consolidated EPS was -₹1.88 versus +₹5.93 YoY. Standalone (India-only) results stayed profitable — PAT ₹321.4 Cr on revenue ₹2,347.4 Cr, EPS ₹6.72 — so the loss is entirely a consolidation-level, Europe-driven event.
The swing is driven by a ₹358.0 Cr consolidated exceptional charge tied to the restructuring of German subsidiary Bharat Forge CDP GmbH: a ₹330.4 Cr provision for a social plan agreed with the Works Council, plus ₹26.7 Cr of incidental restructuring costs and a small VRS charge (note 3). Standalone carried a much smaller ₹24.5 Cr exceptional hit for the same items. Stripping the exceptional charge out, consolidated pre-exceptional PBT was ₹402.4 Cr, and adjusted PAT (pre-exceptional PBT less the reported tax charge) works out to roughly ₹268 Cr — down about 5.6% YoY and 19.3% QoQ. So even excluding the one-off, underlying profitability softened, not just the headline; operating margin compressed to 15.05% from 17.13% YoY and 17.17% QoQ, and net margin fell to -1.94% from 7.26% YoY purely on the exceptional charge.
This is the restructuring management had already flagged: on the May 2026 call it said it was "undertaking a strategic restructuring of its German steel forging business to improve consolidated profitability," delivered then in a confidently bullish tone. The charge materializing confirms that plan, though its size this quarter is a harder print than that framing implied. Segment-wise, growth is increasingly non-core: Defence revenue nearly doubled YoY to ₹495.7 Cr (from ₹264.4 Cr) and "Others" revenue rose to ₹627.9 Cr (from ₹279.0 Cr), while core Forgings grew a more modest 7.7% YoY to ₹3,831.1 Cr. Alongside results, the board approved raising up to ₹2,500 Cr via equity/debt instruments, incorporating a Malaysia subsidiary for semiconductor-related work, a 90% stake buy in RS Aerostructures (₹3.6 Cr) and a 30% stake in Fortuna Engineering (₹129.6 Cr, connecting rods/camshafts) — all consistent with the guided aerospace/defence push and complementary M&A. Separately, Kalyani Powertrain agreed to exit its loss-making JV stake in REFU Drive GmbH for a nominal EUR 12,500. No reliable brokerage consensus for this specific quarter could be confirmed via search, so the print's standing versus Street is unknown.
On management's own guidance, standalone (India) revenue grew only 11.5% YoY (₹2,347.4 Cr vs ₹2,104.7 Cr) — well short of the ~25% FY27 India revenue growth guided in May 2026 — so this quarter is tracking behind that full-year pace, one quarter in. Whether growth accelerates through FY27, backed by the ₹800-850 Cr capex program, and whether the German restructuring provision proves to be a one-time hit rather than the first of several, are the two threads to watch into Q2.