StockWatch
·

Bombay Super Hybrid Seeds Ltd

BSE: 544757

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27
Revenue
85.96
-53.0%
Expenditure
83.01
-50.5%
Net Profit
2.36
-83.5%
OPM %
4.96%
-4.43pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.0051.26102.52153.78205.04Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

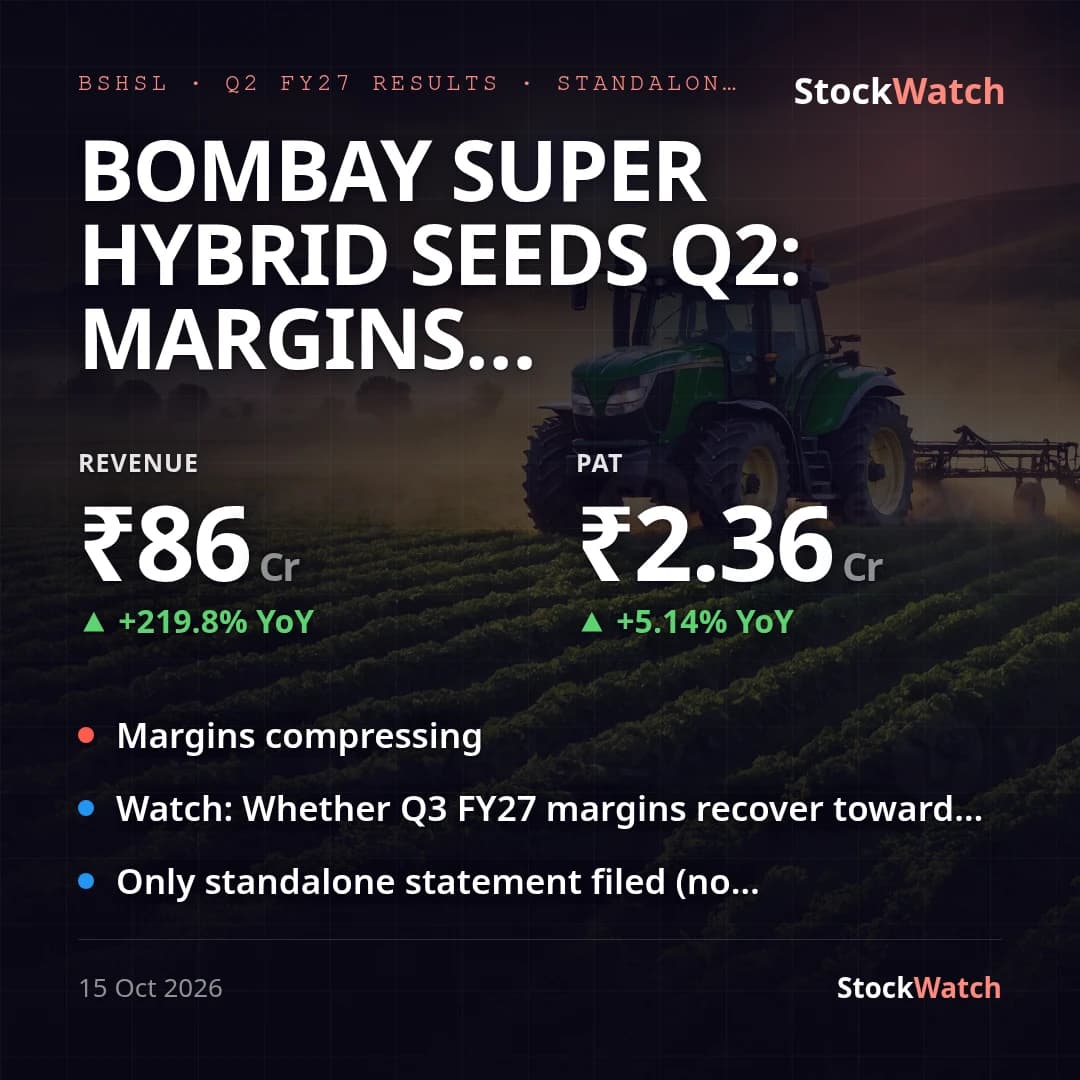
Bombay Super Hybrid Seeds Q2: margins compress sharply, PAT growth of 5% lags revenue surge

hybrid seeds · agri inputs · margin compression

ResultsQ2 FY2715 Oct 20263 min

Bombay Super Hybrid Seeds Q1 FY27: PAT up 17% YoY to ₹14.3 Cr, margins dip

agri seeds · kharif season · standalone results

ResultsQ1 FY2707 Aug 20263 min
Latest
Board Meeting15 Oct, 6:20 pm

Bombay Super Hybrid Seeds Q2: margins compress sharply, PAT growth of 5% lags revenue surge

Bombay Super Hybrid Seeds' standalone revenue rose 219.8% YoY to ₹85.86 Cr in Q2 FY27 (vs ₹26.85 Cr in Q2 FY26), but standalone PAT grew just 5.1% YoY to ₹2.36 Cr (vs ₹2.24 Cr) — net profit margin fell to 2.75% from 8.36%, and EBITDA-level margin (PBT + finance cost + depreciation ÷ revenue) fell to roughly 4.6% from ~15.6% a year ago. Sequentially, revenue fell 52.97% and PAT fell 83.5% from Q1 FY27 (revenue ₹182.57 Cr, PAT ₹14.30 Cr); this QoQ drop is treated as a seasonality artifact of the hybrid-seed business, where sales concentrate ahead of the kharif sowing window in Q1, rather than as fresh weakness — the YoY comparison is the one that matters here. The gap between the 220% YoY revenue jump and the 5% PAT growth shows the incremental volume carried very thin margin this quarter: total expenses rose to ₹83.01 Cr from ₹24.49 Cr a year ago, driven by purchases/production costs and the change-in-inventories line scaling roughly in step with the higher sales base, while employee costs and depreciation rose only modestly and finance costs stayed close to last year's level. There is no exceptional item on either side of the YoY comparison, so the margin compression is read as operating, not accounting. There is no analyst coverage or consensus estimate for this stock (confirmed via search), so no beat/miss call versus street can be made, and the company has no formal guidance on record in our context or found via search, so management's own bar cannot be checked either. No results press release was available for this filing to cross-check management's framing. The quarter's other disclosed developments — a ₹3.68 Cr Indore property acquisition in August and the FY26 annual report submission/AGM approvals through September-October — are governance and capacity items that have not yet shown up in this quarter's P&L. H1 FY27 PAT of ₹16.66 Cr (on revenue of ₹269.04 Cr) is already about 62.5% of full-year FY26 PAT (₹26.66 Cr), so the second half will determine whether the full year tracks ahead of FY26 despite the Q2 margin squeeze.

15 Oct 2026, 06:20 pm

Quarterly Result7 Aug, 1:14 pm

Bombay Super Hybrid Seeds Q1 FY27: PAT up 17% YoY to ₹14.3 Cr, margins dip

Bombay Super Hybrid Seeds reported standalone Q1 FY27 revenue of ₹182.57 Cr, up 19.4% YoY from ₹152.94 Cr, with net profit of ₹14.30 Cr, up 16.6% YoY from ₹12.27 Cr. The quarter carries no exceptional or prior-period items on either side of the comparison, so the YoY read is clean. Sequentially, revenue jumped 175% and PAT more than tripled over Q4 FY26 (₹66.43 Cr revenue, ₹4.41 Cr PAT) — this QoQ swing is a seasonality artifact typical of the kharif sowing cycle (April-June) for an agri hybrid-seeds business, not a trend signal, and should not be read as sequential momentum. Profitability softened marginally YoY: net margin (PAT/total income) was 7.81% versus 8.01% a year ago, and operating margin (revenue less production, inventory, employee and other opex, before finance cost/depreciation) was 9.39% versus 10.04% YoY — roughly 20bps and 65bps of compression, driven by higher purchase/production costs and inventory movement relative to revenue. PAT growth (16.6%) actually outpaced PBT growth (15.7% YoY) only because the effective tax rate eased to 6.2% of PBT from 7.0% a year ago. There is no analyst consensus or brokerage preview available for this micro-cap (BSE 544757, NSE BSHSL), so the print cannot be judged against Street expectations, and the company has issued no formal guidance or outlook on record, so vs-guidance is also unknown rather than met or missed. Management's only other disclosure this quarter was the June 2026 announcement of a ₹1.40 Cr land purchase for expansion at its Rajkot facility — too small to move this quarter's numbers but a marker to watch for future capacity. No press release accompanied the results; the filing is limited to the SEBI-mandated financial statement and board-meeting outcome letter.

7 Aug 2026, 01:14 pm

Corporate Events

Board MeetingBSHSL
2026
15Oct

Board Meeting

The meeting of the Board of Directors will be held to consid…

BSE Filing ↗
Board MeetingBSHSL
2026
30Sep

Board Meeting

The company is submitting the Annual Report for the Financia…

BSE Filing ↗
Board MeetingBSHSL
2026
7Aug

Board Meeting

Board meeting to consider and approve the Unaudited Standalo…

BSE Filing ↗
Board MeetingBSHSL
2026
25May

Board Meeting

The board meeting is scheduled to consider and approve the A…

BSE Filing ↗