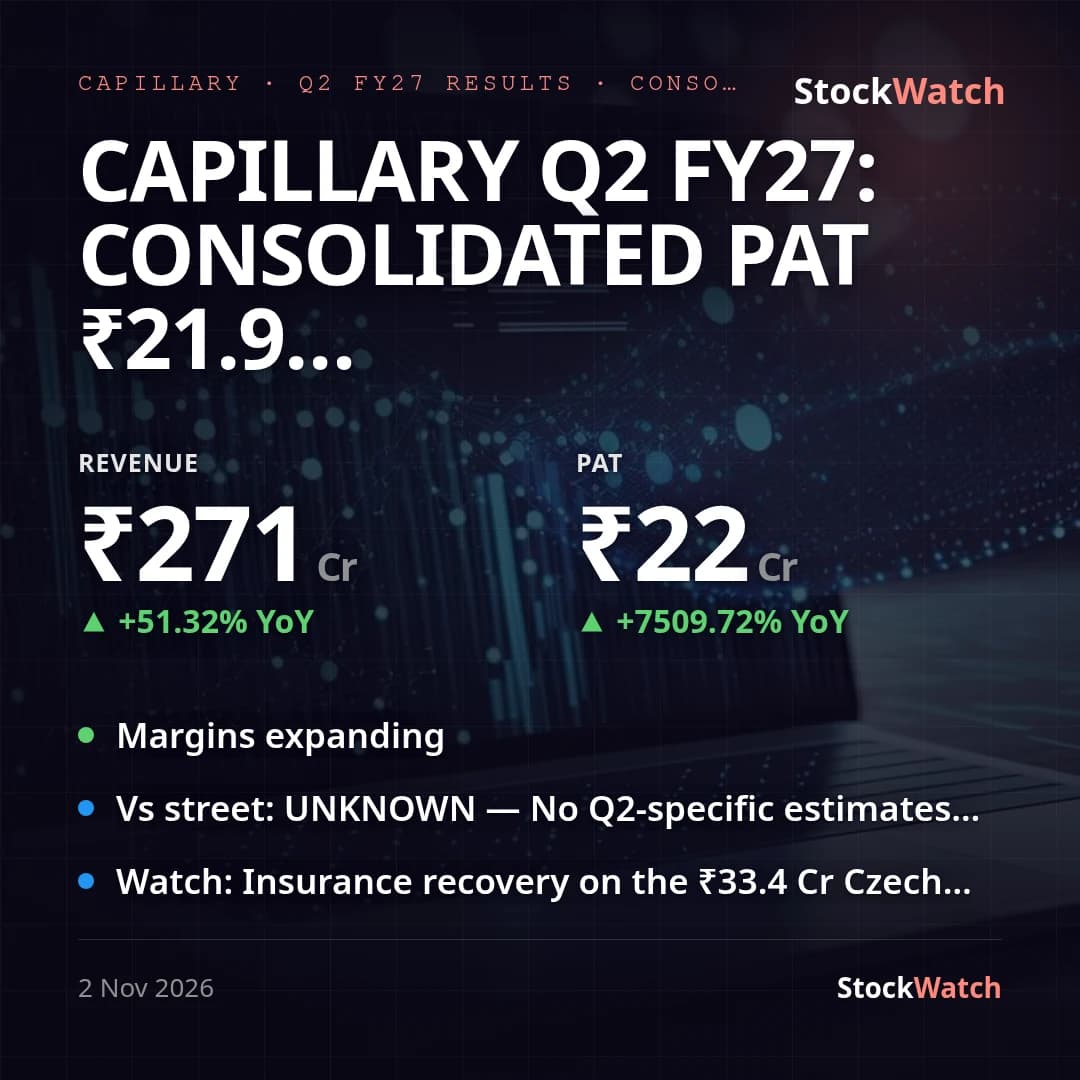
On a consolidated basis — the primary read for Capillary, since standalone excludes its international SaaS subsidiaries — Q2 FY27 revenue from operations rose 51.3% YoY to ₹271.4 Cr (₹179.3 Cr a year ago) and 5.7% QoQ (₹256.6 Cr in Q1 FY27). Consolidated PAT was ₹21.9 Cr, against a ₹9.6 Cr loss in Q1 FY27 and a near-breakeven ₹0.29 Cr a year ago. The YoY PAT comparison is off a near-zero base, so the raw percentage change (over 7,000%) isn't a meaningful number on its own; the useful read is that consolidated net margin moved to a solid 7.9% this quarter from effectively nil a year ago and from -3.6% last quarter.
The swing from last quarter's loss is largely the reversal of a one-off: Q1 FY27 carried a ₹33.4 Cr exceptional charge tied to a cyber-enabled banking fraud at the company's Czech subsidiary, which Q2 FY27 does not repeat. Stripping that out, Q1 FY27's underlying PAT was closer to ₹23-24 Cr, so the sequential improvement in operating profitability is modest, not dramatic. EBITDA (profit before finance costs, depreciation, amortisation and tax) was ₹45.5 Cr, a 16.8% margin on revenue — up from 11.6% a year ago but down from 17.9% in Q1 FY27, as consolidated D&A rose to ₹24.5 Cr (vs ₹11.2 Cr standalone) on purchase-price-allocation amortisation from the SessionM and Kognitiv Solutions acquisitions. That same subsidiary amortisation is why standalone PAT (₹29.4 Cr) came in above consolidated PAT (₹21.9 Cr) this quarter — a divergence investors should read off the consolidated number.
Against management's own guidance (FY27 revenue of ₹1,065 Cr and EBITDA of ₹172 Cr, reiterated at the Q1 FY27 call with management saying it expects to beat without formally revising), H1 FY27 consolidated revenue of ₹539.8 Cr is already 50.7% of the full-year target and H1 EBITDA of ₹91.5 Cr is 53.2% of the EBITDA target — both tracking on pace. We found no Q2-FY27-specific Street estimates (results were filed same-day as this review); FY27 consensus tracked by Trendlyne/sharpely runs around ₹1,050 Cr revenue, broadly in line with guidance. The 17-23% organic growth management guided for FY27 can't be isolated from this filing's 51.3% reported YoY growth, which includes a full quarter of SessionM/Kognitiv contribution versus a partial one a year ago. Separately, the Board used this meeting to replace Protiviti with Deloitte Touche Tohmatsu India LLP as internal auditor effective November 2, 2026, citing the growing scale of overseas operations, finalised SessionM/Kognitiv purchase price allocation during the quarter, and named Bill Swift President-Americas in late October.
Going into Q3 FY27, the headline swing to profit is mostly a one-off reversal rather than a step-change in operating performance, even as YoY revenue growth and margin expansion are genuine. The Czech subsidiary fraud matter remains under investigation with an insurance claim pending and no further financial impact recognised this quarter.