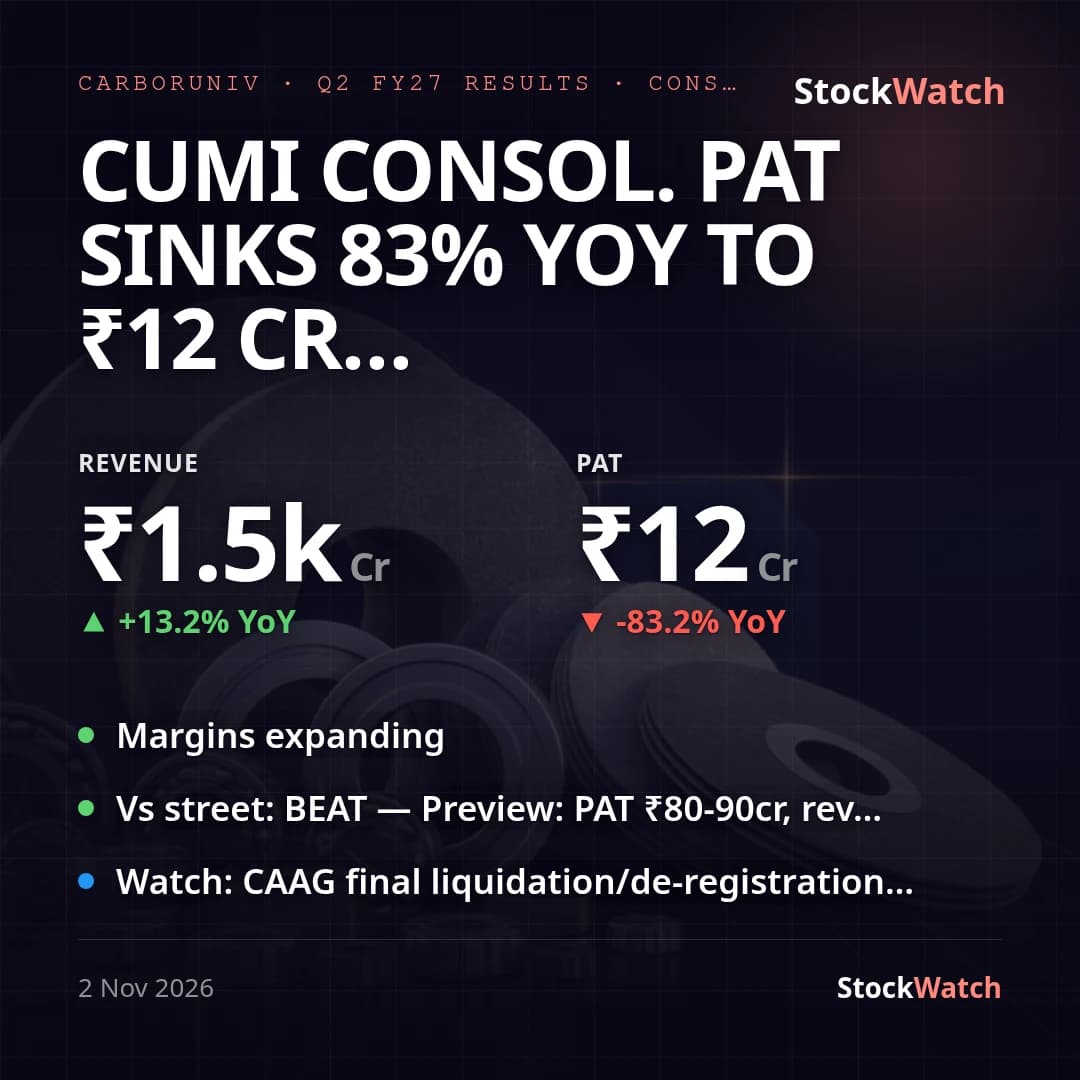
CUMI Consol. PAT Sinks 83% YoY to ₹12 Cr on CAAG One-off; Adjusted Profit Up ~25%
Carborundum Universal's consolidated PAT (owners' share) fell 83.2% YoY to ₹12.45 Cr from ₹74.26 Cr in Q2FY26, and 84.5% QoQ from ₹80.34 Cr in Q1FY27 — but the headline crash is almost entirely a single one-off, not an operating problem. The company recognised an ₹80.26 Cr exceptional charge this quarter for winding down its German step-down subsidiary CUMI Awuko Abrasives GmbH (CAAG): in October 2026 CAAG sold its plant, equipment and inventory for ₹5.34 Cr and settled a reconciliation-of-interest/social plan with employees under German labour law, triggering the write-down. Strip that out and adjusted PAT was ₹92.7 Cr, up ~24.8% YoY and ~15.4% QoQ — management states this explicitly in its press release, and the arithmetic ties out (₹58.02 Cr PBT + ₹80.26 Cr add-back ≈ ₹138.28 Cr pre-exceptional PBT, matching the release's ₹138 Cr figure). Revenue grew a cleaner 13.2% YoY to ₹1,469 Cr (₹1,298 Cr), landing exactly inside the ₹1,450–1,480 Cr range our pre-result preview flagged as the Street's working estimate.
The margin story underneath is actually positive: EBITDA margin expanded to ~12.5% from 12.1% a year ago and a sharply lower 9.5% in Q1FY27, with Ceramics doing the heavy lifting — consolidated Ceramics sales jumped 36.1% YoY to ₹410 Cr and segment PBIT grew 62.1% YoY, well ahead of the 23-25% FY27 growth guidance management had just raised off the back of Q1's strength. Electrominerals also beat its guided 9-10% range, growing consolidated sales 11.1% YoY to ₹443 Cr. Abrasives was the laggard, up just 4.0% YoY to ₹607 Cr on broadly flat sequential sales, pulling blended consolidated growth (13.1-13.2%) a touch below the ~15% overall guidance management had reiterated — on balance this reads as guidance met rather than clearly beaten, since the shortfall traces to one segment rather than broad execution.
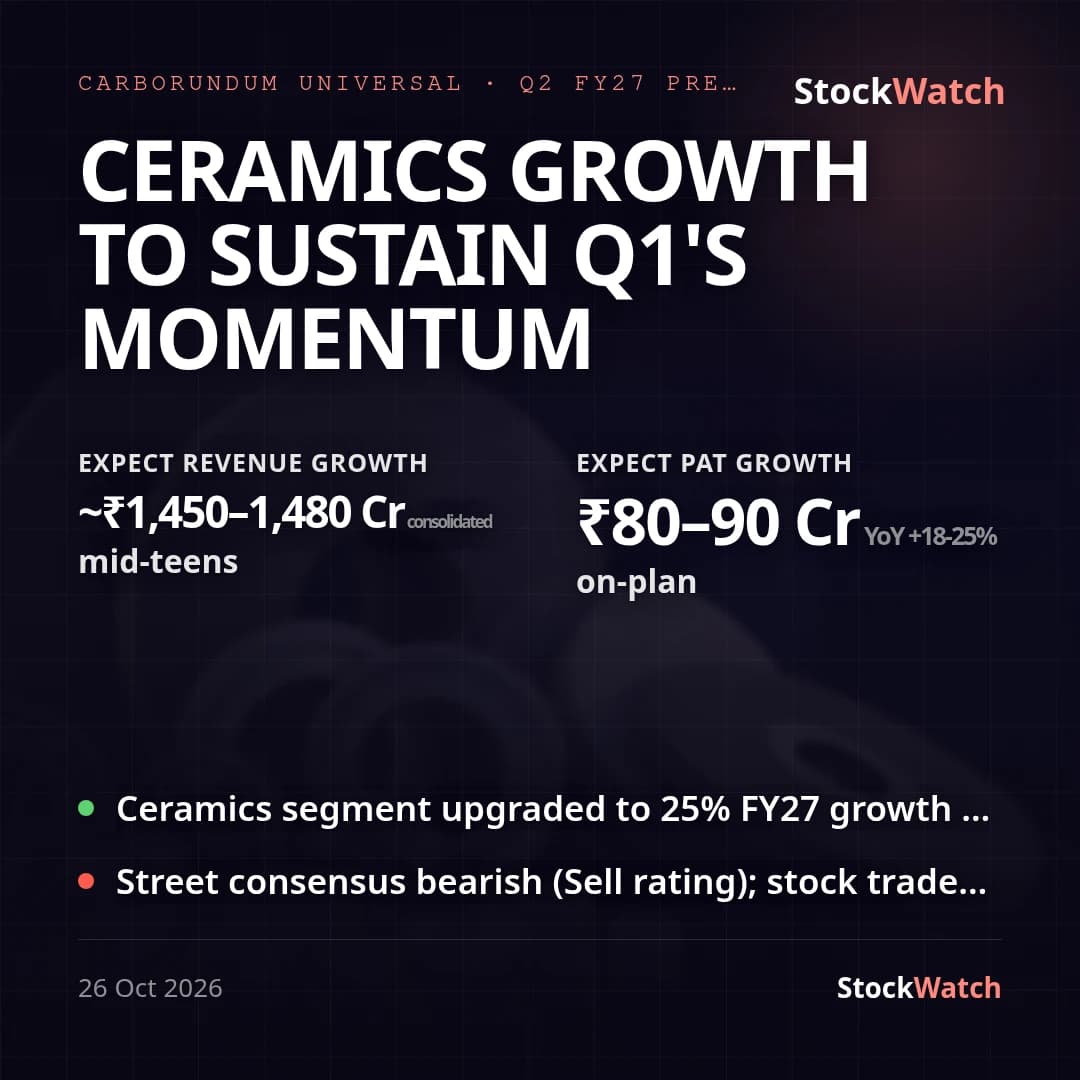
Our pre-result preview flagged that Street consensus (7 analysts, zero Buy ratings, median target ₹964.50 implying 11% downside) was skeptical of the stock's 82x PE and worried any stumble would trigger repricing; this print is a mixed test of that thesis — revenue and adjusted profit both land in-line-to-ahead of the ₹80-90 Cr PAT range the preview cited, but the reported headline miss (₹12.45 Cr) is exactly the kind of noisy print that thin, bearish coverage could misread without parsing the CAAG note. The quarter's other developments were largely incidental to the print: CUMI appointed Sriram Seshadri as CFO & KMP (Sep 7) and CUMI invested $3M in a Cyprus subsidiary (Sep 30) — Cyprus being where CIL, the holding company that approved CAAG's closure, is based, so that infusion plausibly relates to funding the wind-down; several ESG ratings during the quarter carry no financial bearing.
With CAAG's asset sales and employee settlement now complete and only final liquidation/de-registration left, management does not flag further exceptional charges from this entity — cumulative CAAG-related charges now total ~₹19.9 Cr (₹11.9 Cr in FY26 plus ₹8.0 Cr this quarter). The next test is whether Ceramics can sustain its 36%+ pace against a 23-25% guided bar while Abrasives recovers from its 4% YoY trough, against a consolidated net debt position of ₹111 Cr (₹362 Cr debt, ₹251 Cr cash ex-VAW) and H1FY27 capex of ₹127 Cr running below the ₹400 Cr full-year plan.