Chemplast Sanmar Q1 FY27: consolidated loss widens to ₹175.6 Cr on PVC import dumping
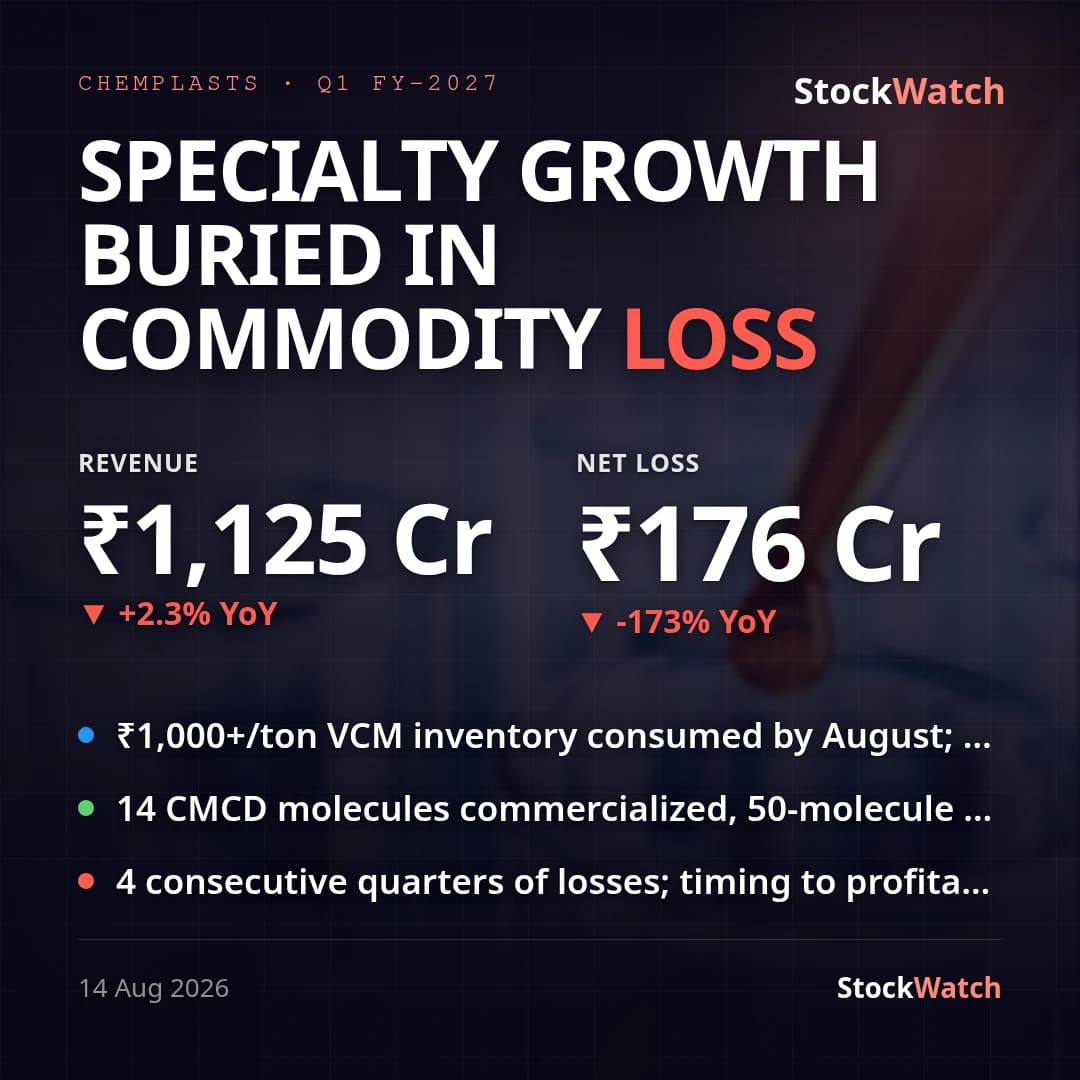
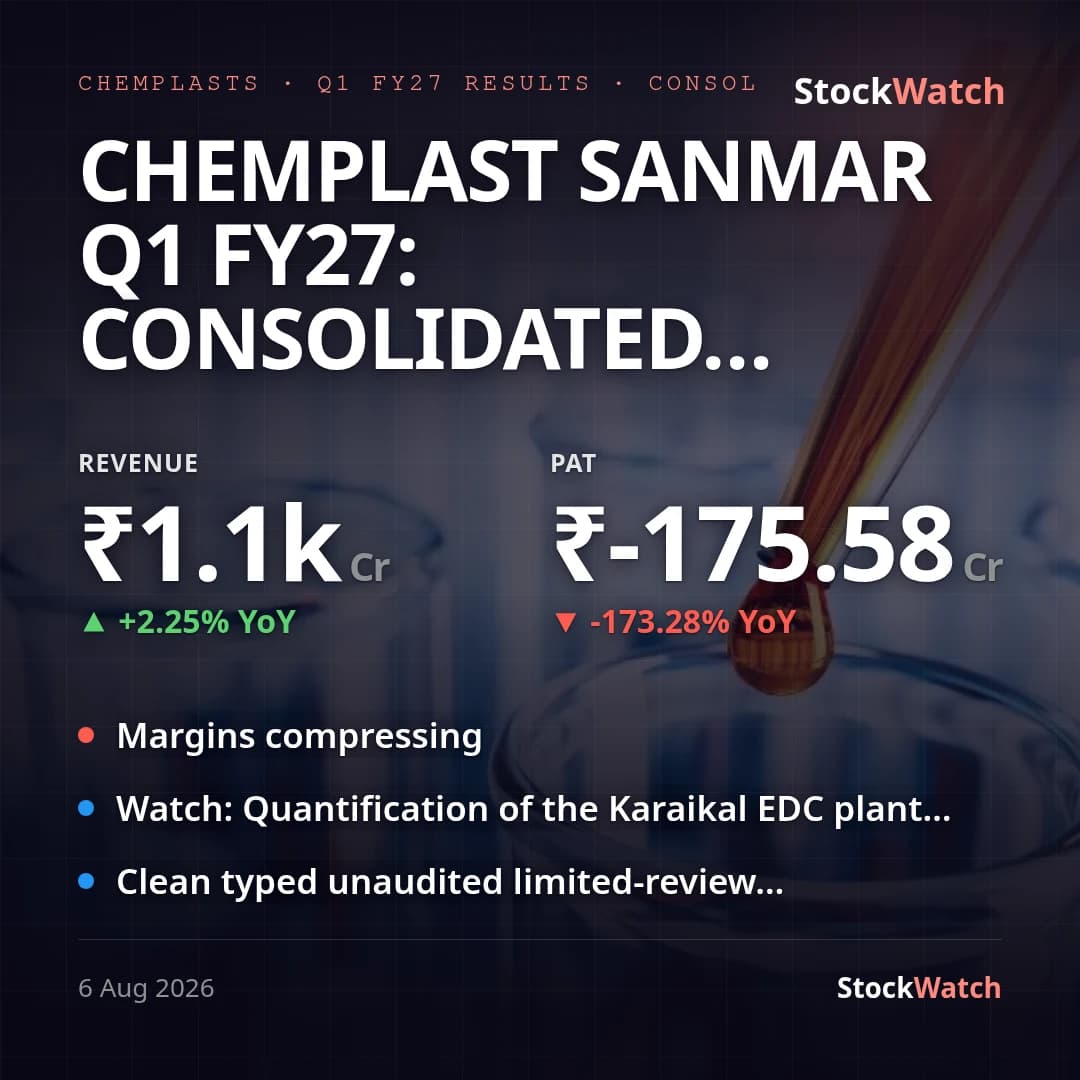
Consolidated revenue came in at ₹1,124.66 Cr, up a modest 2.3% YoY but down 10.4% QoQ (seasonal step-down from Q4). The bottom line deteriorated sharply: net loss widened to ₹175.58 Cr from a ₹64.25 Cr loss a year ago and a ₹45.38 Cr loss last quarter — the loss more than doubled YoY and nearly quadrupled QoQ. Net margin fell to -15.6% from -5.8% YoY and -3.6% QoQ. Consolidated EPS loss was ₹11.10 versus ₹4.02 a year earlier. Standalone (largely the Specialty Chemicals business) posted revenue of ₹592.32 Cr and a net loss of ₹49.29 Cr.
Segment data pins the deterioration on the Commodity (S-PVC, via subsidiary CCVL) business, where the loss ballooned to ₹166.40 Cr from ₹47.99 Cr a year ago. Company notes attribute this to the non-notification (effective dropping) of an expected anti-dumping duty on S-PVC, removal of customs duty on S-PVC imports, the resulting price crush from low-cost imports, and raw-material volatility tied to the West Asia crisis. Specialty Chemicals — the segment management had guided toward "stronger performance" on the Q4 FY26 call — instead swung the wrong way, with the loss widening to ₹65.57 Cr from ₹38.20 Cr YoY, a clear miss against that specific guidance. Notably, Q1 FY27 carries zero exceptional items, whereas Q4 FY26's smaller headline loss (₹45.38 Cr) was struck after a ₹149.92 Cr CCVL onerous-contract exceptional charge — pre-exceptional Q4 PBT was actually a positive ₹88.90 Cr. On a clean, like-for-like basis, Q1 FY27's operating loss therefore represents a genuine sequential deterioration, not one flattered by an easier one-off-laden comparison.
No quarter-specific Street consensus for Q1 FY27 could be located (only broad FY27 full-year revenue/EPS estimates turned up in search, not previews for this print), so vsStreet is marked unknown. Management's prior guidance called the commodity environment "volatile" — borne out this quarter — while separately expecting specialty to benefit from "better fundamentals"; that specific call did not hold. Subsequent to quarter-end, a fire disrupted the Karaikal EDC plant (18 Jul 2026) and pollution-control authorities briefly prohibited operations there (20-23 Jul); the company states the financial impact "cannot be determined at this stage" and has notified its insurer — an added watch item layered on top of the ongoing PVC pricing pressure.