StockWatch
·

Corona Remedies Ltd

BSE: 544644

P/L Snapshot

Q1 FY27 · standalone

vs Q4 FY26
Revenue
425.58
+19.1%
Expenditure
345.23
+14.0%
Net Profit
60.10
+33.4%
OPM %
22.05%
+4.49pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.00119.16238.32357.49476.65Q2 FY26Q3 FY26Q4 FY26Q1 FY27
Price Chart
Reports

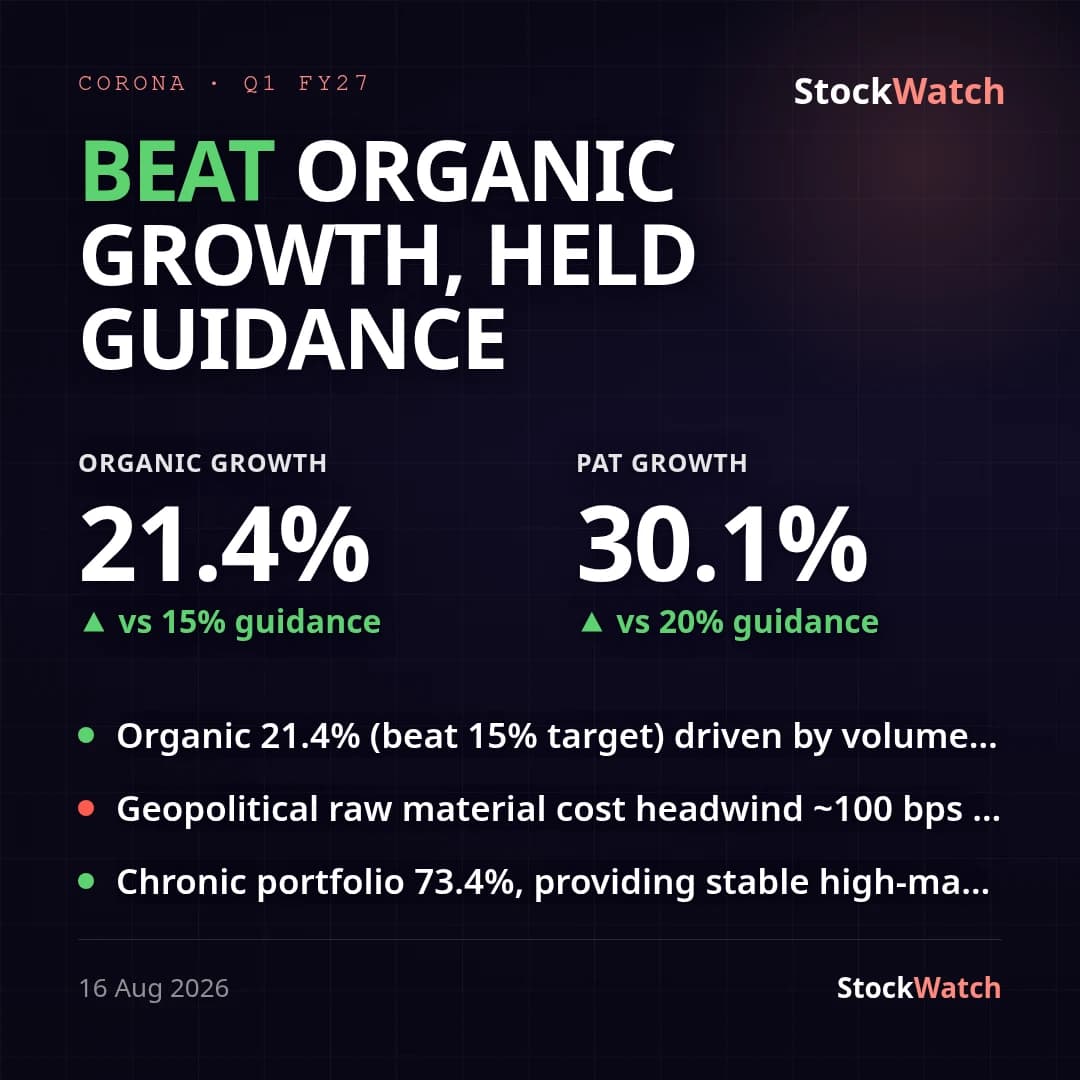
Beat Organic Growth, Held Guidance: The Cost Headwind Hidden in a Strong Quarter

organic growth beat · margin sustainability · geopolitical cost inflation
Result verdictFollow-upQ1 FY2716 Aug 20266 min

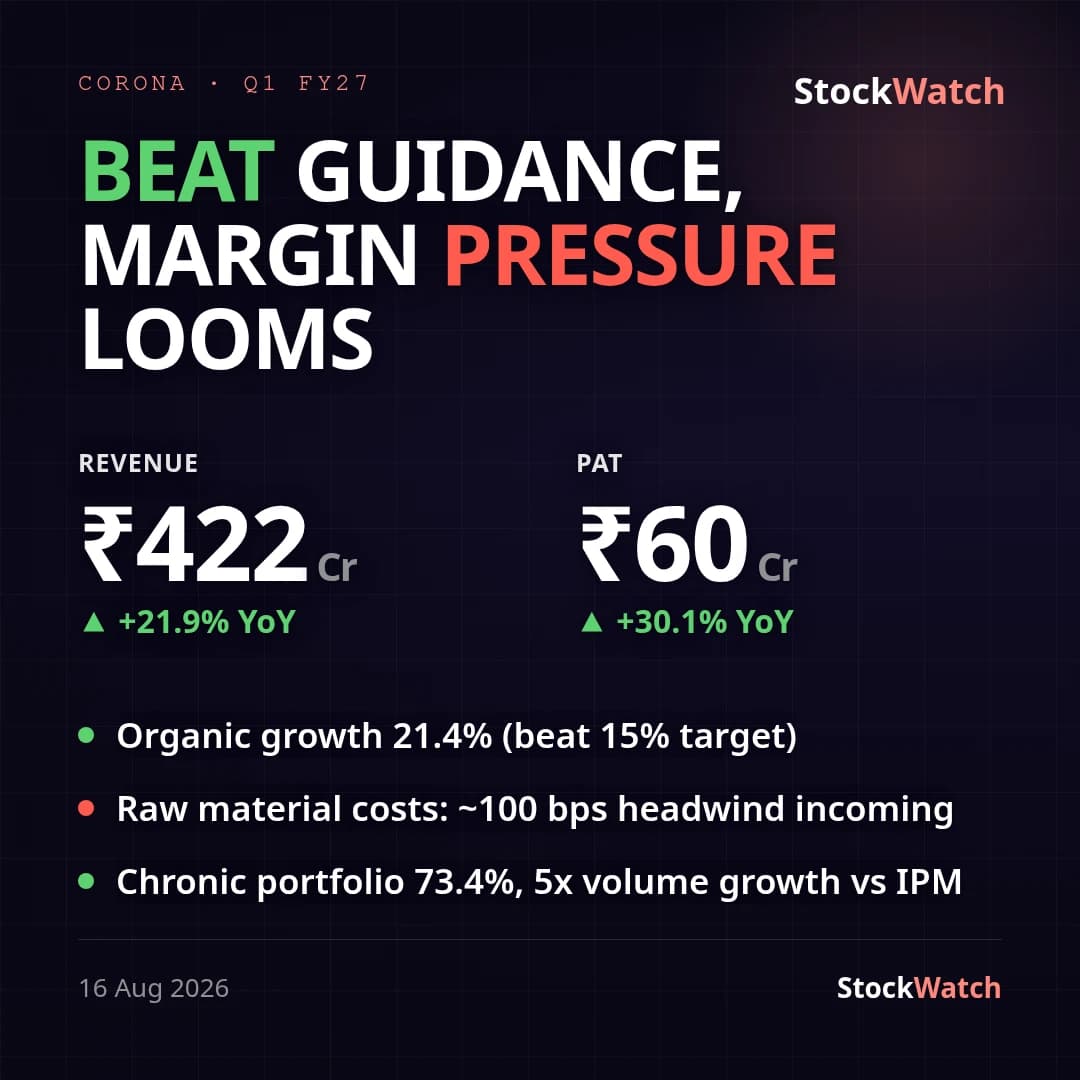
Beat Q1 but margin headwinds ahead; guidance unchanged

chronic portfolio strength · volume growth 5x IPM · margin pressure (geo-cost)
TranscriptDeep diveQ1 FY2716 Aug 20266 min

Corona Remedies Q1: consolidated PAT +30% YoY to ₹60 Cr, revenue up 22%, margins expand

pharmaceuticals · revenue growth · margin expansion

ResultsQ1 FY2731 Jul 20263 min
Latest
Board Meeting31 Jul, 5:30 pm

Corona Remedies Q1: consolidated PAT +30% YoY to ₹60 Cr, revenue up 22%, margins expand

Corona Remedies opened FY27 with a clean growth print: consolidated revenue rose 21.9% YoY to ₹422.4 Cr and net profit climbed 30.1% YoY to ₹60.1 Cr (₹46.2 Cr a year ago), with net margin widening ~90 bps to 14.2%. Profit outgrew revenue with no help from one-offs — neither the current nor year-ago quarter carries an exceptional item, so the reported +30.1% is also the underlying figure. Standalone tells the same story (PAT ₹60.1 Cr); the consolidated line differs by just ₹0.01 Cr of associate profit, so the two bases are effectively identical here. The margin expansion is operating-led. Management's disclosed EBITDA rose 33.5% to ₹93.1 Cr with EBITDA margin up 190 bps YoY to 22.0%, driven by brand-building and operational leverage: revenue grew faster than employee costs (₹122.1 Cr, +25%) and other expenses (₹129.7 Cr, +14%), while cost of materials stayed contained. Sequentially the print looks even stronger — revenue +19.6% and PAT +32.6% over Q4 FY26's ₹353.1 Cr / ₹45.3 Cr — but Q4 was a soft base, so YoY is the cleaner read. The board declared the results 31 July; the earnings call is set for 3 August. Against the bar, this is a beat-to-meet. Management's FY27 guidance from the Q4 concall was >15% organic revenue growth and >20% PAT growth; Q1 delivered 21.9% and 30.1%, comfortably ahead on both. Street context was thin for this December-2025 IPO — Univest's preview pegged Q1 PAT in a ₹58–74 Cr range, and the actual ₹60.1 Cr lands in the lower-middle of it, so inline rather than a blowout. Operationally, management flags Corona as the fastest-growing among IPM's top-30 for six straight months, rank up three places to 26th (MAT June'26), and 5th in Gynaecology. The quarter also saw commercialisation of the EU-GMP female hormone facility (30 June) and the start of Wokadine integration — both feeding the chronic/women's-health focus that underpins the guidance.

31 Jul 2026, 05:30 pm

Corporate Events

Board MeetingCORONA
2026
31Jul

Board Meeting

The meeting of the Board of Directors is scheduled to consid…

BSE Filing ↗
Board MeetingCORONA
2026
9Jul

Board Meeting

The 22nd Annual General Meeting (AGM) of the Company is sche…

BSE Filing ↗
Board MeetingCORONA
2026
9Jul

Board Meeting

The 22nd Annual General Meeting (AGM) of the Company is sche…

BSE Filing ↗
Board MeetingCORONA
2026
30Jun

Board Meeting

The Board approved the unaudited standalone and consolidated…

BSE Filing ↗