Credo Brands Q1 FY27: PAT falls 64% YoY as margins compress despite 4% revenue growth
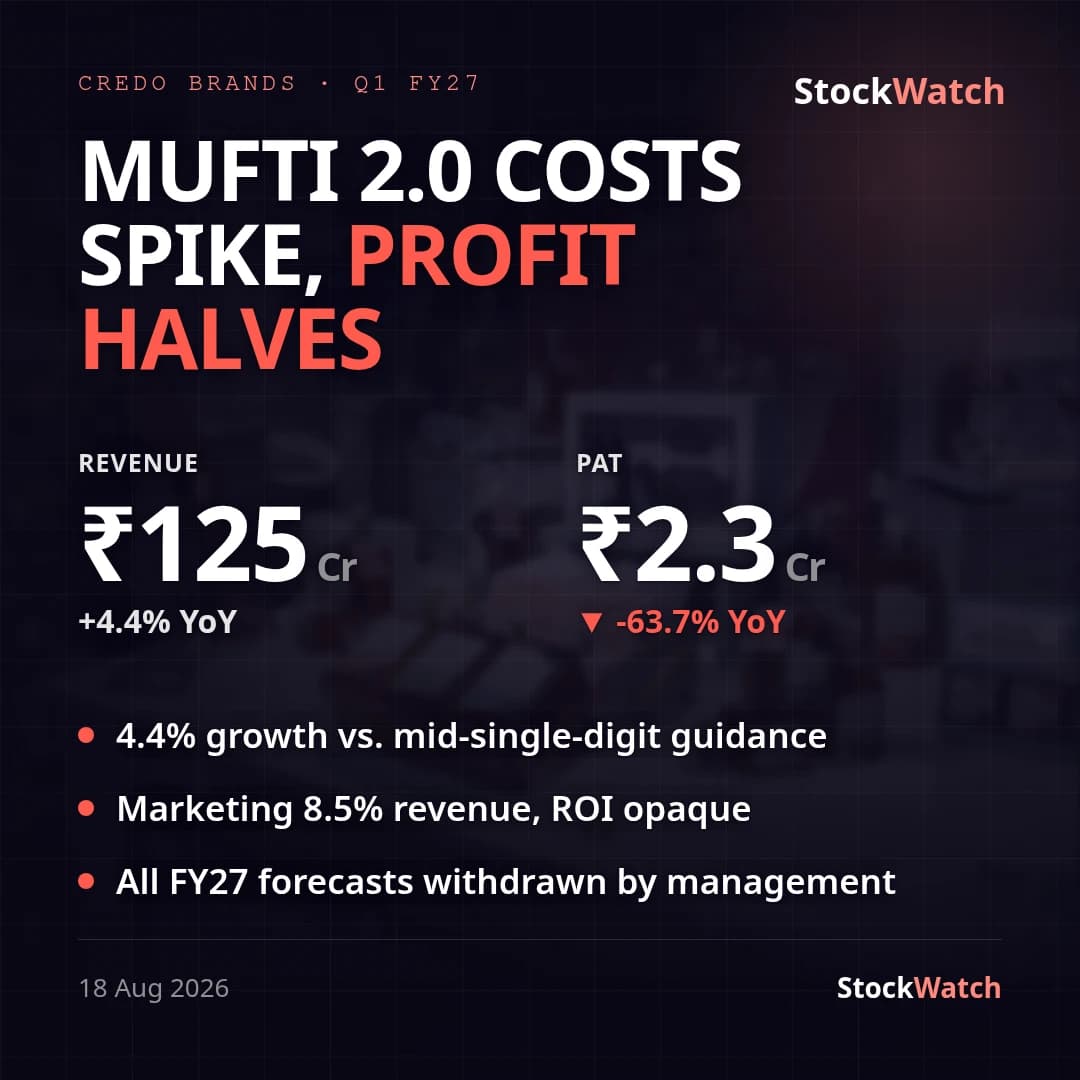
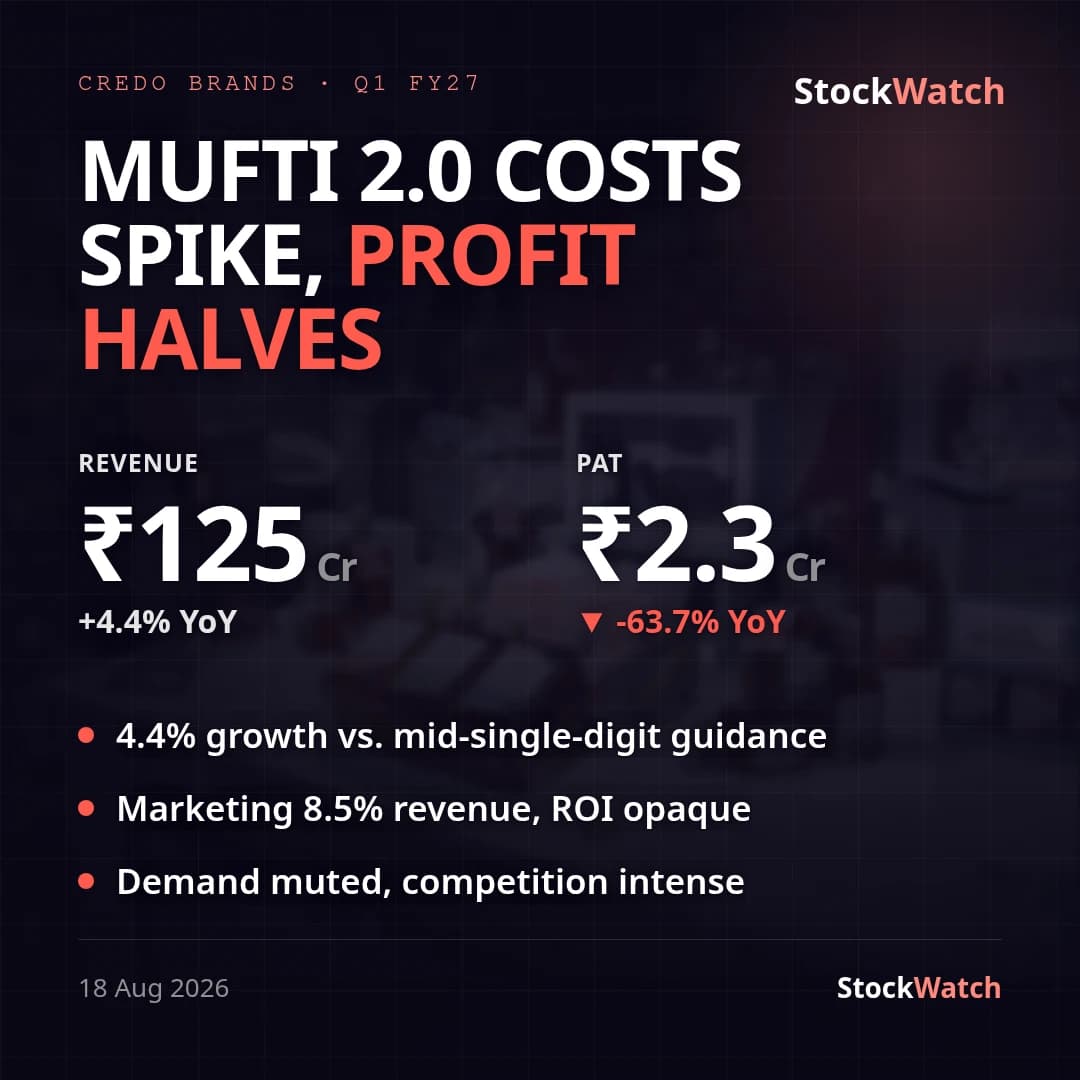
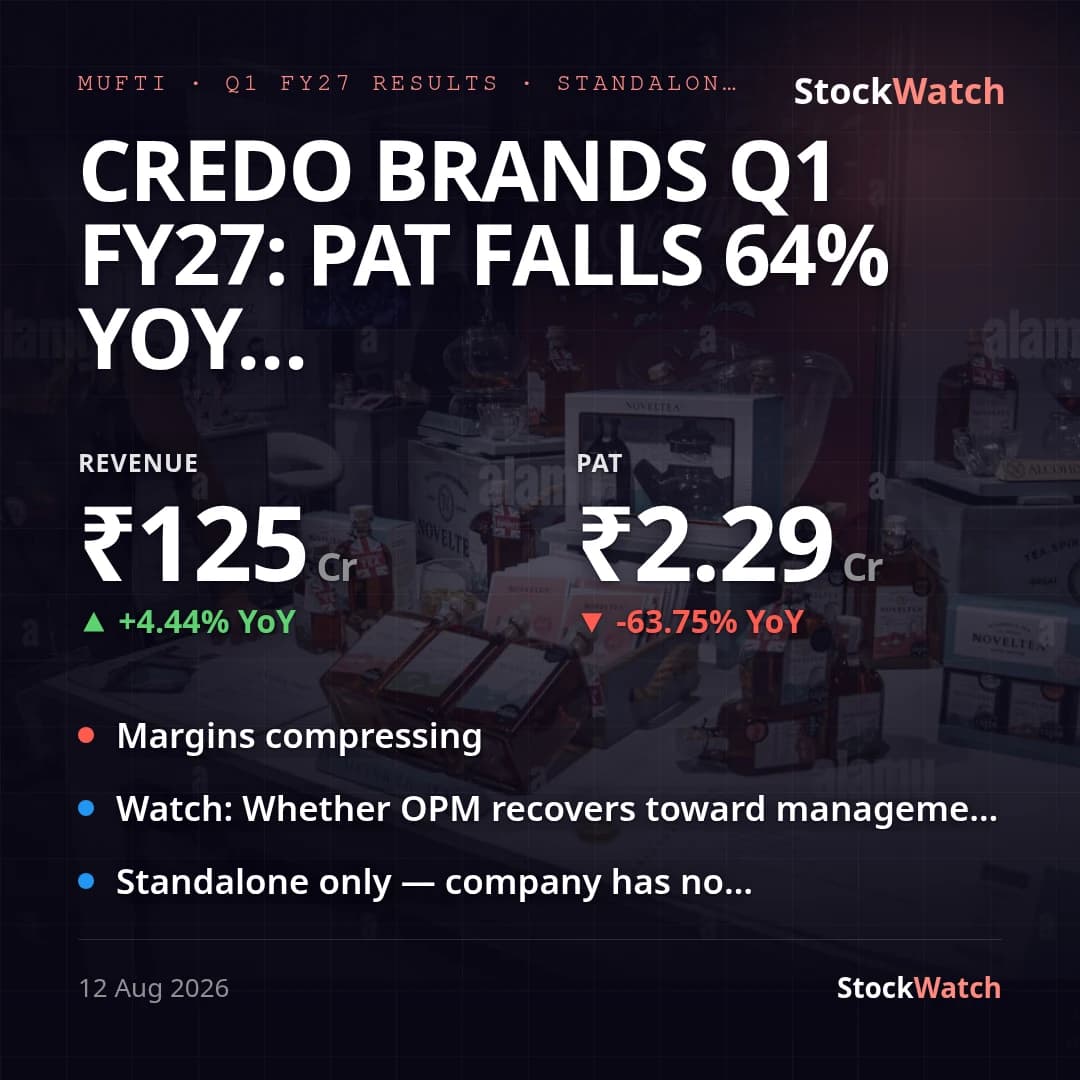
Credo Brands (MUFTI) reported standalone Q1 FY27 (quarter ended June 30, 2026) revenue of ₹125.3 Cr, up 4.4% YoY from ₹119.9 Cr, but standalone PAT fell 63.8% YoY to ₹2.3 Cr from ₹6.3 Cr, with basic EPS at ₹0.35 versus ₹0.97 a year ago; net profit margin compressed to 1.8% from 5.2%. Against the seasonally stronger Q4 FY26 (EOSS-driven), revenue was down 22.8% and PAT down 85% QoQ — a sequential drop that reflects Q1's structurally weak seasonality for apparel retail rather than fresh deterioration, so the YoY read is the one that matters.
The squeeze sits below the gross-profit line. Gross margin held broadly flat at ~61.6% (vs ~61.5% a year ago; gross profit grew ~4.6% YoY, matching management's own claim in its press release that "gross profit grew 5%" YoY), so premiumisation under Mufti 2.0 isn't costing margin at the product level. Instead, employee costs rose to 7.5% of revenue (from 7.0%) and other expenses — which include the guided step-up in advertising/branding spend (9-10% of revenue for FY27) — rose to 32.9% of revenue from 28.7%. Finance costs plus depreciation climbed to 25.5% of revenue from 20.4%, as the Mufti 2.0 store-network build-out adds fixed costs ahead of the sales base catching up. Combined, operating margin (OPM) fell to 21.2% — below management's guided FY27 EBITDA margin band of 23-24% — versus 25.9% YoY and 25.6% in Q4 FY26.
Management's own framing calls this "steady performance despite continued softness in discretionary spending," and 4.4% YoY revenue growth is broadly consistent with its guided mid-single-digit growth for FY27. But this quarter's OPM print running below the 23-24% guided band is a miss on the profitability guidance specifically, even allowing for Q1 seasonality — prior-year Q1 OPM of 25.9% was still above the current guided range, so seasonality alone doesn't explain the shortfall. No brokerage consensus estimates for this specific quarter turned up in search, so the beat/miss versus Street is unknown. Concurrently with the results, the board fixed August 28, 2026 as the dividend record date and set the AGM for September 11, 2026.