StockWatch
·

Cryogenic Ogs Ltd

BSE: 544440

P/L Snapshot

Q2 FY26 · standalone

vs Q2 FY25·vs Q2 FY25
Revenue
21.71
+0.0%+0.0%
Expenditure
15.67
+0.0%+0.0%
Net Profit
5.52
-0.1%-0.1%
OPM %
30.20%
+1.53pp+1.53pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.008.7417.4826.2334.97Q2 FY27Q2 FY25Q2 FY26
Price Chart
Reports

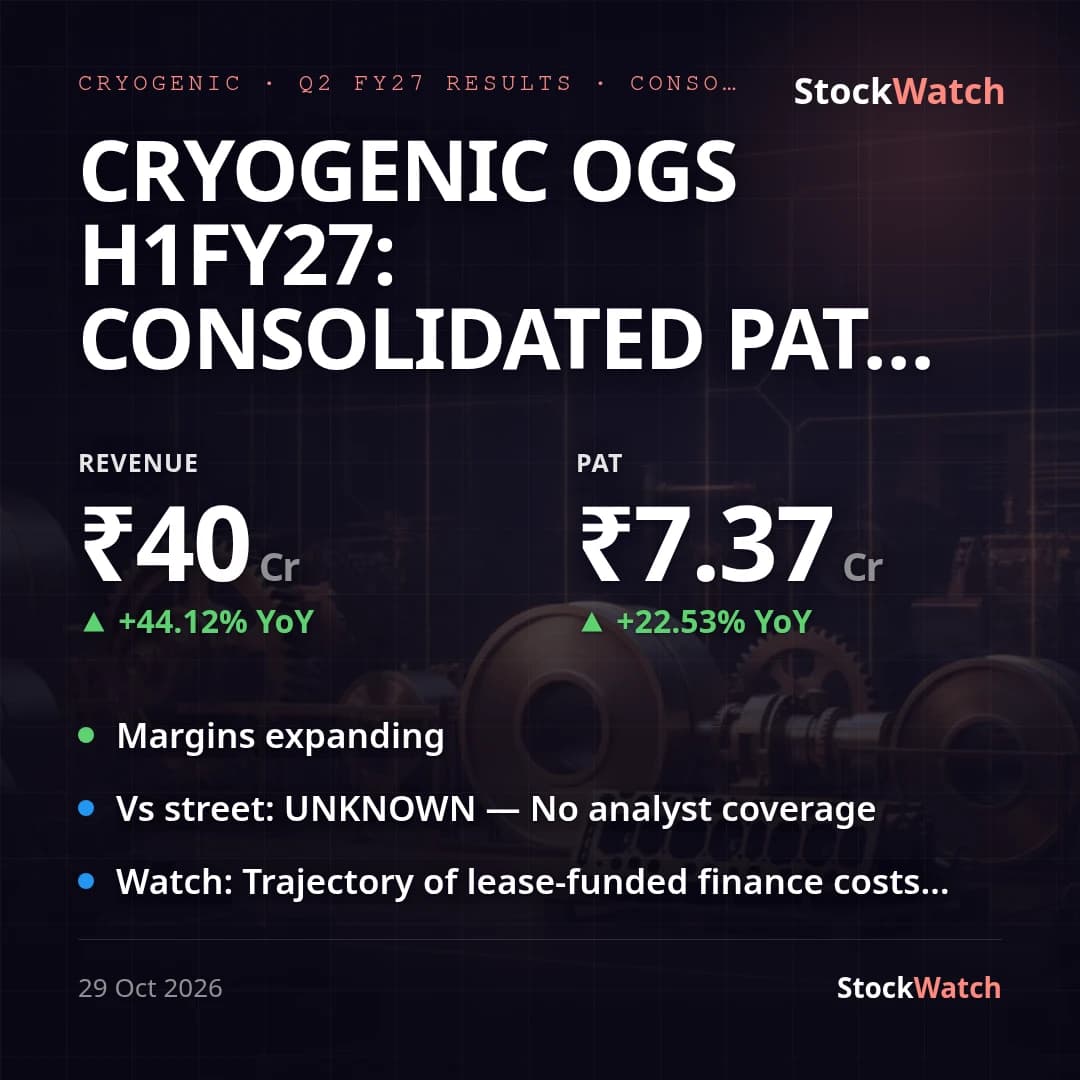
Cryogenic OGS H1FY27: consolidated PAT ₹7.37 Cr; standalone revenue +44% YoY, margins up

oil and gas equipment · cryogenic equipment · margin expansion

ResultsQ2 FY2729 Oct 20263 minIndustrials & Infra
Latest
Quarterly Result29 Oct, 1:02 pm

Cryogenic OGS H1FY27: consolidated PAT ₹7.37 Cr; standalone revenue +44% YoY, margins up

Cryogenic OGS's maiden consolidated financials — for the half year ended 30 September 2026 (H1 FY27), its first filing with the Precision Engineering Products subsidiary folded in — show consolidated revenue of ₹40.10 Cr and consolidated PAT of ₹7.37 Cr (₹7.07 Cr to owners, ₹0.30 Cr to minority interest), EPS ₹4.95. Because the subsidiary became one only this period, there is no consolidated year-ago base; the only like-for-like comparison is standalone, where revenue rose 44.1% YoY to ₹30.36 Cr and reported PAT rose 22.5% YoY to ₹6.76 Cr. The company carries zero sell-side coverage (0 analysts per SimplyWall St), so there is no street consensus to beat or miss. Management's own prior concall commentary had flagged expectations of 'good orders of similar size in H1 FY27 and through FY27'; order wins through the half (a ₹5.07 Cr international MNC order on Sep 30, a $2.02M piping-spools export order on Sep 18, a ₹4.6 Cr gas-metering-skids order on Aug 20) plus fresh ADNOC vendor approval and IBR certification for piping spools/strainers (Oct 8, just after period-end) indicate that pipeline materialised — the quarter reads as broadly meeting that loosely-worded guidance, though no numeric target exists in our records to grade precisely. Reported standalone PAT growth of 22.5% looks modest against 44% revenue growth, but that is a base-period artefact: H1 FY26 PAT was lifted by a ₹1.24 Cr one-off profit on sale of plot that has no equivalent this period. Stripping that one-off from both sides, adjusted PAT growth is closer to +58%, and adjusted net margin actually expands from ~19.7% to 21.65% — consistent with operating margin (EBITDA/revenue) expanding from ~30.0% to ~32.4% on cost discipline (materials cost ratio eased) and operating leverage. Headline NPM nonetheless fell from 25.41% to 21.65% purely on that lost one-off, compounded by a sharp jump in standalone finance costs (₹0.02 Cr to ₹0.27 Cr) as lease liabilities rose to ₹8.40 Cr and the company advanced a ₹6.18 Cr loan to its subsidiary. That lease-driven finance-cost line is worth flagging against the company's public zero-debt positioning, since it is now a visible, growing P&L item even without conventional borrowings.

29 Oct 2026, 01:02 pm

Corporate Events

Board MeetingCRYOGENIC
2026
29Oct

Board Meeting

The meeting of the Board of Directors of the Company is sche…

BSE Filing ↗
Board MeetingCRYOGENIC
2026
20Aug

Board Meeting

To receive, consider and adopt the audited financial stateme…

BSE Filing ↗