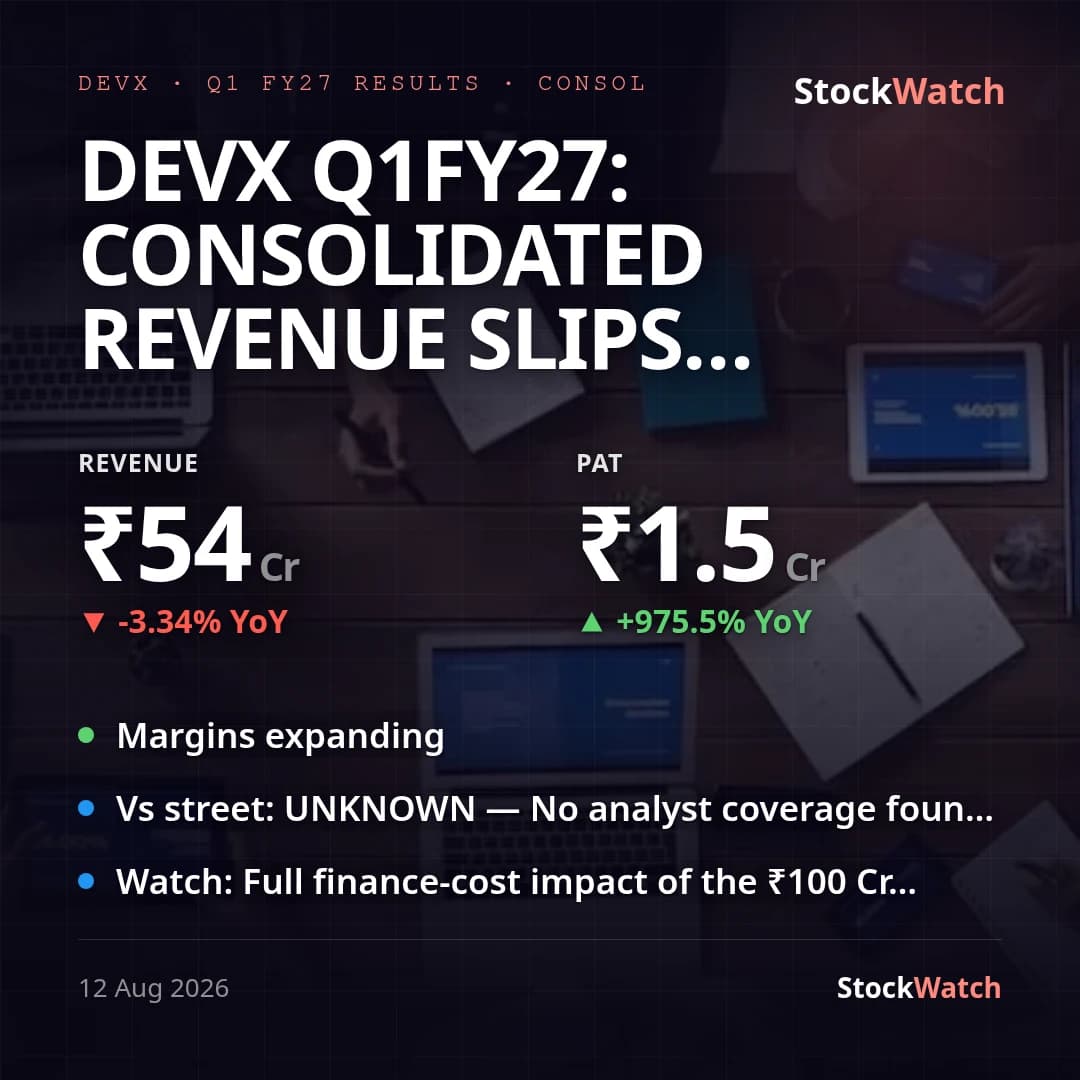
DevX Q1FY27: consolidated revenue slips 3% YoY, PAT thin at ₹1.5 Cr as finance costs rise
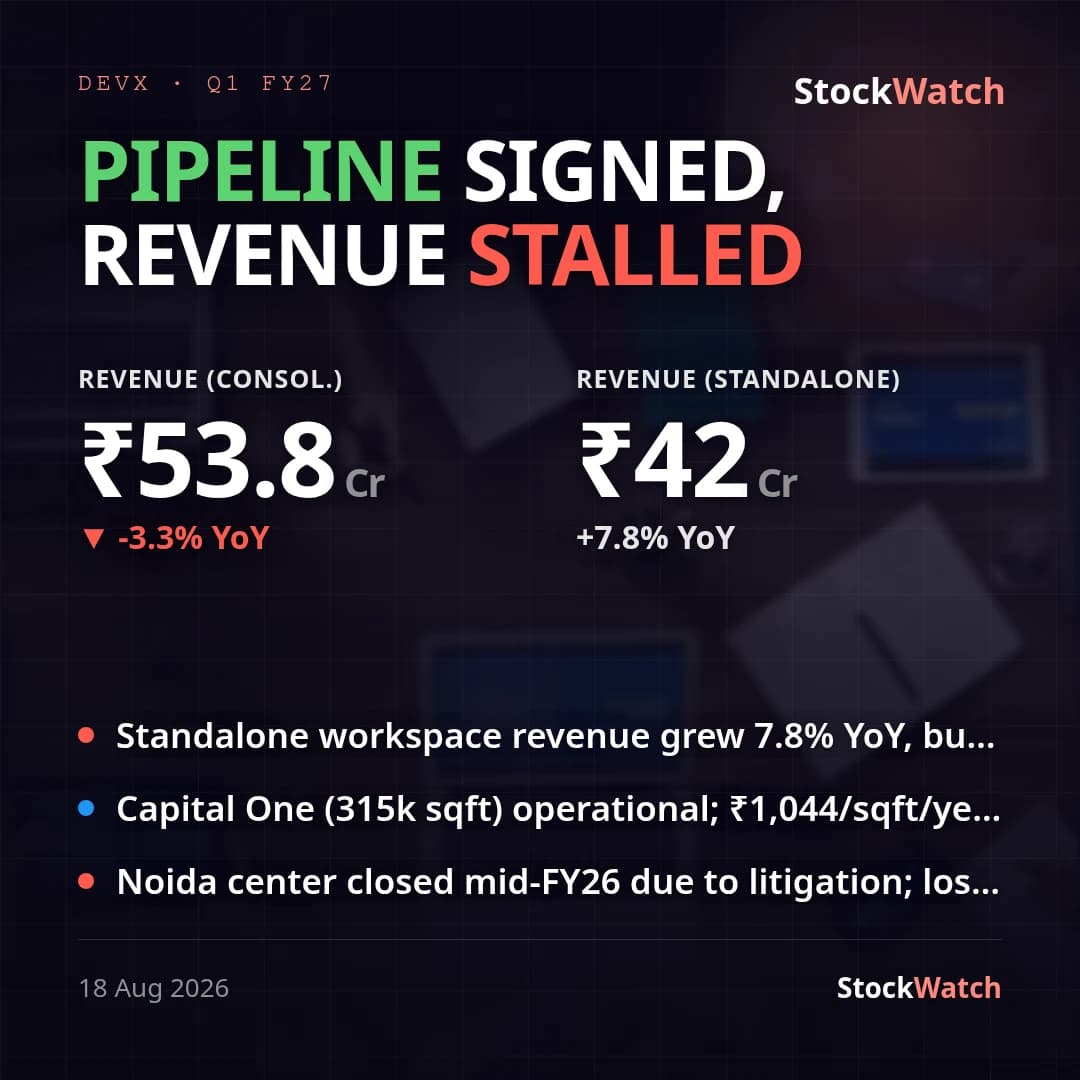
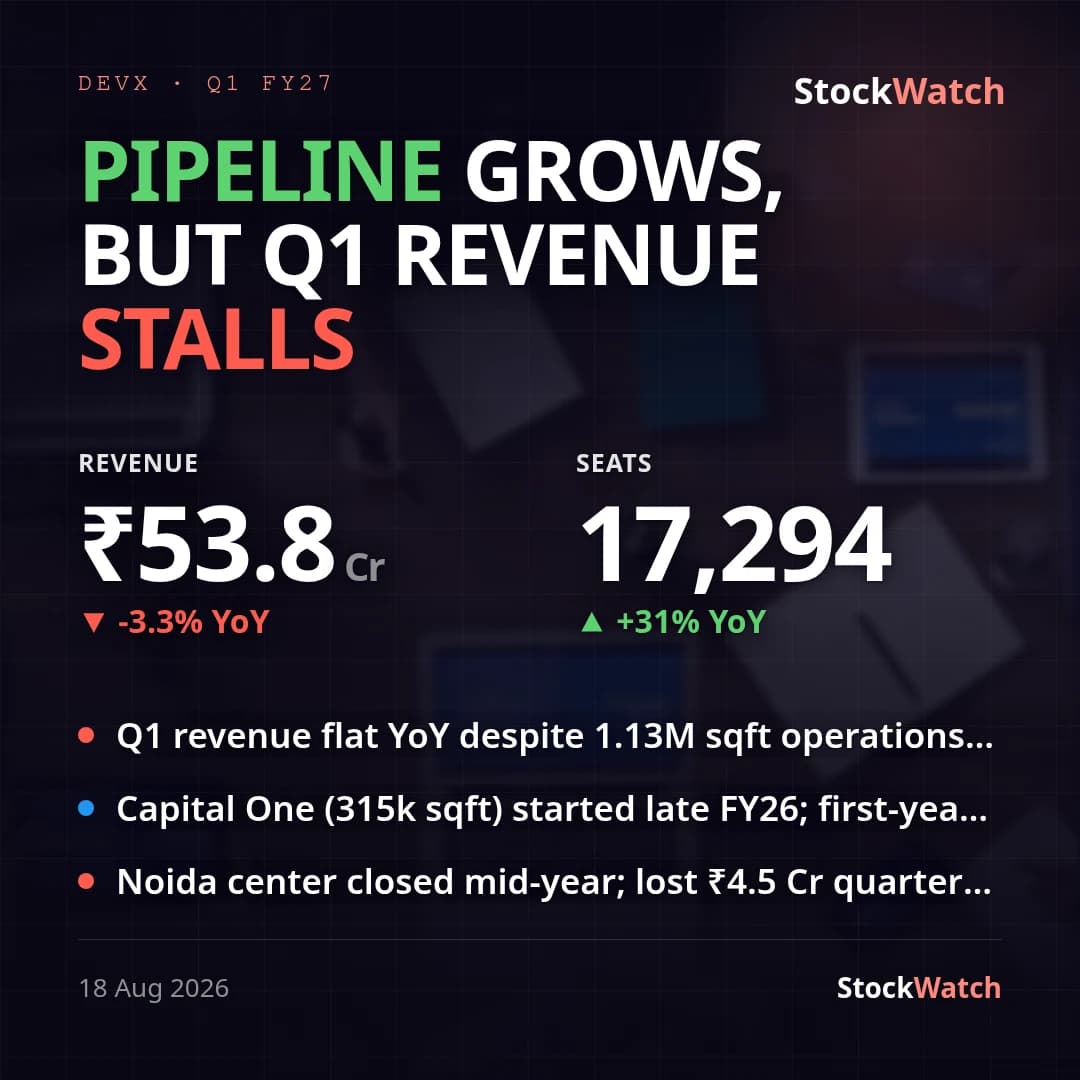
Dev Accelerator's (DevX) consolidated Q1 FY27 (quarter ended June 30, 2026) revenue came in at ₹53.77 Cr, down 3.3% YoY from ₹55.63 Cr and down 9.3% QoQ from ₹59.26 Cr in Q4 FY26. Consolidated PAT was ₹1.50 Cr (EPS ₹0.16) — up sharply YoY off a thin ₹0.14 Cr base a year ago, but down 81% QoQ from ₹7.96 Cr. There is no visible sell-side estimate for this print — analyst coverage is thin since the September 2025 IPO, and a web search on results day turned up no consensus figures — so vsStreet is unknown. Against management's own FY27 guidance from the May 2026 concall (revenue of ₹330-350 Cr and a steady 21-22% cash EBIT margin), the quarter is off to a weak start: a flat ₹53.77 Cr run-rate annualises to roughly ₹215 Cr, well short of the guided range, though this is only the first of four quarters against a full-year target.
The margin picture is split. Operating margin (revenue less operating, employee and other opex) actually expanded to 56.3% from 47.5% a year ago and 53.0% in Q4 FY26 (Q4's figure also absorbed a ₹1.15 Cr exceptional charge, absent this quarter), as core opex was contained even as revenue fell. But net margin stayed thin at 2.65% (versus 12.57% in Q4 and 0.25% a year ago) because Finance Costs rose to ₹14.0 Cr (+14% YoY, +36% QoQ) and Depreciation to ₹17.68 Cr (+22% YoY, +21% QoQ) — both consistent with the company capitalising new centres ahead of their revenue ramp, per its stated Tier-1/Tier-2 asset-commissioning plan. Standalone PAT of ₹2.00 Cr (on ₹41.98 Cr revenue) exceeded the consolidated ₹1.50 Cr, meaning subsidiaries/associates were a net drag this quarter.
During the quarter the company raised capital via a preferential allotment to Infibeam Projects Management and its promoters — 44.44 lakh equity shares (₹20.0 Cr) plus 33.33 lakh convertible warrants (₹15.0 Cr, of which ₹3.75 Cr/25% was received upfront) — taking paid-up capital to ₹18.93 Cr. Separately, it allotted ₹100 Cr of NCDs on August 4, 2026, whose finance-cost impact is explicitly excluded from this quarter's numbers as a non-adjusting subsequent event, and appointed Churchgate Advisory for IR services. No management press release or call commentary accompanied this filing, so the drivers above are inferred from the notes to the results rather than management's own framing.