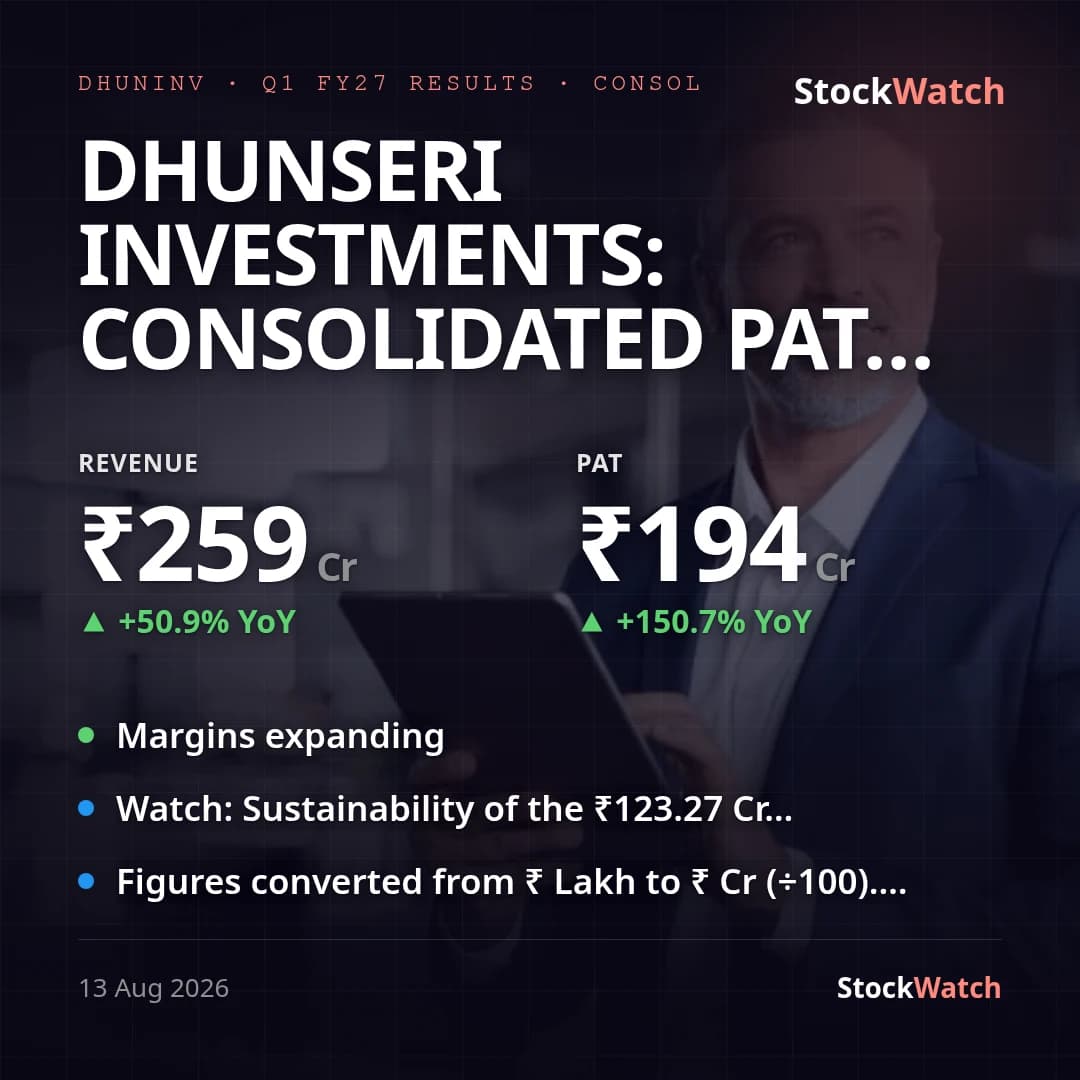
Dhunseri Investments: consolidated PAT +151% YoY to ₹193.8 Cr on investee income jump
Dhunseri Investments' consolidated PAT for Q1 FY27 was ₹193.79 Cr, up 150.7% YoY from ₹77.31 Cr and a sharp rebound from ₹3.50 Cr in Q4 FY26, on consolidated revenue from operations of ₹258.95 Cr (+50.9% YoY). PAT growth badly outpaced revenue growth, but with a large caveat: it was driven overwhelmingly by a ₹123.27 Cr share of profit from an equity-accounted investee, up from ₹27.36 Cr a year ago (+350.6%) — a swing bigger than the ₹119.60 Cr combined result of the Treasury Operations and Flexible Packaging Film segments together. Stripped of that swing, the underlying operating print is far more muted: Treasury segment result rose 33.3% YoY to ₹115.48 Cr (tracking gains on the investment book), while Flexible Packaging Film segment result actually fell 17.3% YoY to ₹4.12 Cr even as its revenue rose 72.2% to ₹137.91 Cr — implying margin compression to roughly 3.0% of segment revenue from 6.2% a year ago. Net profit margin (PAT/total income) expanded to 69.5% from 41.3% YoY, but that expansion reflects the mix shift toward associate income and fair-value gains rather than core cost efficiency.
Standalone (parent-only) numbers tell a smaller, directionally similar story: PAT was ₹16.82 Cr on revenue of ₹22.74 Cr, against ₹5.95 Cr PAT on ₹7.60 Cr revenue a year ago, as the parent's investment portfolio swung to a ₹21.24 Cr unrealised fair-value gain from a ₹5.02 Cr unrealised loss in Q1 FY26. Because the parent alone is a treasury vehicle, consolidated and standalone diverge materially in scale (₹193.79 Cr vs ₹16.82 Cr PAT) — the gap is the packaging-film subsidiary and the equity-accounted investee, both consolidated-only lines, so readers should treat the two prints as answering different questions rather than one contradicting the other. There were no exceptional items this quarter on either basis (FY26 carried a one-off ₹0.23 Cr gain on the Hatibari Tea Factory settlement, not repeated), and the Twelve Cupcakes (Singapore F&B) discontinued operation, in creditors' voluntary winding-up since October 2025, contributed nil this quarter versus a ₹2.50 Cr loss a year ago.
We found no street/analyst previews or consensus estimates for this stock — it carries no visible sell-side coverage — so vsStreet is unknown, and the company has no formal guidance on record to check the print against; management issued no separate press release or call commentary beyond the regulatory filing and auditor review reports. This quarter's other disclosed developments were administrative rather than financial: independent director Raj Vardhan Kejriwal completed his term on Aug 9, 2026, and the company filed its FY26 annual report ahead of its 29th AGM scheduled for Aug 20, 2026 — neither bears on the P&L. The volatility of the headline number is worth flagging on its own: Q4 FY26 shows how quickly it can reverse, when a ₹55.84 Cr consolidated fair-value loss cut PAT to near breakeven at ₹3.50 Cr.