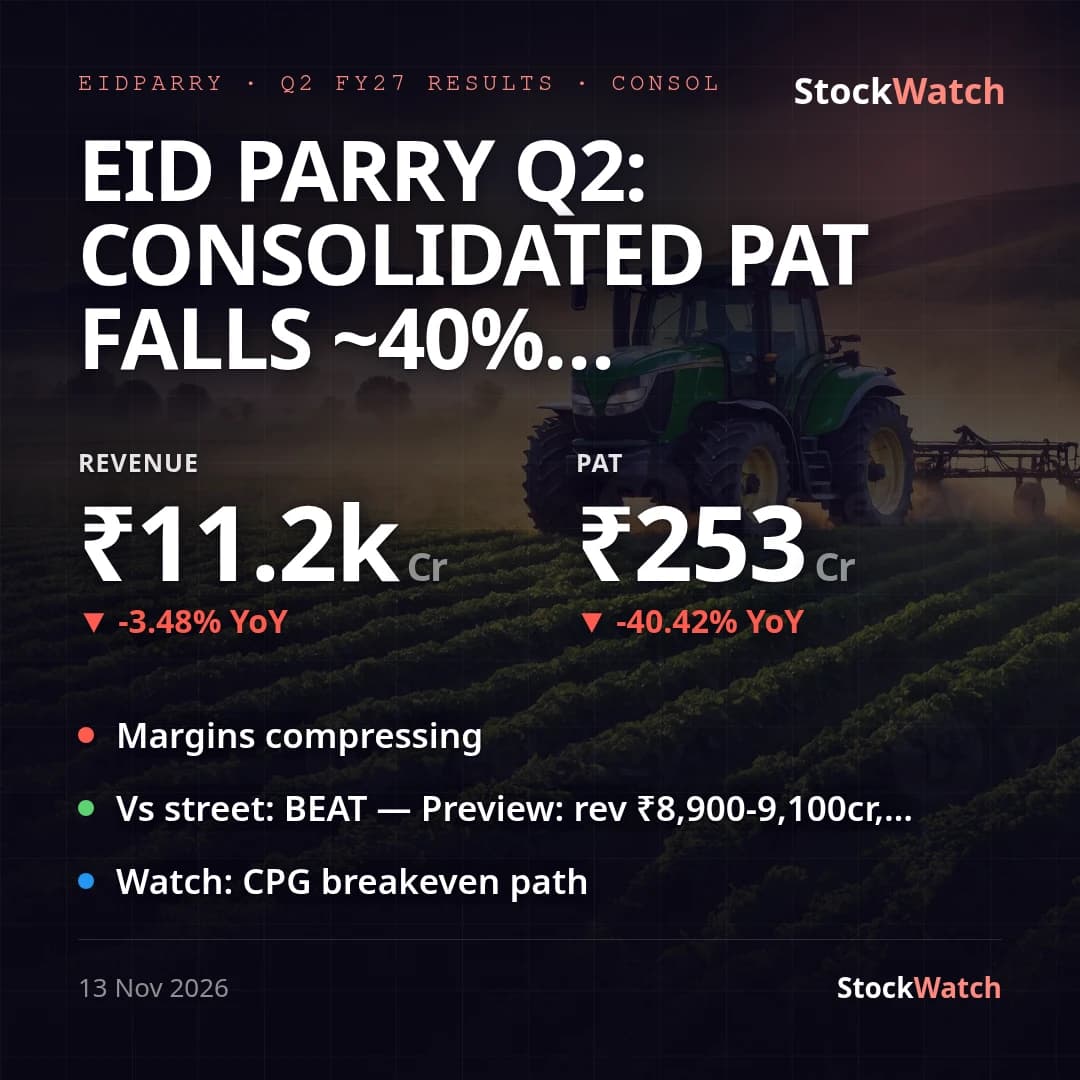
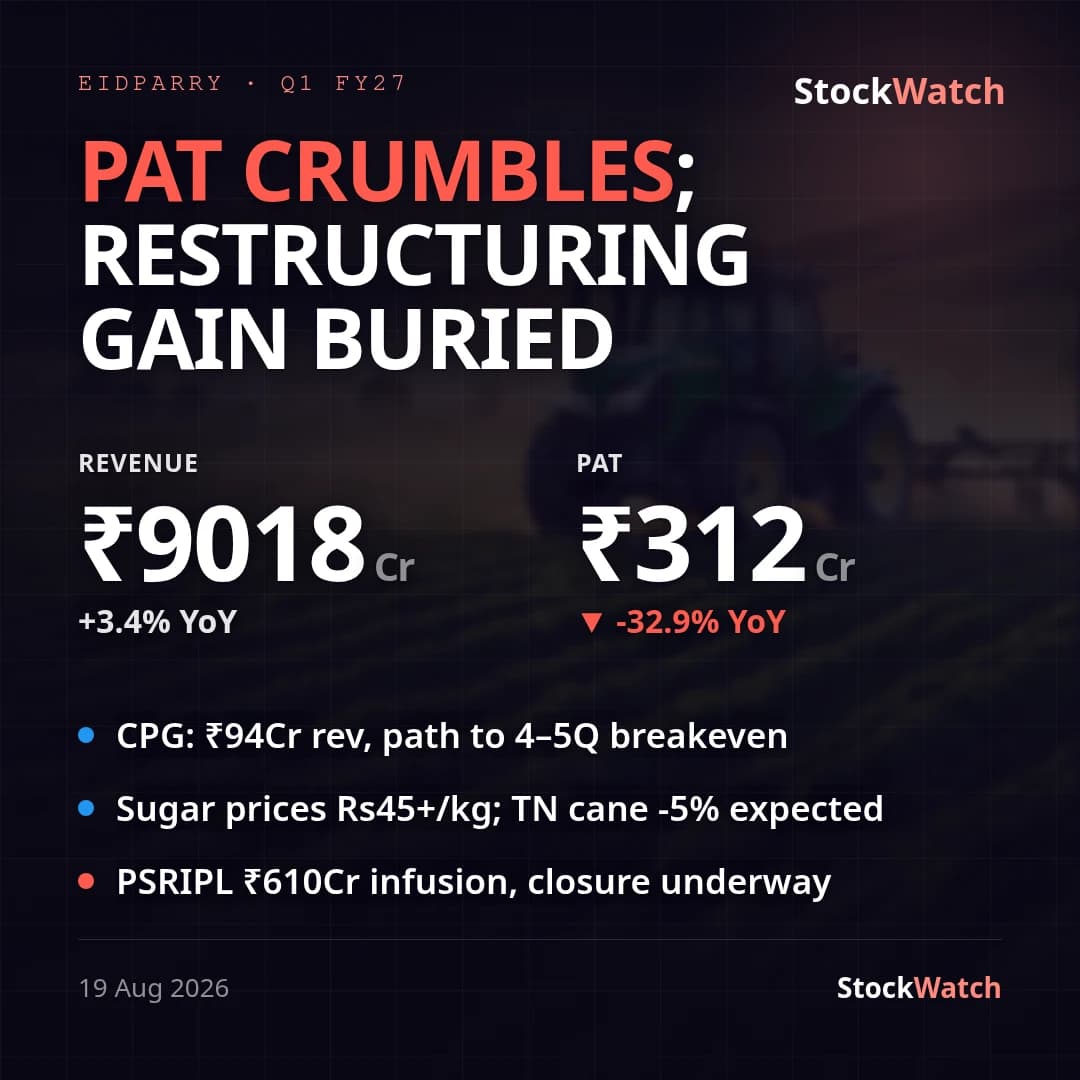
EID Parry's consolidated (primary) PAT attributable to owners fell ~40% YoY to ₹252.86 Cr from ₹424.41 Cr in Q2 FY26, even as group revenue dipped ~3.5% YoY to ₹11,219.70 Cr — a second straight quarter of YoY earnings weakness, as flagged in our pre-result preview. Sequentially both metrics jumped sharply (PAT +79% QoQ, revenue +24% QoQ) on the seasonal Kharif-season ramp in the Coromandel nutrient and allied business (₹9,042 Cr segment revenue, ₹745.90 Cr segment PBIT) — this QoQ strength is a seasonality artifact typical of the agri-input cycle, not a turnaround signal, and the YoY decline remains the operative story. No exceptional items hit either statement this quarter, so both prints are clean like-for-like comparisons.
Margins compressed on a YoY basis: net margin (owners'-PAT basis) fell to ~2.25% from ~3.65% a year ago, though it improved from ~1.57% in Q1 FY27. Our own EBITDA-margin estimate from the filing works out to ~8.8%, down from ~10.3% YoY but up from Q1's ~8.3%. Beyond the dominant nutrient/crop-protection businesses, two standalone drag segments remain relevant: Consumer Products (CPG), whose loss widened to ₹24.48 Cr this quarter from ₹11.98 Cr in Q1 FY27 (though narrower than ₹26.93 Cr a year ago), and Nutraceuticals, which posted a ~10.9% margin (₹7.67 Cr profit on ₹70.10 Cr revenue) — below the 12-15% steady-state band management flagged on the August 2026 call.
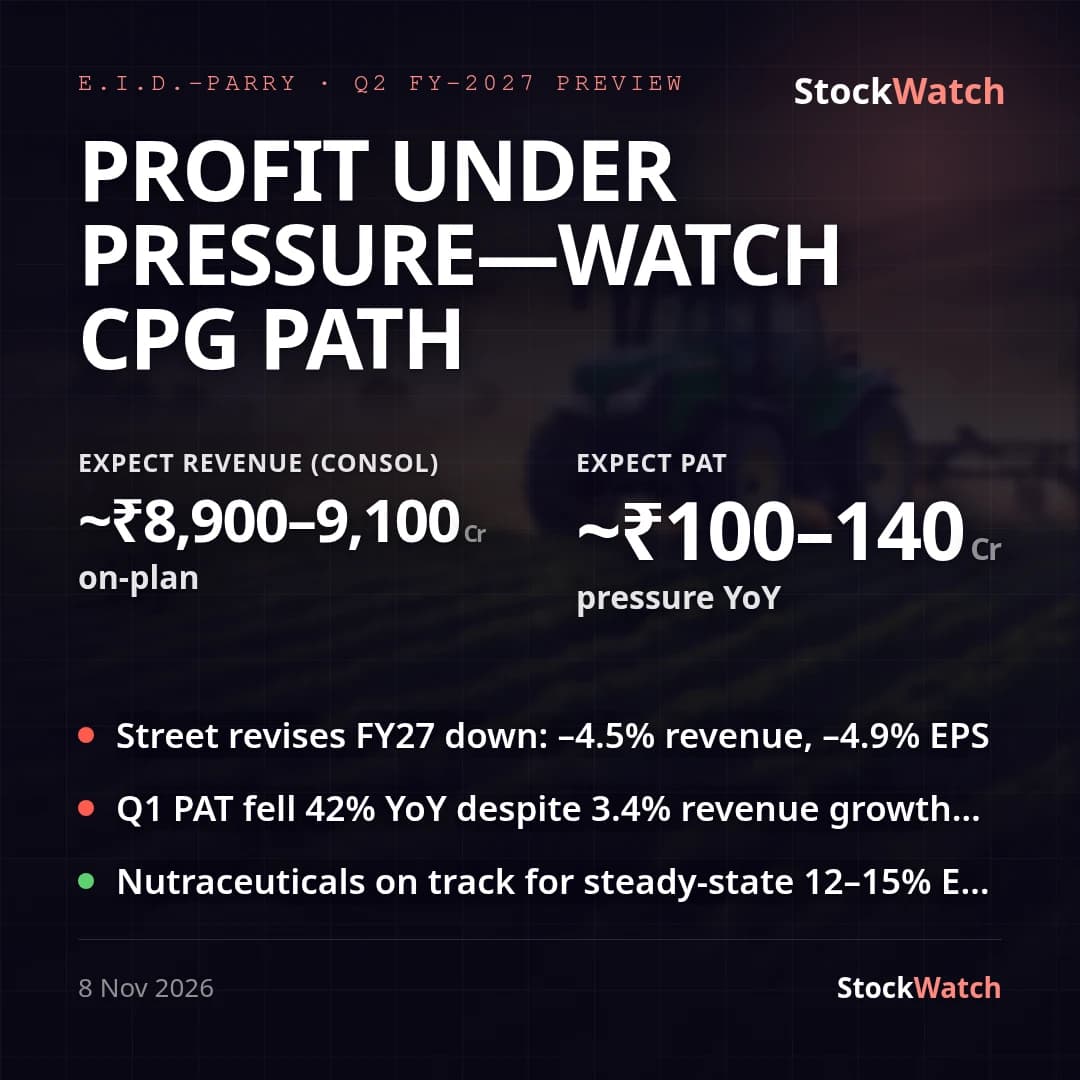
There is no verified external analyst consensus for this specific quarter (coverage is thin — the preview noted a single-analyst Buy rating with a recently cut FY27 target), so the cleanest yardstick is our own pre-result preview, which modeled consolidated revenue of ₹8,900-9,100 Cr, PAT of ₹100-140 Cr and an 8-9% EBITDA margin. The actual print beat that range decisively on revenue (+23-26% above the top end) and PAT (nearly double the top end), while the margin assumption landed almost exactly in the money (~8.8% vs 8-9% guided) — indicating the preview had under-anchored growth to Q1's seasonally soft base rather than Q2's agri-season strength. Against management's own prior framing from the last call: Nutraceuticals remains below its targeted margin band, and CPG shows no sequential progress toward the 4-5-quarter breakeven path (the loss widened, not narrowed, versus Q1); management gave no formal FY27 revenue/PAT guidance, consistent with the prior call, so that specific angle is unresolved on record. No management press release text was available to quote for this filing. Subsequent to the quarter, the Board approved a slump sale of the Sivagangai Distillery Unit on a going-concern basis (Nov 13, 2026), a non-adjusting event with no impact on these numbers; separately, standalone's year-ago quarter carried a ₹352.23 Cr one-off impairment tied to the Parry Sugars Refinery India (PSRIPL) closure that is absent this quarter and absent at the consolidated level throughout — which is why standalone's YoY narrative (loss narrowing to ₹22.49 Cr from ₹285.62 Cr) looks far better than the consolidated one.
Going into Q3 FY27, the markers are whether CPG's loss actually starts narrowing toward its multi-quarter breakeven target, whether Nutraceuticals closes the gap to its 12-15% margin band, and whether the ₹100 Cr Jaggery capacity (guided online roughly six months from the August 2026 call, i.e. around February 2027) comes on stream as planned.