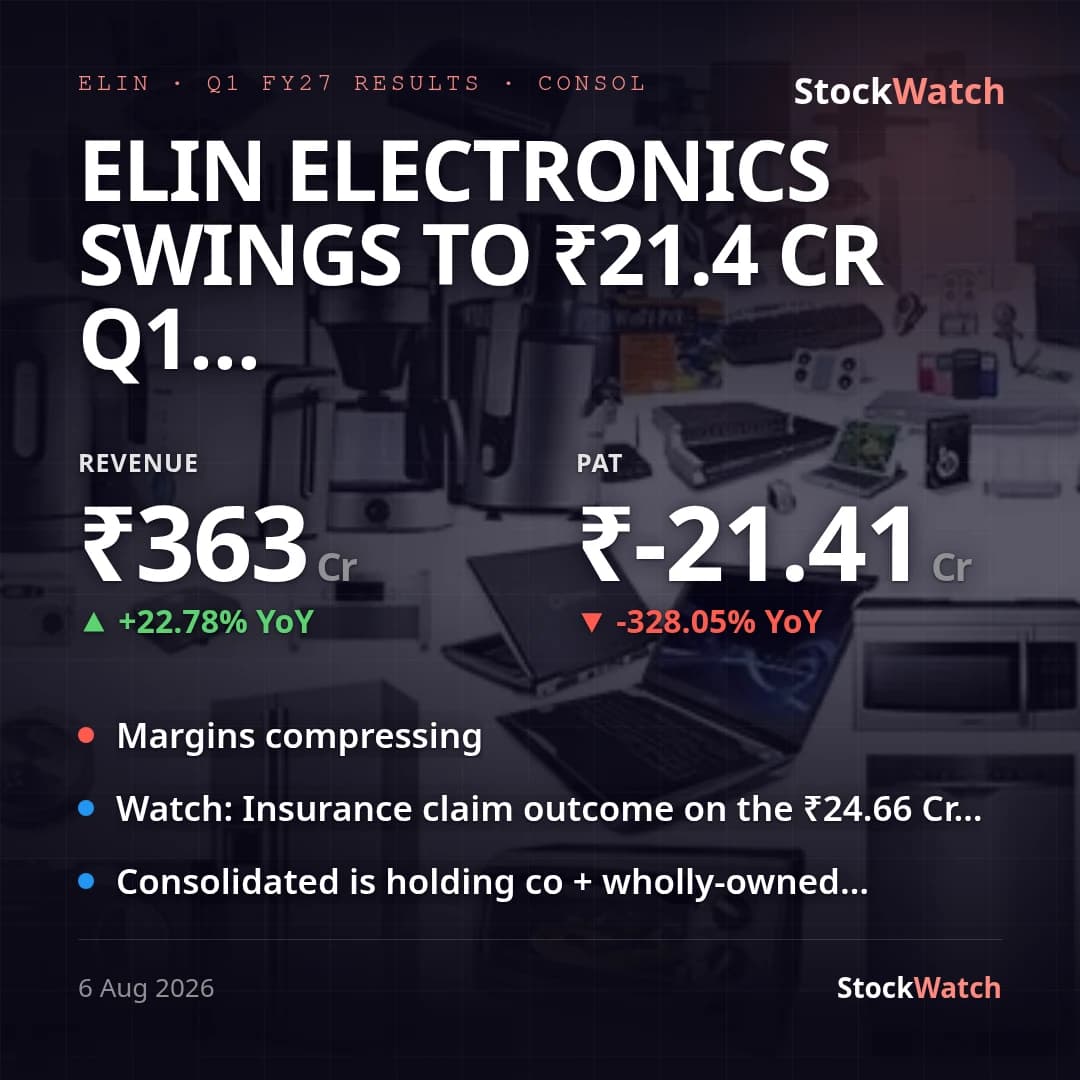
Elin Electronics swings to ₹21.4 Cr Q1 FY27 loss on ₹24.7 Cr Ghaziabad fire charge
Elin Electronics' consolidated revenue rose 22.8% YoY and 11.9% QoQ to ₹362.80 Cr, but the group swung to a consolidated net loss of ₹21.41 Cr (EPS -₹4.39) versus a ₹9.39 Cr profit a year ago and a smaller ₹0.76 Cr loss last quarter. The swing was driven by a ₹24.66 Cr exceptional charge for fire damage (inventory, plant/equipment, factory building) at the Ghaziabad facility, first reported 25 May 2026 and formally recognised in this quarter's results. Even excluding the one-off, core pre-exceptional consolidated PBT was still a loss of ₹3.76 Cr against a ₹12.67 Cr profit a year ago — on our estimate applying the quarter's effective tax rate to the exceptional item, adjusted PAT works out to roughly -₹2.83 Cr versus +₹9.39 Cr YoY (~-130% adjusted), so the deterioration is not fully explained by the fire.
Consolidated NPM fell to -5.86% from +3.15% a year ago and -0.23% last quarter, as cost of materials and other operating costs rose alongside revenue and finance costs/depreciation stepped up with the ongoing capacity ramp. The parent-only (standalone) statement tells a similar but somewhat weaker story: standalone revenue grew a slower 14.4% YoY to ₹275.22 Cr (versus the group's 22.8%, implying the subsidiary Elin Appliances drove a disproportionate share of consolidated growth) and standalone too flipped to a ₹19.89 Cr loss from an ₹8.87 Cr profit, on the same ₹24.66 Cr fire exceptional item.
No consensus PAT/revenue estimates for this specific quarter could be found in public previews, so the print cannot be graded against street numbers (vsStreet: unknown). On guidance, management's last formal commentary (Q3 FY26 concall) targeted 9-10% revenue growth and a 5.3-5.8% EBITDA margin for FY26 (now lapsed) and separately flagged the new Bhiwadi facility (May 2026 launch) to add ~₹140 Cr of FY27 revenue at a 7-7.5% steady-state EBITDA margin, plus fans (+50%) and lighting (double-digit) segment growth for FY27; none of this is independently verifiable this quarter because the company discloses a single reportable manufacturing segment with no product-line breakout, so whether Bhiwadi/fans/lighting are tracking to plan remains unconfirmed (vsGuidance: unknown). The quarter's other corporate developments — insider-trading window closure, the FY26 audited results/ESOP cancellation approved 25 May 2026, and the dissolution of the Risk Management Committee announced alongside this result — are routine and don't bear directly on the numbers; the fire disclosure itself confirms assets and inventory are adequately insured and a claim is being lodged, but no insurance recovery has been recognised in either statement yet.
Going into Q2 FY27, the loss this quarter sets up two things to track: whether any insurance recovery on the fire claim gets recognised, and whether revenue growth (currently running well ahead of the lapsed FY26 9-10% guide) converts into positive core profitability once the one-off cost drag clears.