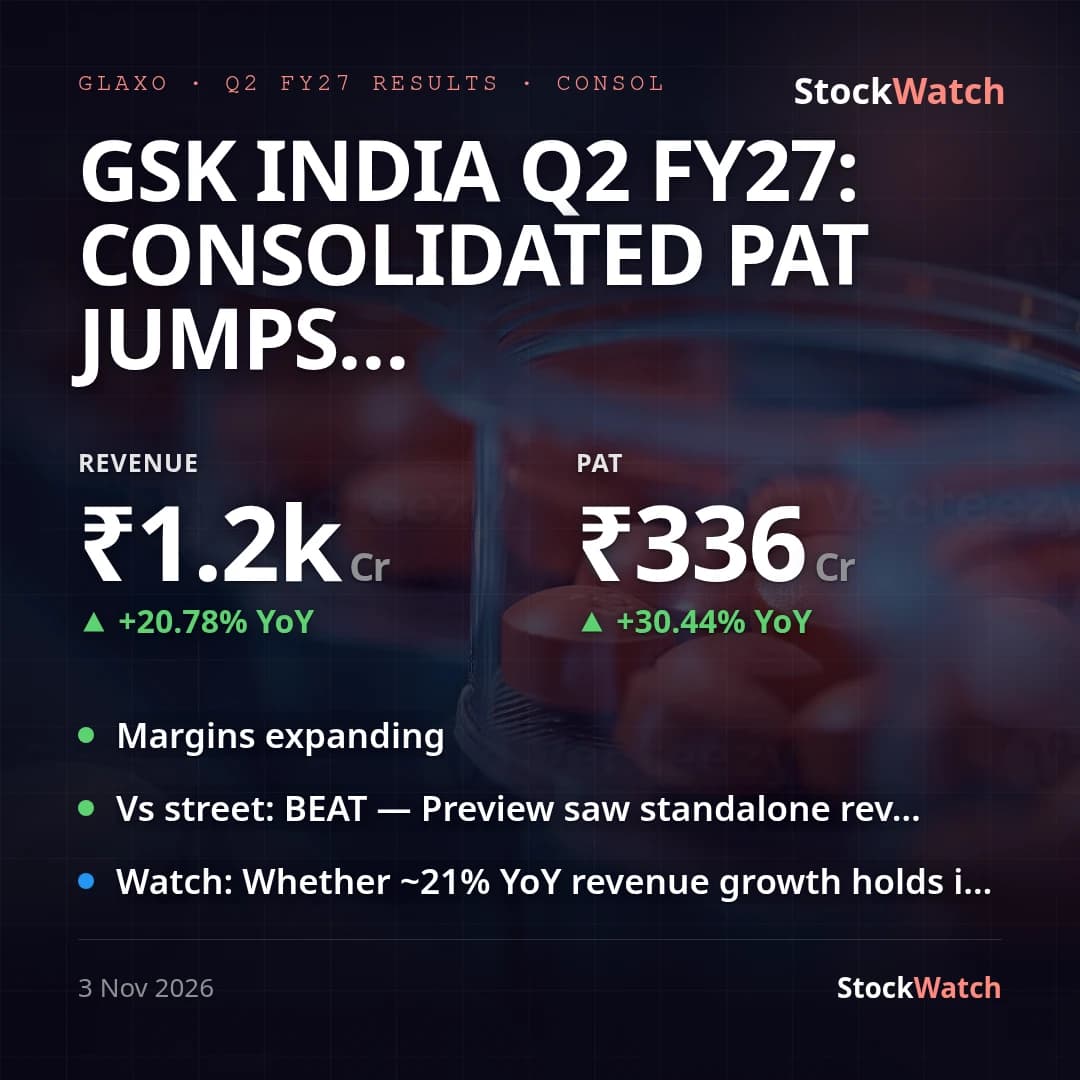
GSK India Q2 FY27: Consolidated PAT jumps 30% YoY on 21% revenue growth, beats guidance
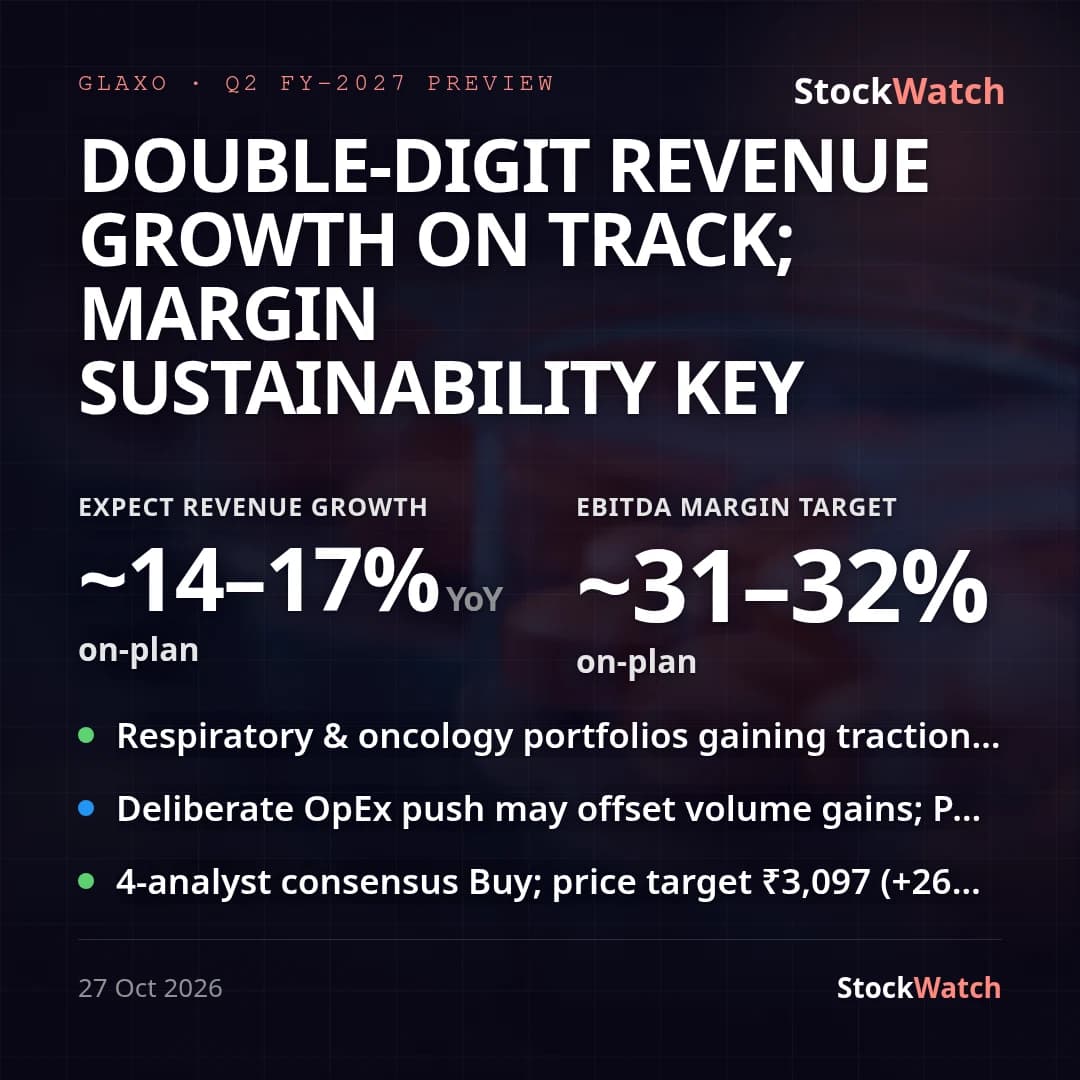
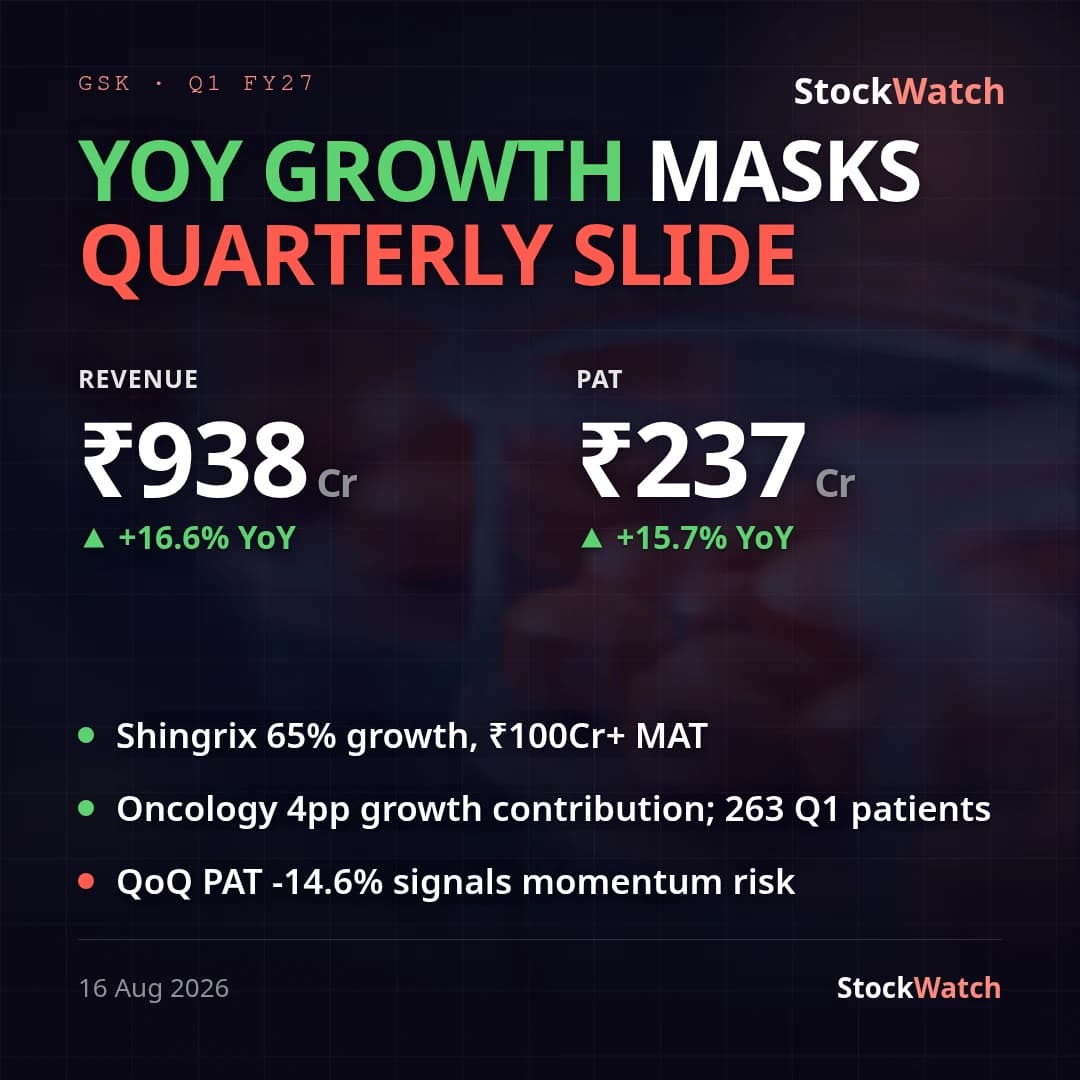
GlaxoSmithKline Pharmaceuticals (GSK India) reported consolidated revenue of Rs 1,183.57 Cr for Q2 FY-2027 (quarter ended 30 September 2026), up 20.8% YoY (Rs 979.94 Cr) and 26.1% QoQ (Rs 938.44 Cr). Consolidated PAT came in at Rs 335.88 Cr, up 30.4% YoY (Rs 257.49 Cr) and 41.6% QoQ (Rs 237.18 Cr); adjusted for a minor Rs 2.64 Cr one-off property-sale credit in the year-ago quarter, underlying PAT growth is ~31.8% YoY — a clean beat, not one-off-driven. EPS was Rs 19.83 against Rs 15.07 a year ago. Standalone numbers track closely (revenue Rs 1,179.91 Cr, PAT Rs 334.62 Cr, EPS Rs 19.76), under 0.4% divergence from consolidated, so the subsidiary contributes negligibly to the quarter's story. This is a clear beat against both the pre-result expectation range (standalone revenue ~Rs 920-950 Cr, PAT ~Rs 225-245 Cr) and management's own August-concall framing of 9-10% underlying growth (plus a 4-5pp favourable base from prior-year CMO disruptions) — actual YoY growth of ~21% comfortably clears that bar.
The beat is volume-led: management had flagged Q2 as seasonally strong on acute/respiratory demand, and revenue from operations grew in step with that call. Consolidated NPM (PAT/total income) expanded to 26.7% from 25.4% a year ago and 24.2% last quarter, driven by operating leverage over cost of materials and purchases of stock-in-trade rather than financial items — finance costs were flat at Rs 0.49 Cr and depreciation Rs 15.02 Cr, both immaterial to the swing. EBITDA-equivalent OPM was ~34.0%, essentially level with the year-ago 34.5% (a ~0.5pp YoY dip, not a trend) and up sharply from 31.5% last quarter — consistent with management's stated target of EBITDA margins normalising to the ~34% range. Other income of Rs 72.78 Cr included Rs 42.09 Cr of interest on an income-tax refund, which coincides with the Rs 52 Cr IT refund the company disclosed receiving on 6 August 2026 and a further Rs 4.99 Cr refund on 19 August 2026 — a cash-flow tailwind captured in other income, not operating profit. No exceptional items hit either statement this quarter.
No company press release accompanied this filing, so framing rests on the regulatory statement and the prior concall. The same board meeting also approved Walker Chandiok & Co LLP as statutory auditors for a five-year term from FY2027-28, and named Sandeep Seth as Head – Ethics & Compliance effective 3 November 2026 — governance items unconnected to the quarter's operating performance. The quarter was otherwise bookended by August's trading-window closure ahead of results and Bhushan Akshikar's MD reappointment on 3 August 2026, against the Q1 FY27 base (revenue Rs 938.44 Cr, PAT Rs 237.18 Cr) this quarter's sequential jump is measured off.
Going into H2 FY27, the key question is whether ~21% YoY growth holds or reverts toward management's stated 9-10% underlying run-rate once the seasonal acute-demand tailwind and the prior-year CMO-disruption base effect fade. The ~34% OPM this quarter matches management's medium-term margin target, so the watch is whether that holds without the seasonal volume boost, not whether it was met this quarter.