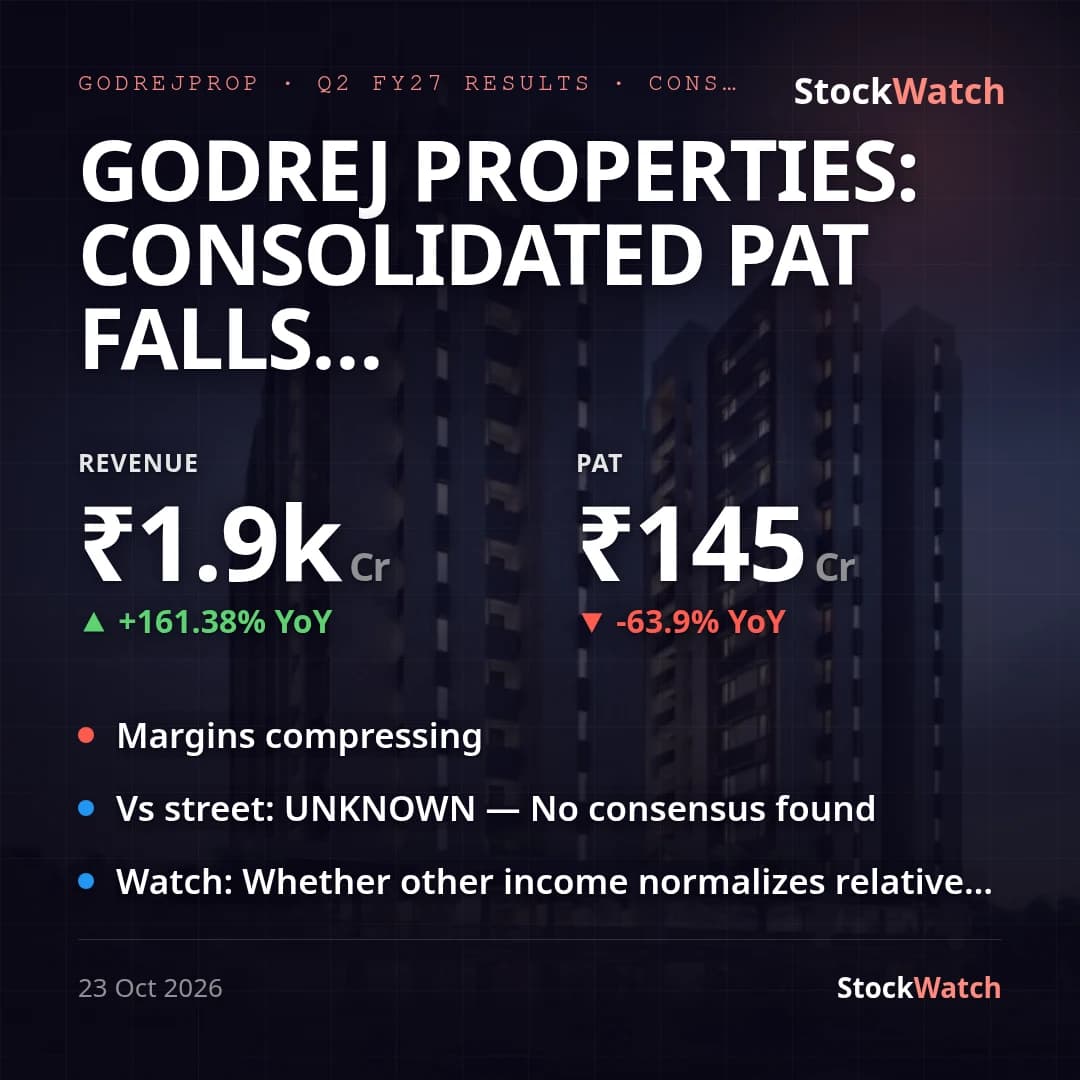
Godrej Properties: consolidated PAT falls 64% YoY to ₹145 Cr despite 161% revenue surge
Godrej Properties' consolidated revenue from operations surged 161.4% YoY and 282.3% QoQ to ₹1,935.17 Cr on project completions/handovers, but consolidated PAT fell 63.9% YoY to ₹145.47 Cr (from ₹402.99 Cr) and 58.4% QoQ (from ₹349.38 Cr). Net profit margin compressed to 5.65% from 21.59% YoY and 26.14% QoQ. No exceptional items sat in either comparison period, so the decline is on a clean like-for-like basis. Owners' share of consolidated PAT was ₹154.15 Cr (basic/diluted EPS ₹5.12) after an ₹8.68 Cr loss attributable to non-controlling interests; standalone PAT was ₹80.76 Cr on total income of ₹729.20 Cr (EPS ₹2.68) — consolidated remains the primary read given the scale gap between the two.
The margin story is nuanced rather than a straightforward operating miss. The company's own operating-margin metric (EBITDA excluding other income, over revenue from operations) actually improved to -19.22% from -67.12% a year ago and -54.04% last quarter — core project cost-to-revenue matching got relatively better, not worse, in a sector where percentage-of-completion accounting routinely produces negative headline operating margins. The NPM compression instead traces to other income, which fell 47% YoY to ₹636.56 Cr and shrank to just ~25% of total income versus ~62% in both the year-ago and preceding quarters — the interest/financial income that had been propping up reported profit didn't scale with the jump in operating revenue this time. Finance costs also rose 74% YoY to ₹37.41 Cr as gross debt-equity climbed to 1.02x from 0.88x a year ago, while the JV/associate line turned a modest ₹3.39 Cr profit versus an ₹83.14 Cr loss a year ago — a partial offset that wasn't enough to prevent the PAT decline.
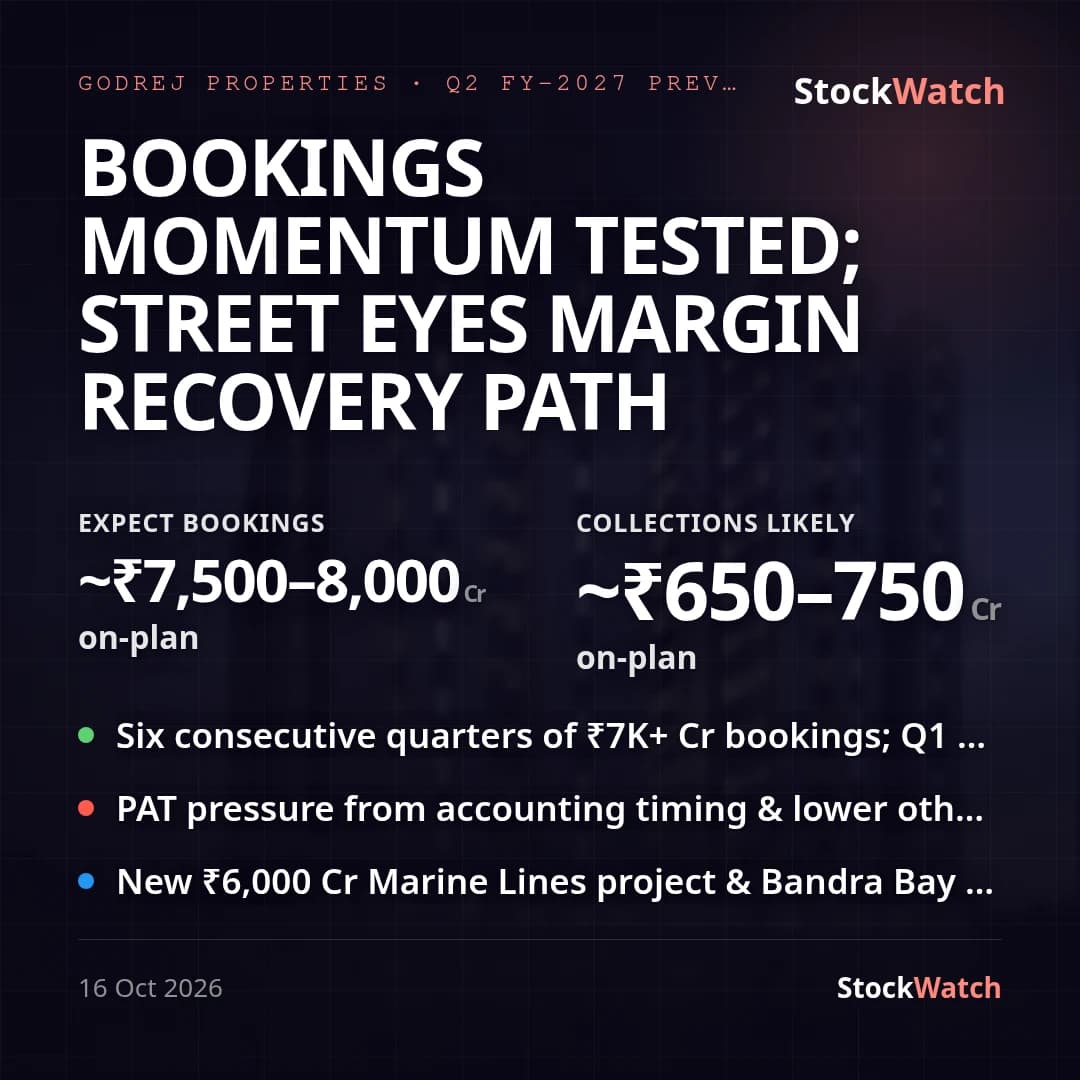
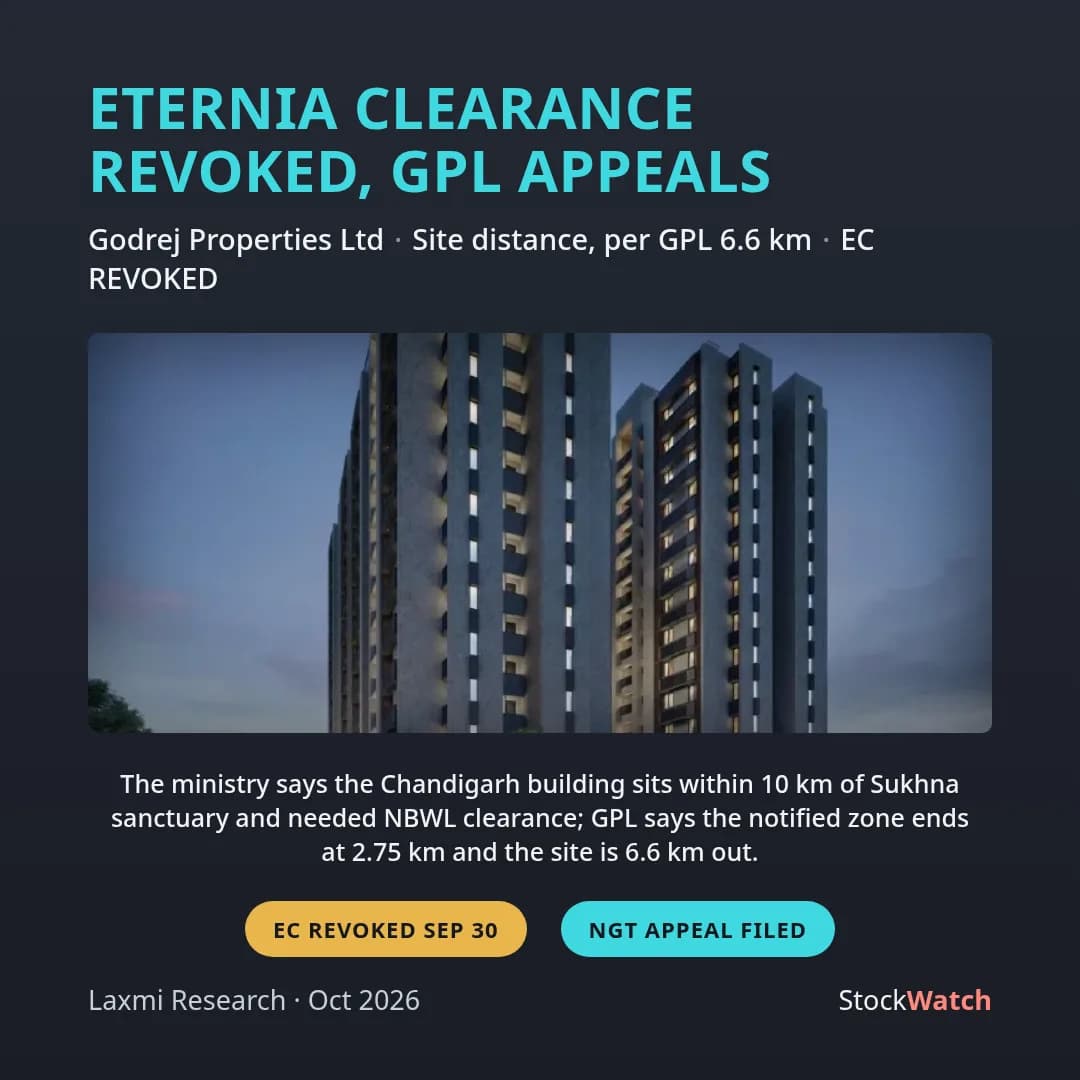
No analyst consensus specific to this quarter could be located — a pre-result preview explicitly noted no estimates were available and recommended tracking bookings/pre-sales rather than the P&L lines — so vsStreet is unknown. Management's FY27 guidance from the May 2026 concall (bookings above ₹39,000 Cr, collections above ₹24,000 Cr, a 20% growth trajectory, and a 20% ROE target by FY28) cannot be checked against this filing since booking/pre-sales values aren't disclosed in the standalone or consolidated financial statements; that verdict awaits the accompanying investor presentation. The quarter's corporate developments were largely non-financial and don't yet show up in these numbers: the October 23 board meeting approving these results, the Bandra Bay pedestrian corridor/BMC promenade partnership, a new ₹6,000 Cr luxury project addition in Marine Lines, and the revocation of the Godrej Eternia environmental clearance (now under NGT appeal). No management press release accompanied this regulatory filing, so there is no company commentary to reconcile against the print.
With other income unlikely to repeat at the scale that cushioned FY26 margins, and finance costs rising on higher short-term borrowings (₹17,495.56 Cr, up from ₹13,364.87 Cr at FY26-end), H2 FY27 profitability will hinge on operating revenue recognition continuing at this pace with sustained cost matching, plus verified progress toward the ₹39,000 Cr bookings target.