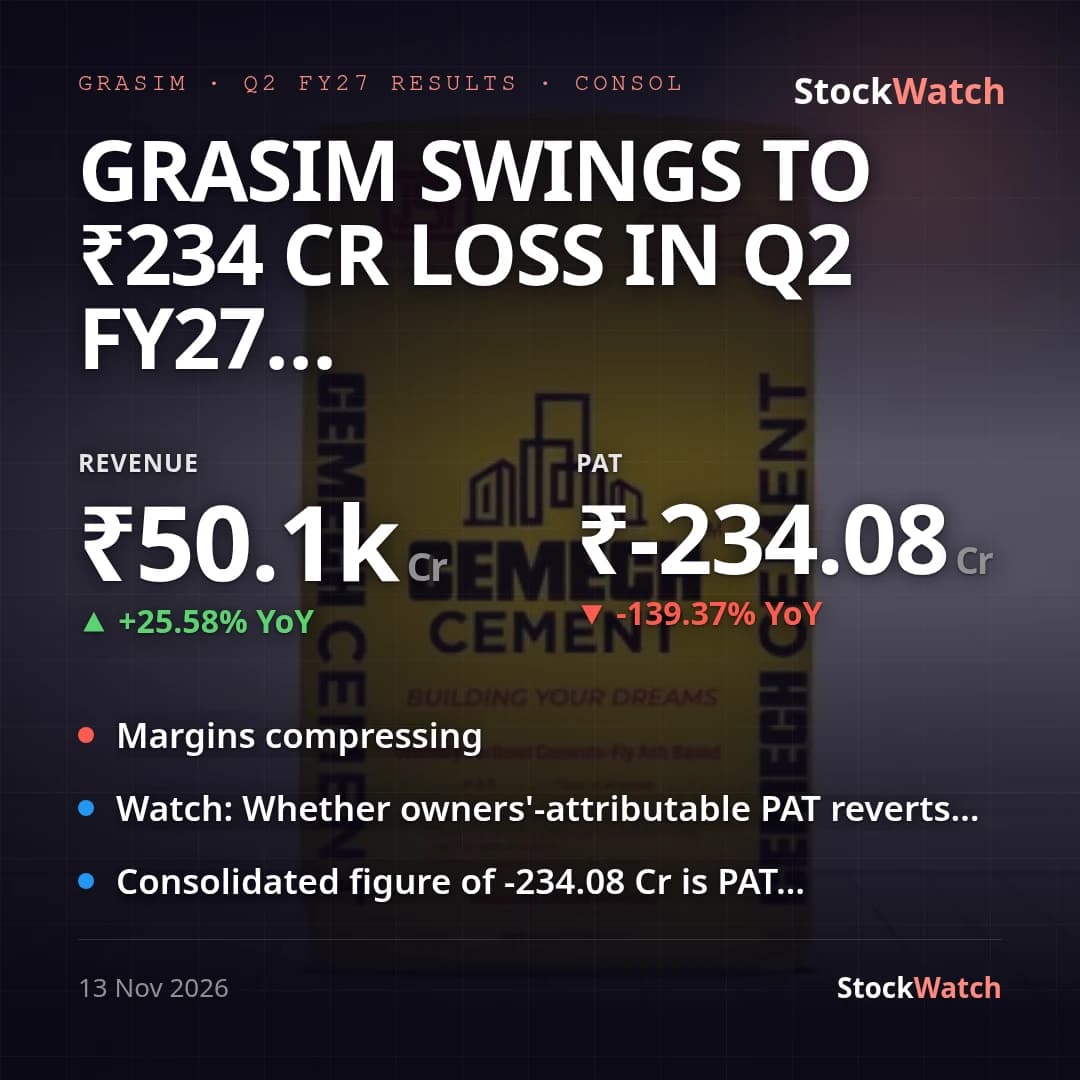
Grasim swings to ₹234 Cr loss in Q2 FY27 on one-off AVNB charge, core profit holds
Consolidated revenue grew 25.6% YoY and 2.9% QoQ to ₹50,105 Cr for the quarter ended 30 September 2026, but the headline bottom line swung to a net loss of ₹234 Cr attributable to Grasim's own shareholders (basic EPS -₹3.45), against a restated profit of ₹594.5 Cr a year ago and ₹2,145.9 Cr in Q1 FY27. The swing was driven entirely by a ₹766.73 Cr exceptional charge - a ₹128.72 Cr impairment plus a ₹638.01 Cr provision - against Grasim's exposure to AV Group NB Inc (AVNB), the Canadian joint venture that has temporarily idled its dissolving-grade pulp mill at Nackawic, New Brunswick (the equivalent standalone-level charge was ₹825.43 Cr). Strip that out and the group held up: total profit after tax for the period, before the owners/minority split, was ₹1,029.4 Cr, of which ₹1,263.5 Cr accrued to non-controlling shareholders in UltraTech Cement and Aditya Birla Capital - both majority-but-not-wholly-owned subsidiaries that stayed solidly profitable even as the AVNB charge, booked directly at the parent/JV level, wiped out the owners' share.
No formal Street consensus for this print turned up in search, so a beat/miss call isn't possible. Adjusting for the one-off (which had no prior-year equivalent), owners' PAT comes to roughly ₹535-540 Cr, down about 9-10% on the restated ₹594.5 Cr a year ago - a far more modest decline than the headline loss implies, and consistent with group operating margin holding broadly flat YoY at 12.53% (12.46% a year ago) even as it slipped from 16.14% in Q1. Net profit margin fell to 2.05% from 3.95% YoY and 7.99% QoQ, but that compression is a function of the one-off and the owners/NCI split, not core cost or pricing pressure. Growth was broad-based: Financial Services (Aditya Birla Capital) revenue rose 32.4% YoY to ₹13,990 Cr with segment EBIT up roughly 49% YoY; Cellulosic Fibres grew 28.8% YoY to ₹5,343.5 Cr; Building Materials (cement, paints, B2B e-commerce - mainly UltraTech and Birla Opus) grew 23% YoY to ₹27,378 Cr, though its segment EBIT of ₹3,510.5 Cr fell sharply from ₹5,002.3 Cr in Q1 - a sequential slowdown.
Management's standing guidance - Birla Opus reaching ₹10,000 Cr revenue by FY28 with FY27 growth above 50%, and Birla Pivot hitting EBITDA breakeven at a ₹10,000+ Cr annualized run-rate by FY27 exit - isn't separately verifiable from this result, since both are folded into the Building Materials and Others segments. The only external data point is Q1 FY27 Birla Opus revenue of ₹1,661 Cr (+64% YoY), tracking ahead of pace, but no Q2-specific Opus figure is disclosed here. No standalone management press release was available to cross-check the quarter's framing against the numbers. On the corporate-action side, Grasim repaid ₹750 Cr of commercial paper twice during the quarter (26 October and 4 November), CCI cleared its renewables subsidiary's acquisition of Solenergi Power (not yet consolidated as of 30 September), and the Bombay High Court quashed a ₹329 Cr tax reassessment - balance-sheet-supportive items alongside a consolidated debt-equity ratio of 1.43x this quarter.
Next quarter will show whether the AVNB exposure is now fully provided for and whether owners' PAT reverts to the roughly ₹2,000-2,150 Cr quarterly run-rate seen earlier in FY27. The standalone (parent-only) print of ₹2,306.2 Cr PAT (EPS ₹34.00, up from ₹804.55 Cr YoY and ₹246.65 Cr QoQ) was inflated by a one-time ₹4,120.7 Cr other-income line from subsidiary dividends (vs ₹143.97 Cr in Q1) and isn't representative of ongoing standalone profitability.