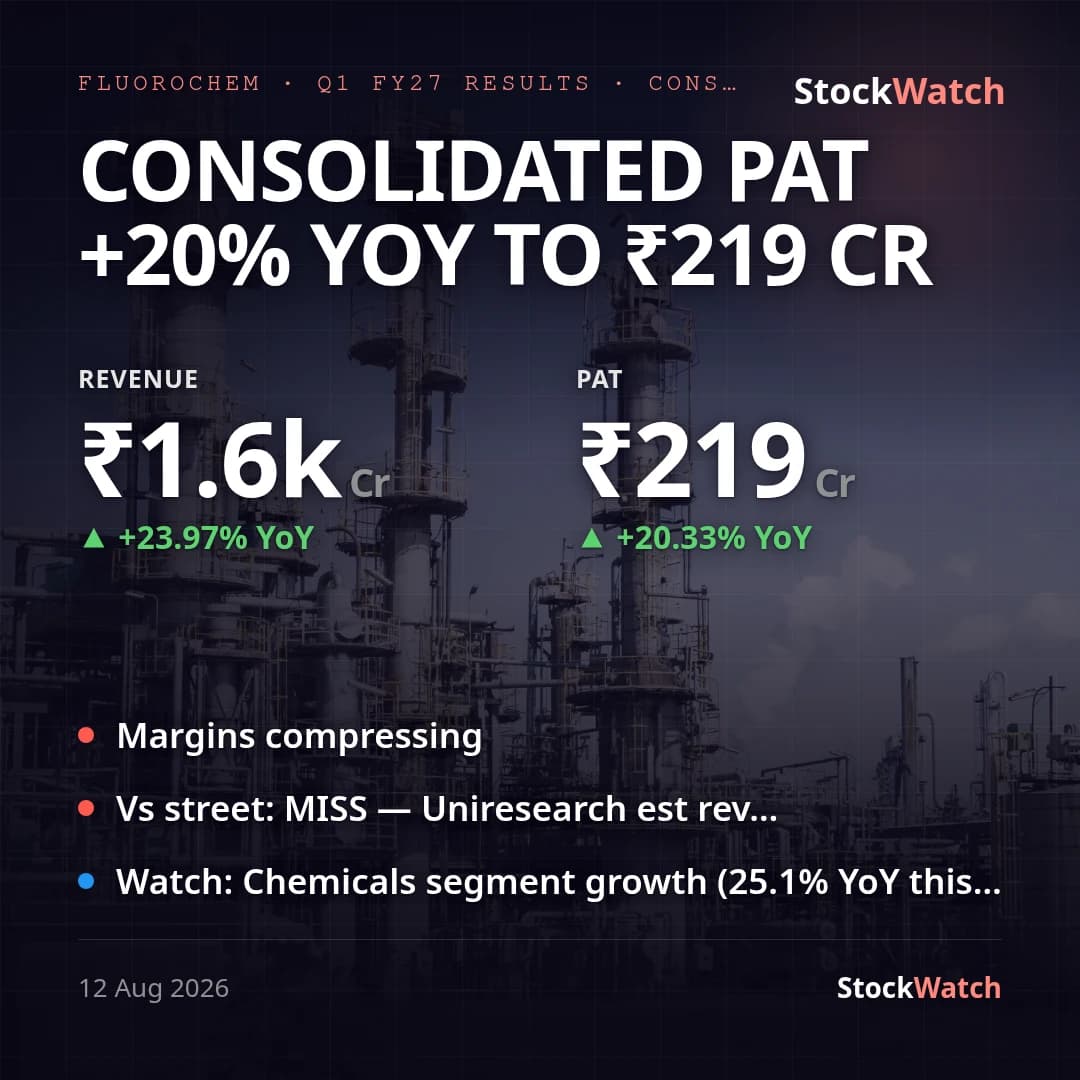
Consolidated PAT +20% YoY to ₹219 Cr, misses Street's ₹276 Cr view; EV losses widen
Gujarat Fluorochemicals' consolidated revenue rose 23.97% YoY to ₹1,588 Cr (+16.0% QoQ from ₹1,369 Cr), comfortably ahead of Uniresearch's Street preview of ₹1,395 Cr (+8.9% YoY). Consolidated PAT of ₹219 Cr grew 20.33% YoY (from a restated ₹182 Cr base; originally reported as ₹184 Cr) but landed roughly 21% below the Street's ₹276 Cr estimate (+50% YoY), making this a revenue-beat/profit-miss quarter. Standalone PAT of ₹201 Cr (EPS ₹18.35) grew only 8.65% YoY versus consolidated's 20.33%, a meaningful basis divergence driven by faster growth in overseas and EV-linked operations that show up only at the consolidated level.
The Chemicals segment carried the quarter: segment PBT rose 34.9% YoY to ₹352 Cr on 25.1% revenue growth (₹1,610 Cr vs ₹1,287 Cr), keeping segment EBITDA broadly stable near 27% of revenue. But the EV Products segment's PBT loss widened to ₹42 Cr from ₹14 Cr a year ago as the battery-materials ramp-up continues, and because those losses attract no deferred-tax benefit, the group's effective tax rate climbed to ~29.4% from ~26.3% YoY — the main reason PAT growth (20.33%) trailed PBT growth (25.5% YoY, to ₹310 Cr) and consolidated net margin slipped to 13.7% from ~14% a year ago.
Against management's FY27 guidance of 15-20% growth in fluoropolymers and a ₹3,150 Cr capex plan (₹2,300 Cr to EV, ₹850 Cr to GFL), the quarter looks on track: Chemicals segment growth of 25% YoY runs ahead of the guided range, and the company funded ₹290 Cr into GFCL EV Products preference shares and ₹52 Cr into Flurry Wind Energy this quarter. No management press-release commentary was available for this filing to cross-check framing. Comparatives were also restated this quarter — Q4FY26 and Q1FY26 consolidated PAT were revised down by ₹9 Cr and ₹2 Cr respectively — after the company derecognised a deferred tax asset at GFCL EV Products (Note 4); this is a non-cash, EV-segment-specific accounting change and does not affect the Chemicals business.
Neither quarter carried an exceptional item, so YoY growth is clean, but the QoQ PAT jump of 119% (off a ₹100 Cr restated base) is a low-base artifact from Q4FY26, which itself carried a ₹3 Cr exceptional charge, and should not be read as sequential momentum. Going forward the print sets up two things to track: whether Chemicals growth holds near the 25% pace or reverts toward the 15-20% guided band, and whether EV Products losses (₹42 Cr PBT loss this quarter) start narrowing toward the FY29 targets of >25% EBITDA margin and 2x asset turns that management has flagged.