StockWatch
·

JAIN IRRIGATION SYSTEMS LTD.

BSE: 500219

P/L Snapshot

Q2 FY27 · standalone

vs Q1 FY27·vs Q2 FY26
Revenue
727.66
+2.4%+4.1%
Expenditure
744.78
+2.3%+7.0%
Net Profit
-14.46
-3.7%-837.8%
OPM %
13.40%
+1.35pp-2.16pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
-146.61178.90504.40829.911.2KQ2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27Q2 FY27
Price Chart
Reports

Jain Irrigation returns to profit (₹18 Cr); 10% revenue growth lags FY27 guidance

agri inputs · micro irrigation · margin recovery

ResultsQ2 FY2704 Nov 20263 minIndustrials & Infra

Jain Irrigation swings to ₹17.8 Cr loss as core agri segment revenue drops 22% YoY

irrigation · agri input · margin compression

ResultsQ1 FY2710 Aug 20263 minIndustrials & Infra
Latest
Quarterly Result4 Nov, 3:32 pm

Jain Irrigation returns to profit (₹18 Cr); 10% revenue growth lags FY27 guidance

On a consolidated basis — the primary number — Jain Irrigation reported PAT of ₹18.01 Cr for Q2 FY27, up 17.4% YoY from ₹15.34 Cr and a sharp swing from the ₹17.80 Cr loss booked in Q1 FY27. Revenue rose 10.1% YoY and 4.5% QoQ to ₹1,576.66 Cr. Basic EPS was ₹0.23 versus ₹0.21 a year ago. The standalone entity told a different story: it swung from a ₹1.96 Cr profit in Q2 FY26 to a ₹14.46 Cr loss this quarter, meaning the group-level improvement was driven entirely by profitable subsidiaries — Agro Processing was the largest revenue segment this quarter at ₹559.01 Cr, ahead of Plastics (₹519.85 Cr) and Hi-tech Agri Inputs (₹497.80 Cr), though Hi-tech Agri remained the most profitable division with a ₹56.08 Cr segment result. Operating margin (EBITDA/revenue) was 13.33%, down marginally from 13.82% a year ago but up sharply from 10.89% in Q1 FY27 — a sequential recovery rather than a YoY expansion. Finance costs rose to ₹119.33 Cr (from ₹115.67 Cr YoY, ₹110.56 Cr QoQ), including ₹21.53 Cr of non-cash interest from unwinding NCD/ECB effective-interest adjustments per the filing notes. Net profit growth outpaced PBT growth mainly because the tax line swung to a net credit of ₹0.09 Cr (a ₹9.84 Cr deferred tax credit against ₹9.75 Cr current tax), not from operating leverage. There were no exceptional items in the current or year-ago quarter, unlike FY26 which absorbed ₹55.33 Cr of one-offs (labour-code impact, subsidiary goodwill de-recognition and a plant-shutdown charge) — so this YoY comparison is clean on both sides. Management's FY26 concall guidance called for 15%+ revenue/EBITDA growth with an 18-20% Q4 FY26 revenue push, and FY27 guidance stepped up further to 18-20% revenue and earnings growth with EBITDA margins targeted at 14-14.5%. Against that, Q2 FY27's 10.1% revenue growth and 13.33% OPM both fall short, so the quarter reads as missing the company's own guided trajectory even as the bottom line recovered. No reliable analyst consensus estimates for this specific quarter turned up in search — only generic commentary that Q2 is seasonally the softest quarter for the company — so the street comparison is unknown rather than beat/miss. Our records show no separate management press release accompanying this filing. On the balance sheet, consolidated cash fell to ₹62.95 Cr from ₹122.07 Cr at FY26-end while current borrowings rose to ₹3,301.77 Cr from ₹3,197.69 Cr; trade receivables eased to ₹2,149.12 Cr from ₹2,273.94 Cr, a partial step toward the government-receivables recovery management had flagged as necessary to fund upcoming debt repayments. The next checkpoints are whether H2 FY27 revenue growth accelerates toward the guided 18-20% band and whether OPM closes the gap to the 14-14.5% target.

4 Nov 2026, 03:32 pm

Quarterly Result10 Aug, 1:28 pm

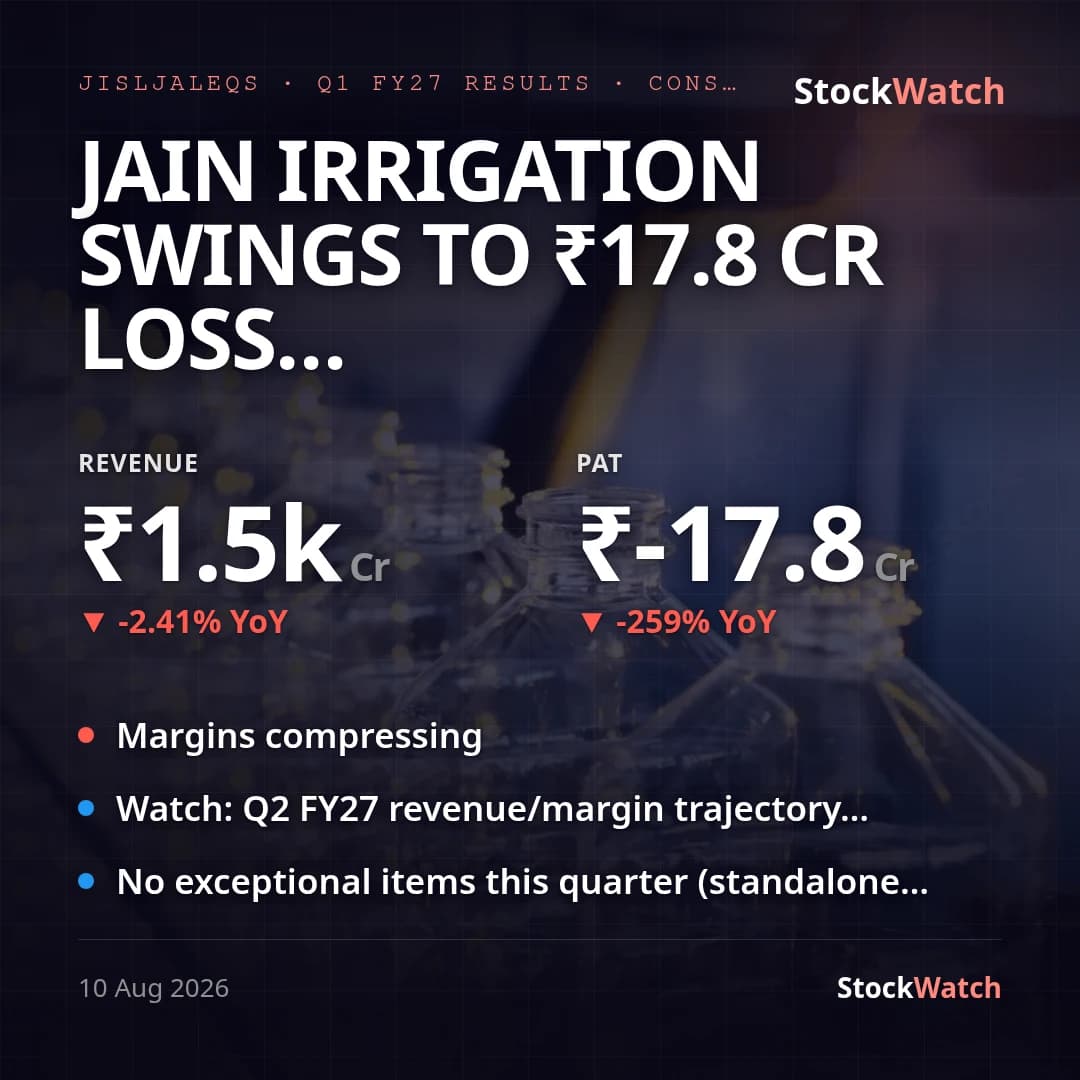
Jain Irrigation swings to ₹17.8 Cr loss as core agri segment revenue drops 22% YoY

Jain Irrigation's consolidated revenue came in at ₹1,508.37 Cr for Q1 FY27, down 2.4% YoY and 17.3% QoQ (Q1 is seasonally the softest quarter versus Q4). The group swung to a net loss of ₹17.80 Cr (owners' share ₹14.93 Cr, EPS -₹0.20) against a profit of ₹11.19 Cr in Q1 FY26, though the loss narrowed marginally from Q4 FY26's ₹19.04 Cr. Standalone results mirrored this, flipping to a ₹13.94 Cr loss from a ₹7.06 Cr profit YoY. The drag is concentrated in the Hi-Tech Agri Input segment (irrigation systems, solar pumps) — the group's largest by result — where revenue fell 22.0% YoY to ₹450.79 Cr and segment result collapsed 54.7% YoY to ₹25.89 Cr. Agro Processing (foods/beverage) bucked the trend on revenue, up 19.7% YoY to ₹547.73 Cr, but its segment result still fell 38.7% YoY to ₹22.13 Cr, and Plastics was roughly flat. Total segment result fell 35.2% YoY to ₹91.10 Cr, and consolidated operating margin (OPM, PBT-before-exceptional + finance cost + depreciation, over revenue) compressed to roughly 11.6%, down from 13.07% a year ago and 12.06% last quarter. A ₹8.07 Cr tax charge on a ₹9.73 Cr pre-tax loss — including ₹9.91 Cr of current tax, reflecting profitable subsidiaries paying tax even as the group posts a loss — widened the bottom-line loss further. The result runs well behind management's own framework: at the February 2026 concall the company guided to 15%+ FY26 revenue/EBITDA growth, 18-20% Q4 alone, and for FY27 targeted 18-20% revenue/earnings growth with EBITDA margins improving to 14-14.5% — against which a 2.4% YoY revenue decline and ~11.6% margin in the very first quarter of that guided year is a clear miss. No management press release or updated commentary was available in the context to reconcile this against; the August 10 concall (scheduled same day as this filing) should clarify whether the FY27 targets are being walked back. Web searches for street/consensus estimates on this specific print turned up no numeric brokerage previews for Q1 FY27 — vsStreet is marked unknown rather than guessed. Consolidated and standalone tell the same directional story (both swing to loss), so there is no material divergence to flag. Going into Q2, the key markers are whether Hi-Tech Agri Input volumes recover with the monsoon progression, whether OPM stabilises toward the 14-14.5% FY27 target management set out, and progress on the previously flagged ₹688 Cr sustainable-debt repayment planned for H2 FY27 via internal accruals and asset monetisation — none of which this filing updates.

10 Aug 2026, 01:28 pm

Corporate Events

Board MeetingJISLJALEQS
2026
4Nov

Board Meeting

The Board of Directors meeting is scheduled to review, final…

BSE Filing ↗
Board MeetingJISLJALEQS
2026
10Aug

Board Meeting

The Board of Directors meeting is scheduled to review, final…

BSE Filing ↗
Board MeetingJISLJALEQS
2026
14Jul

Board Meeting

The Board of Directors considered and approved the re-appoin…

BSE Filing ↗
Board MeetingJISLJALEQS
2025
26Jul

Board Meeting

review, finalize, approve and recommend the Unaudited Standa…

BSE Filing ↗
Board MeetingJISLJALEQS
2025
14May

Board Meeting

Review, finalize, approve and recommend the Audited Standalo…

BSE Filing ↗
Board MeetingJISLJALEQS
2025
15Apr

Board Meeting

Trading Window closure

BSE Filing ↗
Board MeetingJISLJALEQS
2024
28Oct

Board Meeting

Notice of meeting, Review, finalize, approve and recommend U…

BSE Filing ↗
Board MeetingJISLJALEQS
2023
9Nov

Board Meeting

Approval of H1/Q2 FY 2024 Unaudited Financial Working Result…

BSE Filing ↗
Board MeetingJISLJALEQS
2023
17Aug

Board Meeting

36th AGM Notice and related reports of Board, operations for…

BSE Filing ↗
Board MeetingJISLJALEQS
2023
8Aug

Board Meeting

to consider and approve Notice of meeting of Board of Direct…

BSE Filing ↗