Jindal Stainless's consolidated PAT for Q2 FY27 (quarter ended 30 September 2026) was ₹897.75 Cr, up 11.1% YoY from ₹807.92 Cr and up 16.8% QoQ from ₹768.66 Cr, on revenue of ₹12,873.86 Cr (+18.2% YoY, +14.1% QoQ). But both this quarter and the year-ago quarter carried exceptional gains (₹116.41 Cr now vs ₹17.41 Cr then); stripping these out on an approximate post-tax basis, underlying YoY PAT growth is only ~2%, not the 11% headline — a steady, not strong, quarter. Basic EPS was ₹10.85 vs ₹9.80 a year ago. Standalone PAT, by contrast, grew a faster 22.0% YoY to ₹785.50 Cr (vs ₹643.89 Cr) — the gap versus consolidated growth reflects how subsidiaries and equity-method associates consolidate into the group number; consolidated remains the primary basis for this read.
Operating margin compressed to 11.13% from 12.74% a year ago and 11.78% last quarter; net margin fell to 6.97% from 7.42% YoY. The compression traces to raw materials: cost of materials consumed rose to roughly 75.4% of revenue from about 67.8% a year ago, outpacing the topline increase, with power & fuel costs also higher in absolute terms (₹865.06 Cr vs ₹684.66 Cr YoY). The exceptional gain of ₹116.41 Cr was driven mainly by a ₹95.63 Cr write-back of excess provisions under Haryana's one-time settlement scheme for long-disputed Local Area Development Tax/Entry Tax demands, after the company opted to settle at ₹101.72 Cr in tranches (note 10).
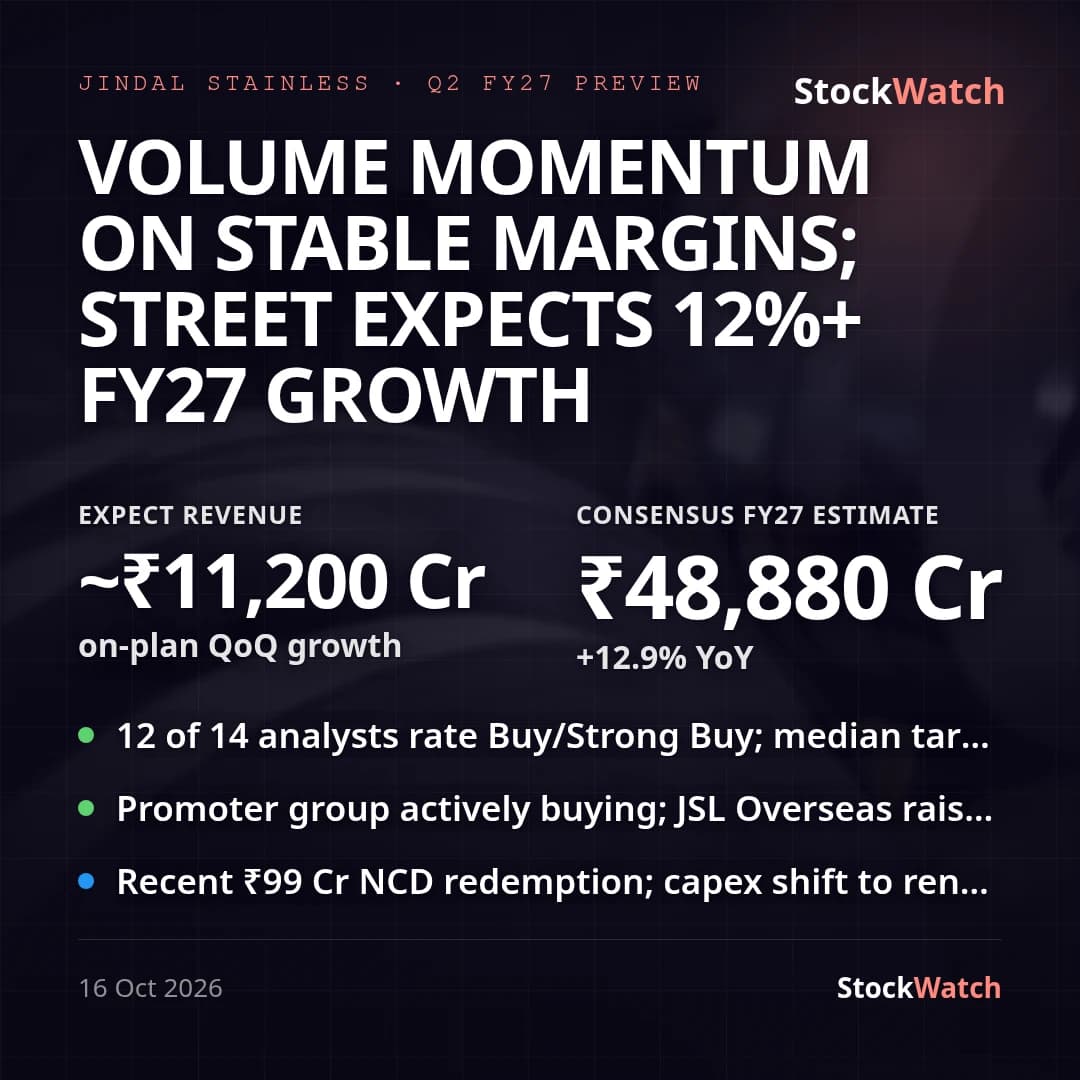
Against our pre-result preview, which expected Q2 revenue of ~₹11,200 Cr and a stable 12-13% EBITDA margin, the quarter beat on revenue (₹12,874 Cr, about 15% above expectation) but missed on margin (11.13% operating margin, below the expected range) — so the core margin-recovery debate Street flagged (Goldman/ICICI bullish on margin and volumes, Prabhudas Lilladher cautious on commodity headwinds) tilts toward the cautious camp this quarter. On guidance, management's FY27 capex target of ₹2,400-2,600 Cr looks on track — H1 consolidated capex (PP&E/CWIP purchases) was ₹1,521.34 Cr, roughly half the full-year range — but the H1 EBITDA-per-tonne target of ₹18,000-20,000 and the FY27 volume-growth guidance deferred to this quarter cannot be verified from this filing, which discloses no tonnage data; that silence is itself notable given volume run-rate was one of the watch items flagged pre-result. Corporately, the Board also approved a composite scheme amalgamating four wholly-owned subsidiaries (Chromeni Steels, Rabirun Vinimay, JSL Super Steel, Jindal United Steel) into the company effective 1 April 2027 to simplify the group structure, alongside the October 16 renewable-energy SPV stake acquisition. No management press release/MD&A accompanied this filing beyond the regulatory results and notes, so this read rests on the reported numbers themselves.
Minority interest rose to ₹3.17 Cr this quarter from ₹0.98 Cr a year ago, reflecting the expanding subsidiary base being consolidated ahead of the planned amalgamation. Into Q3, the open items are whether raw-material cost pressure eases enough to pull operating margin back toward last year's ~12.7% level, and whether management finally discloses the volume-growth figure it deferred from the last concall.