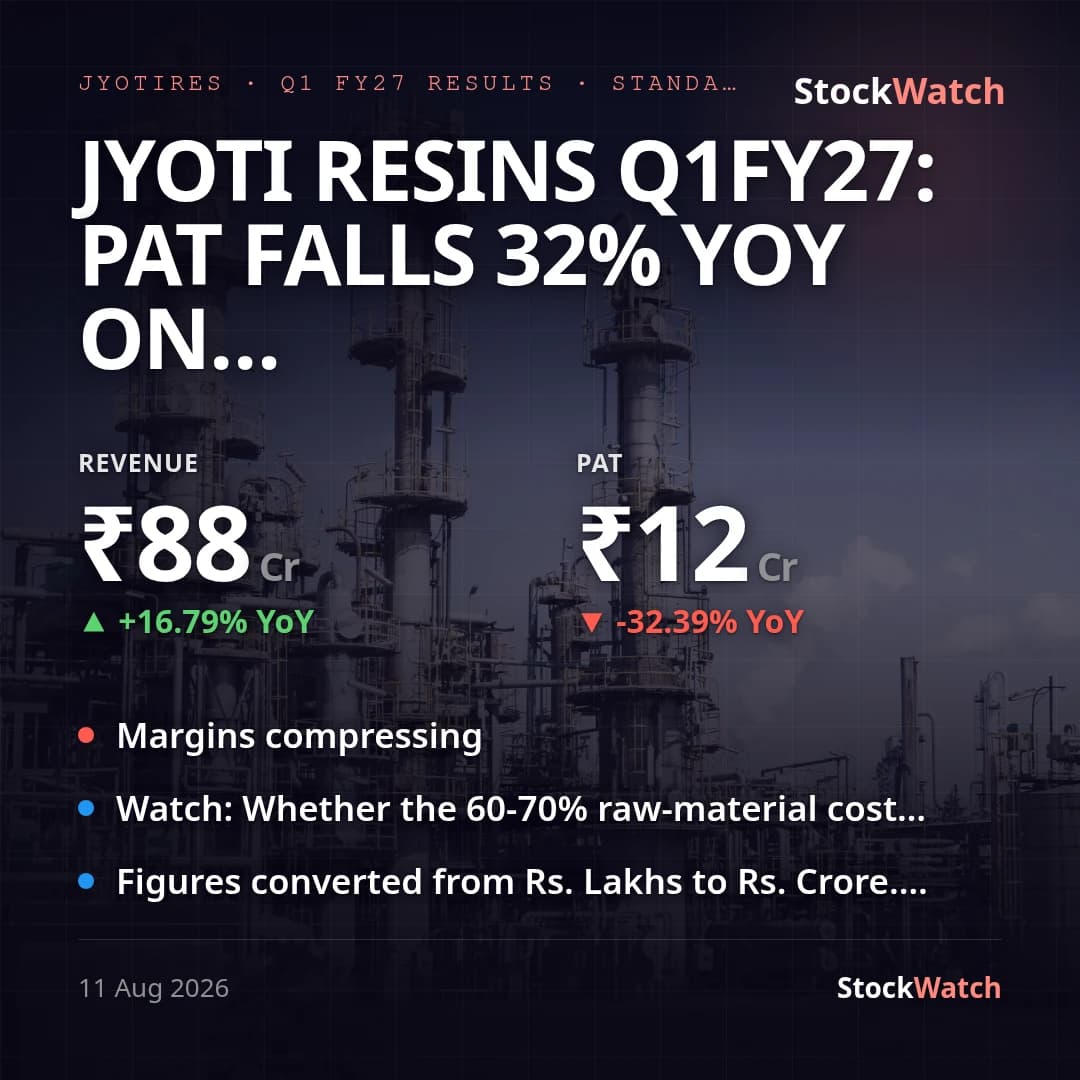
Jyoti Resins Q1FY27: PAT falls 32% YoY on margin squeeze despite 17% revenue growth
Jyoti Resins & Adhesives reported standalone Q1 FY27 (quarter ended June 30, 2026) revenue of Rs.87.71 Cr, up 16.8% YoY but down 5.6% QoQ off a seasonally strong Q4. Net profit fell sharply on a YoY basis to Rs.11.75 Cr, down 32.4% from Rs.17.38 Cr a year ago and down 41.5% sequentially from Rs.20.08 Cr — a clear case of the topline growing while profitability shrank, which is the story of the quarter, not the revenue print. No exceptional items appear in the current or comparable periods, so this is a clean, unadjusted decline rather than a one-off distortion.
The compression sits squarely on the cost-of-materials line: cost of materials consumed jumped to Rs.52.21 Cr, 59.5% of revenue, versus Rs.23.75 Cr (31.6% of revenue) a year ago and Rs.30.88 Cr (33.2% of revenue) last quarter. Operating margin (PBT plus finance cost and depreciation, less other income, over revenue from operations) fell to 14.42% from 27.48% YoY and 26.87% QoQ; net margin on total income fell to 12.91% from 22.24% YoY and 21.04% QoQ. This matches management's own Q4 FY26 concall warning of 'significant near-term margin pressure in Q1 due to a sharp rise in raw material costs' — the guidance was directionally met, though the severity (margins roughly halving YoY) is steep even against that warning, and the current 12.91% NPM sits below the 18-22% steady-state net-margin range the company has separately guided toward for FY27 as it works to pass on 60-70% of the raw-material cost increase via price hikes effective May 2026. No formal Street consensus for this micro-cap's Q1 FY27 print was found in a web search; the only external reference located was a standing 'buy' call with a Rs.1,764 target based on 22x FY27e earnings, which is a full-year thesis, not a quarterly estimate, so vsStreet is left unknown rather than inferred. Management's own press commentary on this specific result was not available in the filing to quote directly. EPS (basic) came in at Rs.10 for the quarter versus Rs.14 YoY and Rs.17 QoQ, tracking the profit decline.
The quarter's other corporate context — the Board approving these results and taking the limited review report (unqualified, from R Kabra & Co LLP) on record on August 11, 2026, and the company's June 27, 2026 announcement of plans for a direct NSE listing — are procedural/strategic items that don't bear directly on this quarter's operating numbers. Sets up FY27 as a margin-recovery story: whether the raw-material pass-through restores OPM toward the long-term-guided 23-25% EBITDA margin band, and whether the previously flagged elevated receivables normalize within the two quarters management targeted, are now the two things to track against a still-healthy 16.8% YoY revenue growth trend.