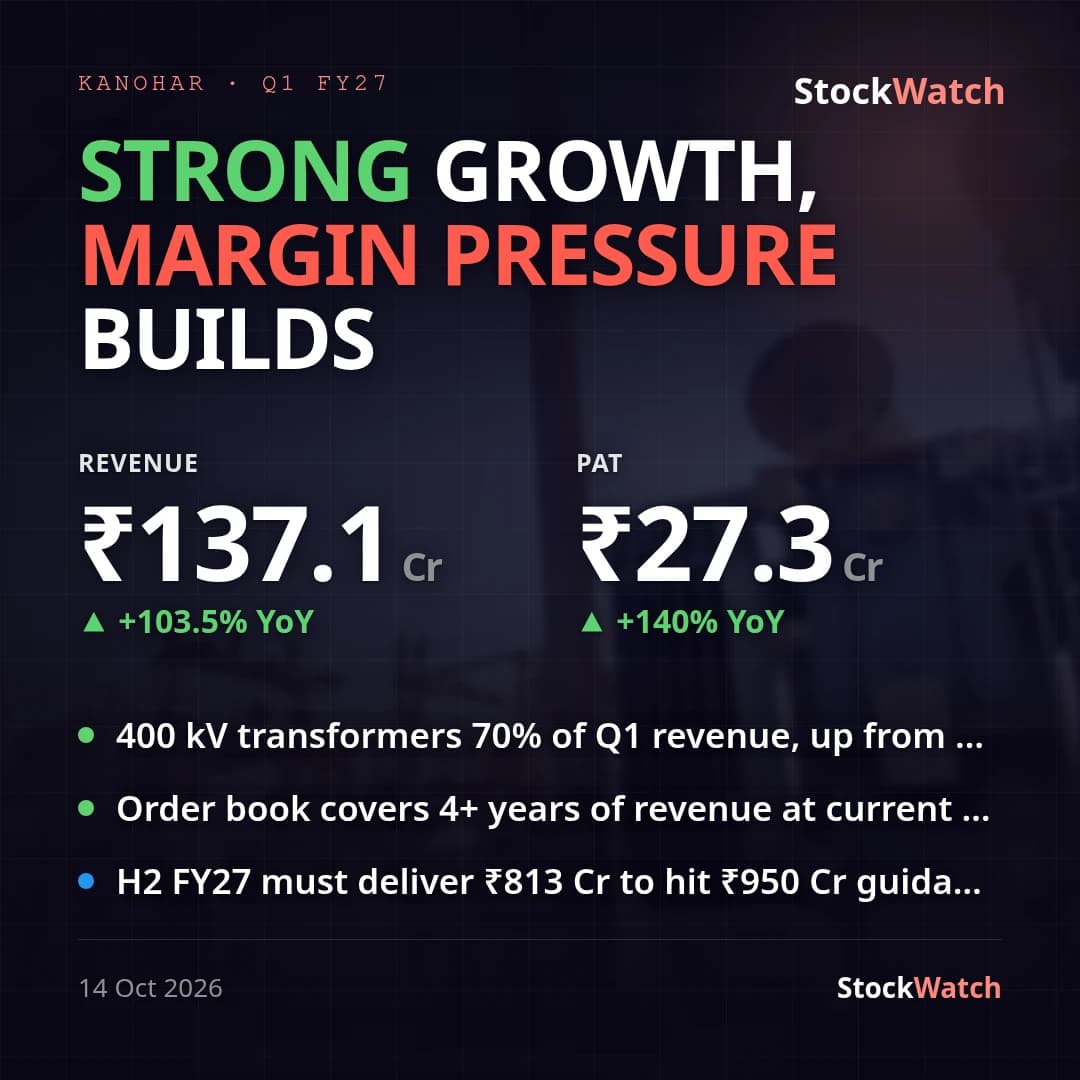
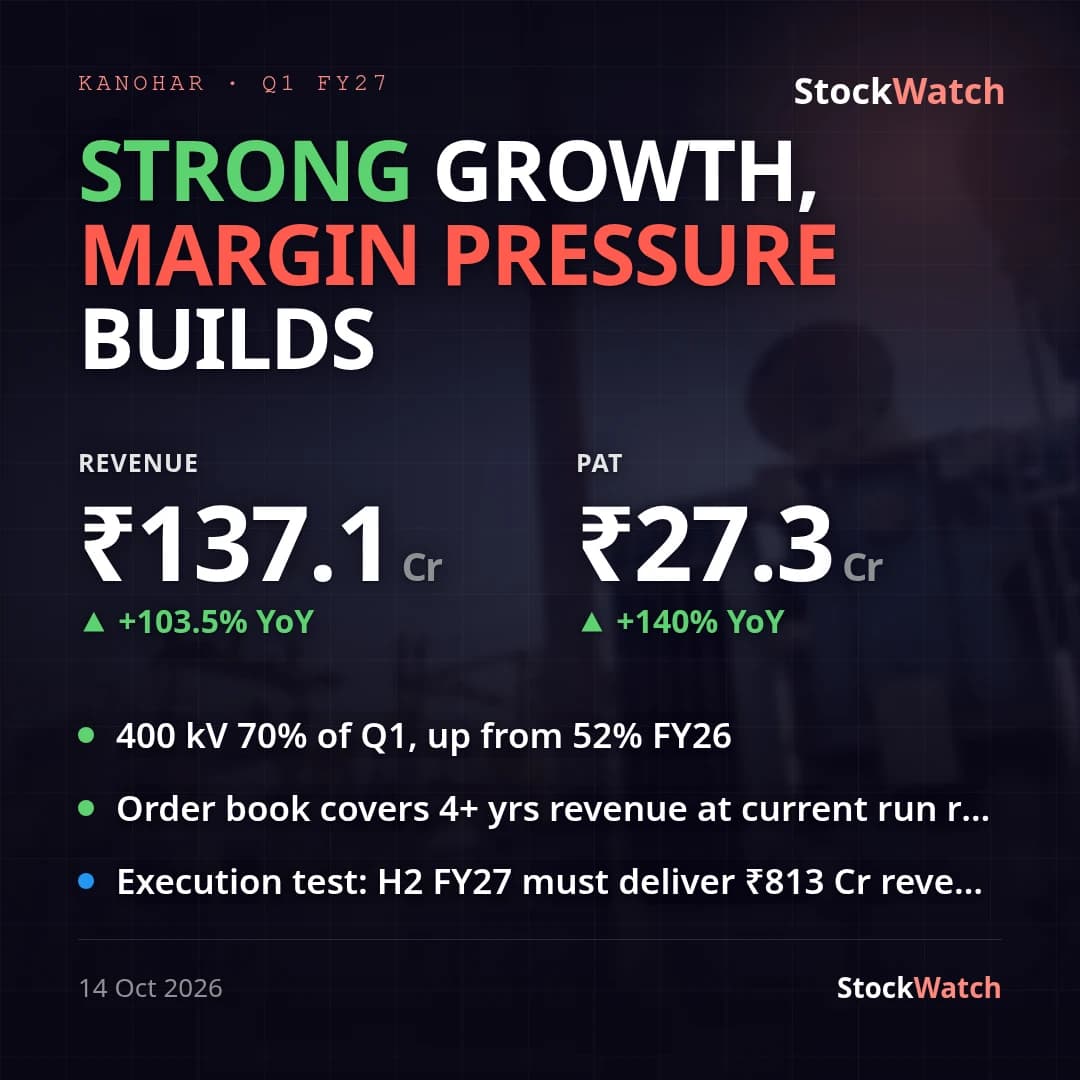
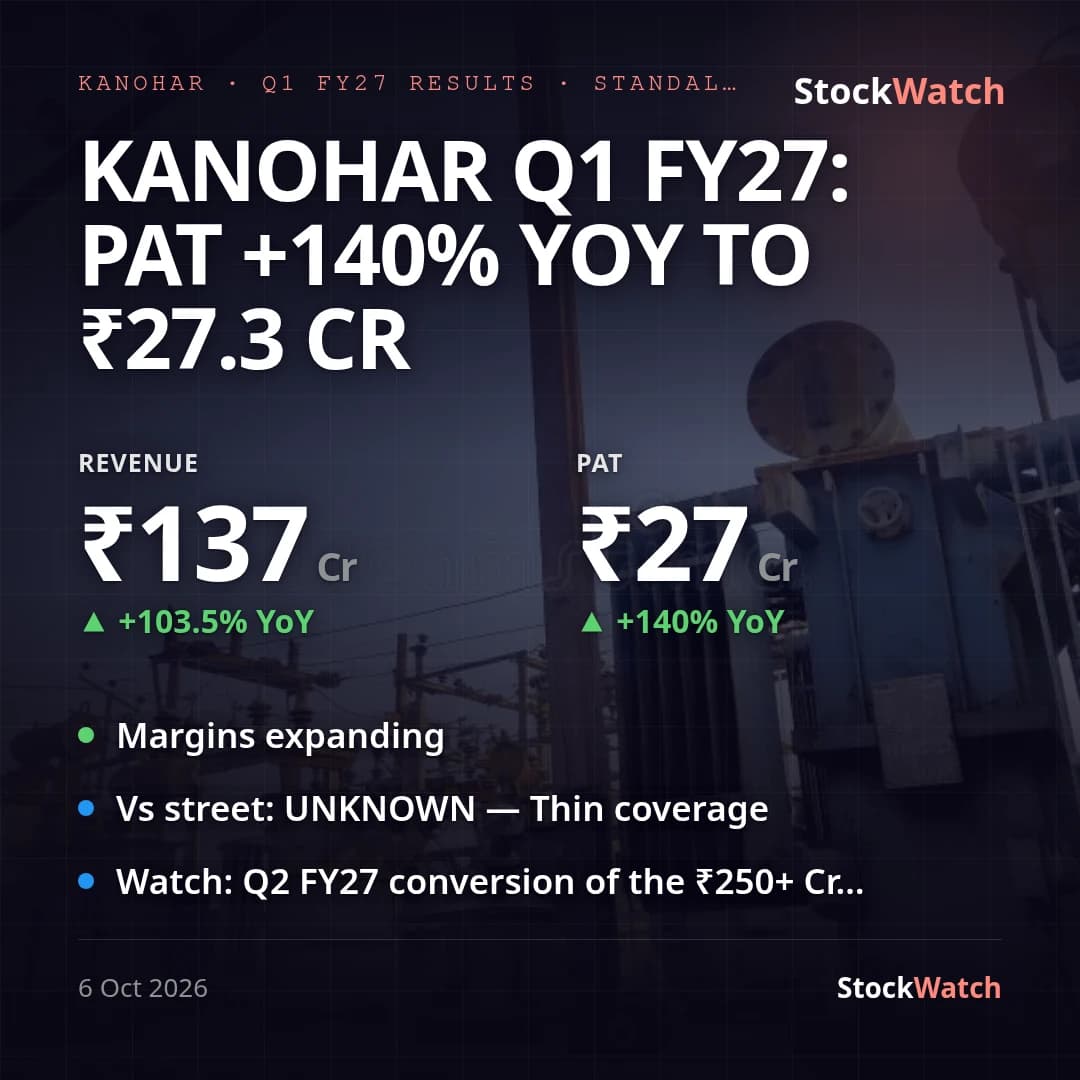
Kanohar Q1 FY27: PAT +140% YoY to ₹27.3 Cr, margins expand; sharp QoQ fall vs Q4 peak
Kanohar Electricals' maiden quarterly print as a listed company (shares debuted on BSE/NSE on September 16, 2026 after a ₹1,056 Cr IPO — ₹755.74 Cr OFS plus ₹300 Cr fresh issue) shows standalone revenue of ₹137.08 Cr for the quarter ended June 30, 2026, up 103.5% year-on-year from ₹67.37 Cr, with PAT up 140% YoY to ₹27.34 Cr from ₹11.39 Cr. Net profit margin expanded to 19.95% from 16.91% a year ago (+304 bps), and EBITDA margin (PBT plus finance cost and depreciation, less other income) rose to roughly 28.3% from 22.8% (+550 bps). The expansion is operating-leverage driven, not materials-cost driven: employee expense fell to 7.1% of revenue from 10.7% YoY and other overheads to 6.6% from 9.7%, more than offsetting a slightly higher raw-material/purchases ratio (58.1% of revenue versus 56.8% a year ago).
Sequentially, revenue and PAT fell 54.1% and 56.3% respectively against March quarter (Q4 FY26) levels of ₹298.97 Cr revenue and ₹62.63 Cr PAT — unsurprising given FY26's Q4 alone made up roughly 44% of the full year's ₹653.84 Cr revenue, consistent with project-linked, year-end-weighted execution typical of power-equipment manufacturers; this is a timing effect, not a reversal, and should not be read as a demand slowdown.
There is no formal management guidance on record, and no separate management press release accompanied this filing, so neither can be graded directly. Street coverage remains thin (one analyst tracked per our pre-result note); no absolute analyst revenue/PAT estimate for this quarter turned up in a web search, but the realised 19.95% NPM sits squarely inside the pre-result preview's indicated 19–20% PAT-margin band, even though that preview's revenue figure itself cannot be reconciled with the company's actual scale. The quarter's other disclosed developments — a ₹250+ Cr 400kV transformer order win on September 30 (after this quarter closed), a new RTA (MUFG Intime), a newly appointed Company Secretary, and the Fair Disclosure Code filing — are governance/listing housekeeping and an early order-book data point rather than drivers of this print; the order win will instead be a Q2 FY27 revenue/margin test.