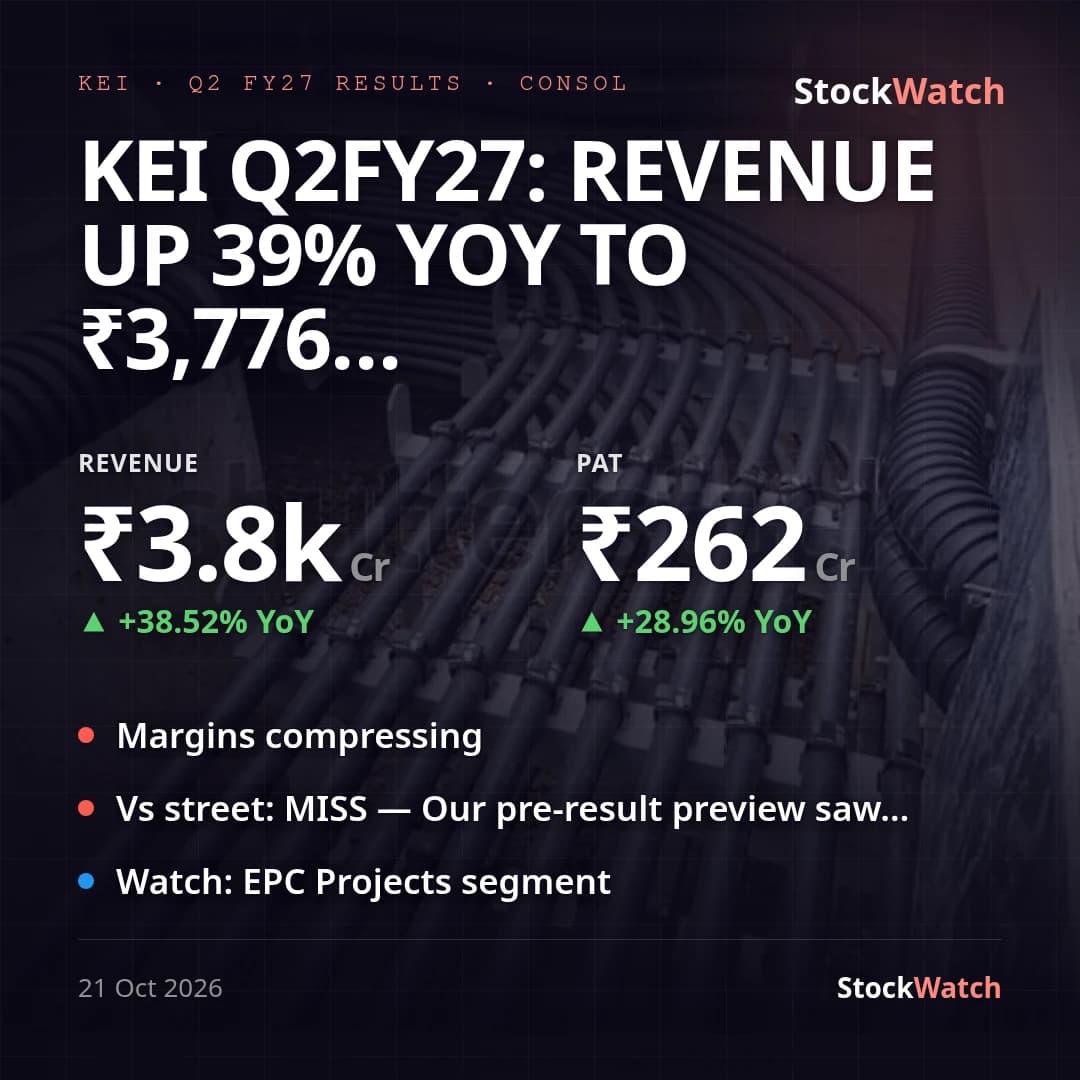
KEI Q2FY27: Revenue up 39% YoY to ₹3,776 Cr, PAT misses Street as EPC swings to loss
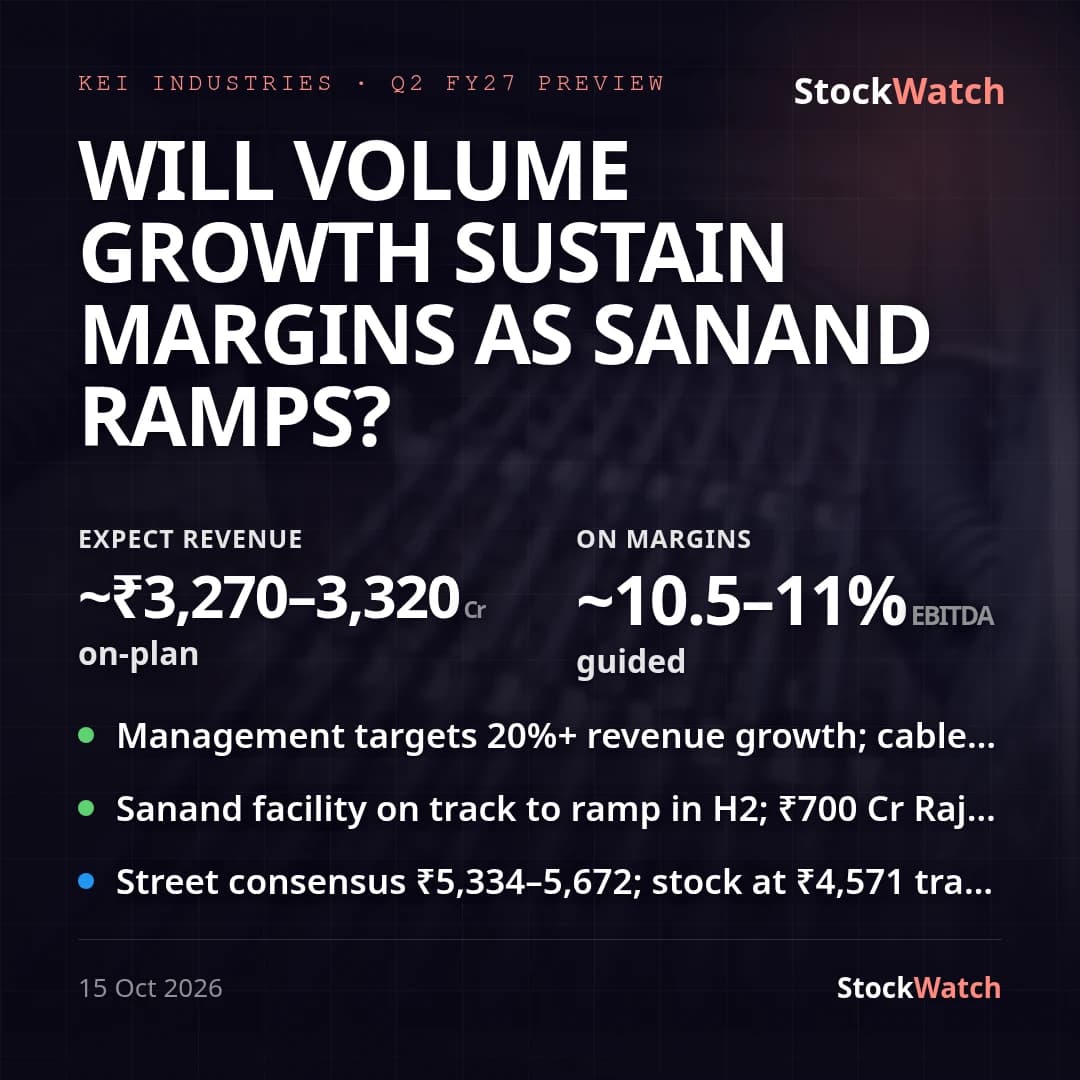
KEI Industries posted consolidated revenue of ₹3,776.42 Cr for Q2FY27, up 38.5% YoY (+18.6% QoQ) and well ahead of our pre-result preview band of ₹3,270–3,320 Cr. Consolidated PAT of ₹262.45 Cr grew 29.0% YoY but fell 4.3% QoQ, and came in 24–28% below the ₹343–364 Cr pre-result estimate — a clear miss on the bottom line even as the top line beat. Basic EPS was ₹27.45, down from ₹28.68 in Q1FY27 but above ₹21.30 a year ago.
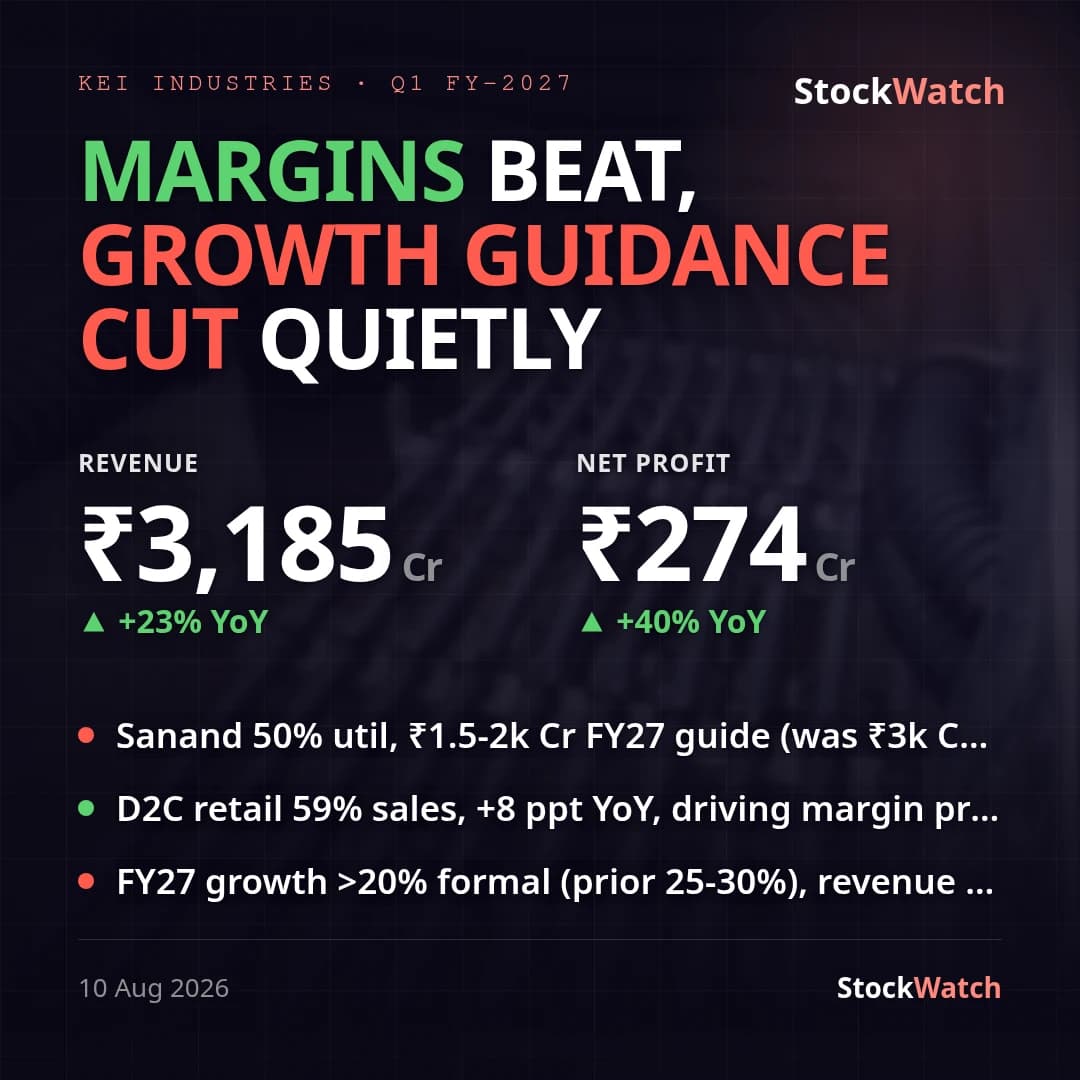
The miss traces to the EPC Projects segment, which swung to a segment loss of ₹8.93 Cr versus a ₹5.13 Cr profit in Q2FY26, dragging consolidated net segment results even as the core Cables & Wires business grew revenue 39.7% YoY to ₹3,685.22 Cr with segment margin steady-to-better at ~11.3% (from ~10.9% a year ago). Layered on top, finance costs rose 20% YoY to ₹103.3 Cr and depreciation rose 51% YoY to ₹30.6 Cr as capital work-in-progress (₹1,271.9 Cr, roughly double the ₹634 Cr segment-asset base a year ago) builds out the Sanand and new Salarpur capacity. Net result: consolidated net margin slipped to roughly 6.9% of revenue, down from 8.55% in Q1FY27 and 7.35% in Q2FY26 (per our records) — a YoY and QoQ compression, since PAT grew slower than revenue on both counts.
Against management's own guidance, the quarter is ahead: H1FY27 revenue grew 31.0% YoY to ₹6,961.76 Cr, above the raised >25% FY27 revenue bar (up from an original >20%), and H1 segment-result margin of ~11.9% of revenue from operations sits inside the raised 11–12% operating-margin guidance band — so on management's own metrics this reads as on-track-to-beat, even though it missed our Street-level PAT estimate. No standalone management press release was available for this filing to cross-check framing beyond the board-meeting letter and the financial statements themselves. Within this quarter's other developments, the GST demand was reduced by ₹4.46 Cr (immaterial to the P&L) and the company received a separate ₹17.1 lakh GST demand order; neither is financially significant. More material is the Income-Tax search conducted in May 2026, which the auditors' limited review flags again this quarter as unresolved, with impact 'not ascertainable' — a disclosed but unquantified overhang. The ₹2,000 Cr QIP from November 2024 continues to fund the capacity build, with ₹162.9 Cr still unutilised and parked in bank deposits/monitoring account.
Going into Q3, the swing factor is whether the EPC segment returns to profit, whether operating margin holds near the 11–12% guided band as Sanand ramps, and whether the Income-Tax search resolves with a quantified (rather than open-ended) impact.