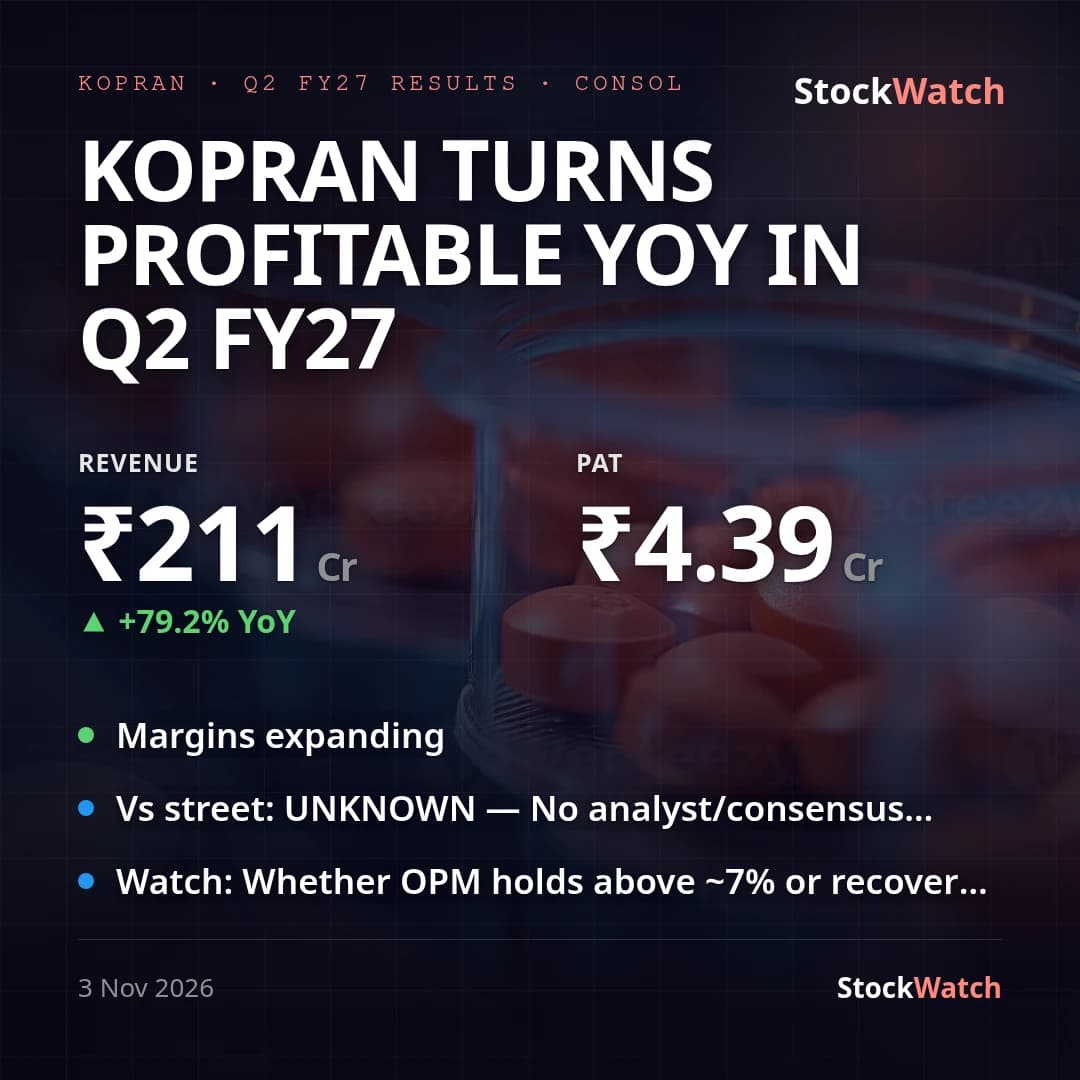
Kopran turns profitable YoY in Q2 FY27 — consol PAT ₹4.4 Cr vs loss; revenue up 79%
Kopran's consolidated Q2 FY27 (quarter ended September 30, 2026) print is a clean year-on-year turnaround: PAT of ₹4.39 Cr against a ₹9.92 Cr loss in Q2 FY26, on revenue up 79.2% YoY to ₹211.26 Cr. Neither period carries exceptional items, so the swing is operating, not one-off driven. Sequentially, though, the quarter cooled off — PAT fell 34.4% from ₹6.70 Cr in Q1 FY27 even as revenue kept climbing 37.2% QoQ, and OPM slipped to ~7.3% from 10.3% in Q1 FY27 (still well above the -4.5% a year ago), with NPM easing to 2.1% from 4.3% QoQ. Standalone tells a better bottom-line story — PAT of ₹6.29 Cr (EPS ₹1.30) versus the group's ₹4.39 Cr (EPS ₹0.91) — a gap the auditor's limited review traces to roughly a ₹2.1 Cr quarterly net loss at one overseas subsidiary; readers comparing the two numbers should note this is why they diverge rather than assume an error.
There is no prior guidance or concall commentary on record for Kopran, and a web search turned up no analyst or consensus estimates for this quarter either — both the guidance and street checks resolve to unknown for lack of coverage on this smallcap. The margin give-back sits mainly in the cost lines rather than other income: finance costs and depreciation both grew faster than other income on a rising capex and borrowings base, consistent with the company scaling up even as near-term profitability gave back part of Q1's gain. The quarter's one concrete regulatory datapoint — the EU GMP inspection at the Khopoli facility concluding successfully on October 22, 2026 — is a relevant quality-compliance signal alongside this quarter's growth, though the filing reports a single pharmaceuticals segment under Ind AS 108 with no revenue break-up to size its contribution. No management press release was available to cross-check against the reported numbers.