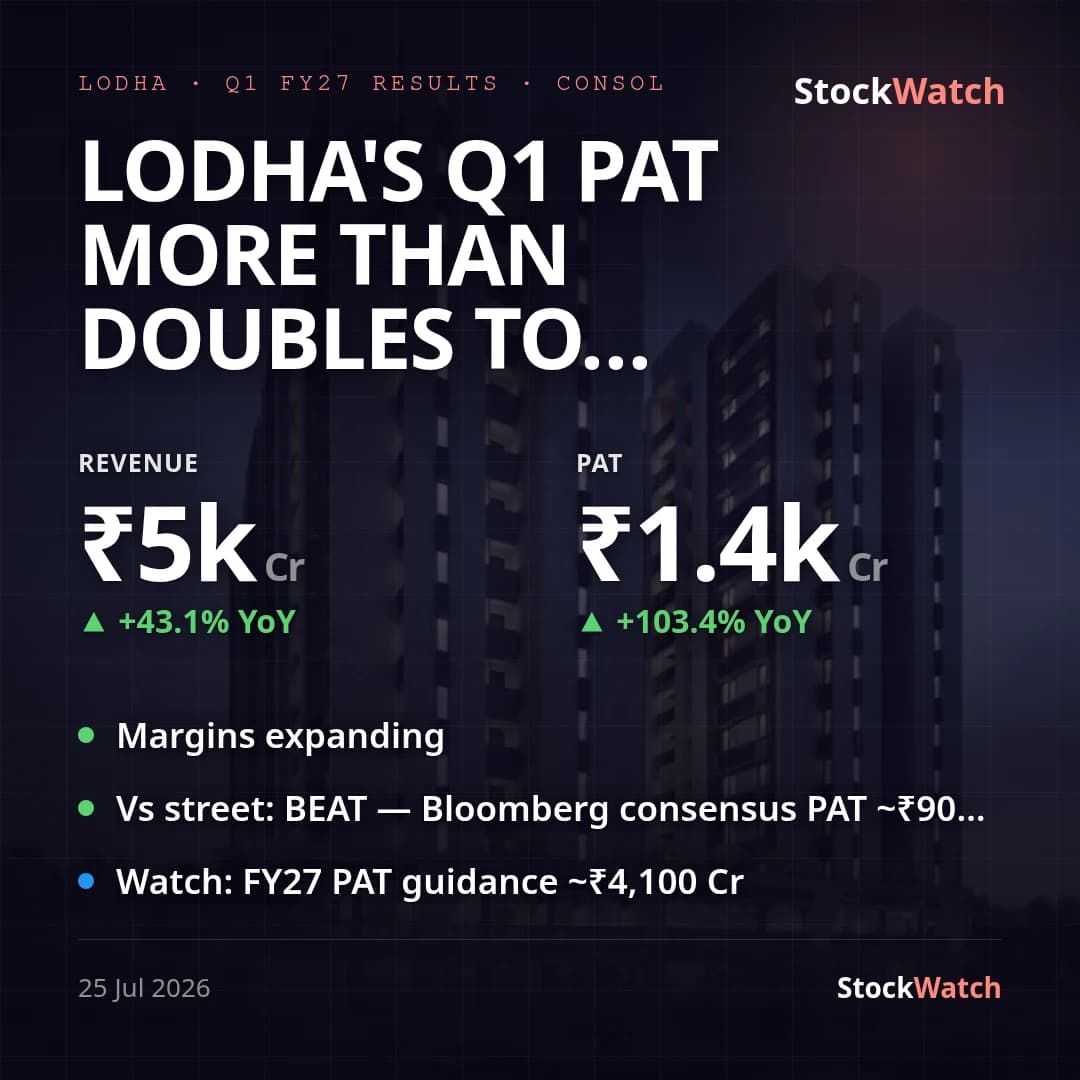
Lodha Developers (formerly Macrotech) delivered its best-ever quarter, with consolidated PAT more than doubling YoY to ₹1,373.1 Cr (₹1,372.1 Cr to owners) from ₹675.1 Cr, on revenue from operations of ₹4,996.7 Cr, up 43.1% YoY. Sequentially, profit rose 36% and revenue 6% over Q4 FY26's ₹1,008 Cr / ₹4,713 Cr. The print blew past the street: the Bloomberg consensus PAT was ~₹907 Cr, so actual profit beat by roughly 51%. Crucially, there are no exceptional items on either side of the comparison — the doubling is entirely underlying, driven by higher revenue recognition and collections rather than any one-off.
The story is as much margin as topline. Net profit margin (PAT/total income) expanded to ~26.9% from ~20.8% a year ago, and EPS doubled to ₹13.73 from ₹6.76. Operating leverage is visible: total expenses grew ~22% against 43% revenue growth, and the cost-of-projects line rose only ~21% YoY, widening the gross spread as higher-margin completed inventory was recognised. Standalone (secondary) told a directionally identical story — PAT ₹1,049.5 Cr on revenue ₹4,377.9 Cr (+31% YoY) — with no material divergence in the growth narrative, so readers seeing the standalone number elsewhere should not treat either as wrong.
Against guidance, the quarter is a strong start: management's FY27 PAT guide is ~₹4,100 Cr, and Q1 already banks ₹1,373 Cr (~33%), ahead of a proportionate run-rate for a business whose deliveries typically skew to H2. This aligns with the strategic pivot management flagged last quarter — shifting the primary focus to profitability (20% PAT CAGR to >₹8,500 Cr by FY31), supported by lower business-development capex and rising free cash flow. Balance-sheet discipline held: consolidated net debt/equity eased to 0.20 from 0.25 a year ago. Management framed it as "our best-ever quarterly profit… profits more than doubled YoY," and the numbers corroborate that claim without embellishment. The FY27 presales target of ₹240 bn (17% growth, 32-34% embedded EBITDA margin) is an operational metric not captured in this P&L and remains the key thing to verify in coming quarters — as does whether the H2-weighted delivery schedule sustains the annual PAT run-rate.